



US open: Stocks move higher, jobless claims hit 8-week high
US stocks extend gains and USD continues to fall. Jobless claims are at the the highest level since mid-November.
Share this:

US futures
Dow futures +0.26% at 36396
S&P futures +0.2% at 4735
Nasdaq futures +0.3% at 15953
In Europe
FTSE +0.28% at 7561
Dax +0.39% at 16057
Euro Stoxx +0.25% at 4328
Learn more about trading indices
Inflation, jobless claims and rate hike in focus
US stocks are set to open higher after booking mild gains in the previous session. The debate over inflation and interest rates continues after CPI rose to 7% in the previous session. Today PPI inflation rose to 9.7% in December, up from 9.6% but short of the 9.,8% forecast.
Jobless claims unexpectedly rose to 230k, up from 207k, marking the highest number of initial claims since mid-November. The increase comes as COVID cases surged. However, the rate of initial jobless claims is still reflective of a rapidly tightening labour market. Let’s not forget that there were still 10.6 million job vacancies in the US at the end of November.
The broad expectation is that the Fed will hike 4 times across the coming year starting in March. The data this week has been consistent with this expectation so no additional Fed fears have shown up in the market
In corporate news:
Boeing is trading 2.5% higher pre-market on reports that the troubled 737 MAX jet could begin service in China as soon as this month.
Taiwan Semiconductor Manufacturing rose 4.4% after the chip maker reported a record quarterly profit amid surging demand.
Where next for the Nasdaq?
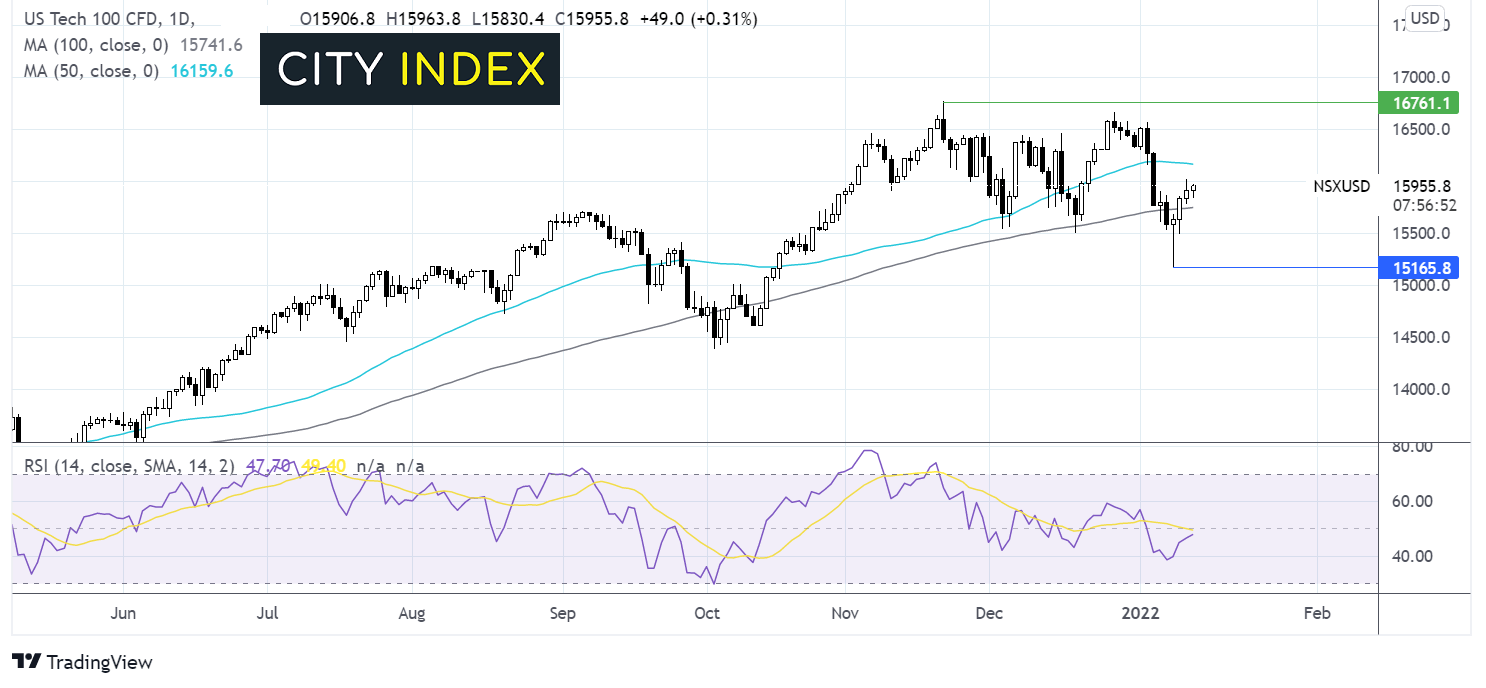
The Nasdaq continues to extend its rebound from 15165 reached earlier in the week. The move above above the 100 sma is keeping buyers hopeful. However, the RSI is in neutral territory. Buyers might look for a move over 50 sma at 16150 in order to look towards 16760. Sellers could watch for a move below the 100 sma. It would take a move below 15165 for sellers to gain tracton.

FX markets USD falls, GBP rises
The USD is falling for a third straight session. DXY has dropped 1.2% in 3 days even as CPI hits a 40 year high. PPI rises less than expected and jobless claims rise, hurting demand for the greenback.
GBP/USD has risen above 1.37 as senior cabinet ministers have rallied around Boris Johnson, who has so far managed to cling onto power
GBP/USD +0.20% at 1.3727
EUR/USD +0.34% at 1.1463
Oil eases but remains around its two month high
Oil prices are edging mildly lower but stays close to two-month highs after booking solid gains over the past two sessions. The weaker USD is helping the greenback priced commodity in addition to the improved demand outlook, even as Omicron cases rise. Any impact from Omicron is expected to be short lived.
EIA inventory data revealed that crude oil supplies fell by 4.6 million barrels, significantly more than the 1.6 million decline forecast. This came after the API report reported a 1.1 million barrel decline.
However, the EIA also reported an 8 million barrel increase in gasoline inventory, most likely owing to the Omicron impact.
WTI crude trades -0.3% at $81.73
Brent trades -0.12% at $84.11
Learn more about trading oil here.
Looking ahead
15:00 Fed Brainard speech
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.