



US open: Stocks point higher, boosted by upbeat earnings
US stocks are set to extend gains as treasury yields ease and earnings remain supportive.
Share this:

US futures
Dow futures +0.7% at 35708
S&P futures +0.96% at 4464
Nasdaq futures +1.38% at 14945
In Europe
FTSE +0.85% at 7622
Dax +1.6% at 15494
Euro Stoxx +1.7% at 4200
Stocks extend rally
US stocks pointing to a strong open after a solid close in the previous session. All three indices closed on positive ground yesterday after a string of upbeat earnings helped distract from Thursday’s inflation data.
According to FactSet so far 60 % of companies on the S&P have reported earnings and of those 77% have beaten Wall Street estimates. Apart from a few anomalies, (Meta, Netflix the most obvious) earnings have broadly been supportive for the market. Corporate America is broadly beating forecasts, but by smaller amounts than in previous years, also 2022 estimates are not being raise as much as in 2021. However, neither of these points are surprising, we know that growth must normalize after two unique years.
Earnings will continue think and fast today with CVS Health, Disney, MGM Resorts and Uber all due to release numbers.
Inflation is the other hot topic for the markets as investors await tomorrow’s CPI data. Expectations are for inflation to continue rising to 7.3% YoY. The data is likely to drive Fed rate hike expectations – a 25 or 50 basis point move in March?
In other corporate news:
Tesla will also be in focus after recalling 27,000 cars in the US due to a software issue, which could result in problems defrosting the windshield.
Where next for the Dow Jones?
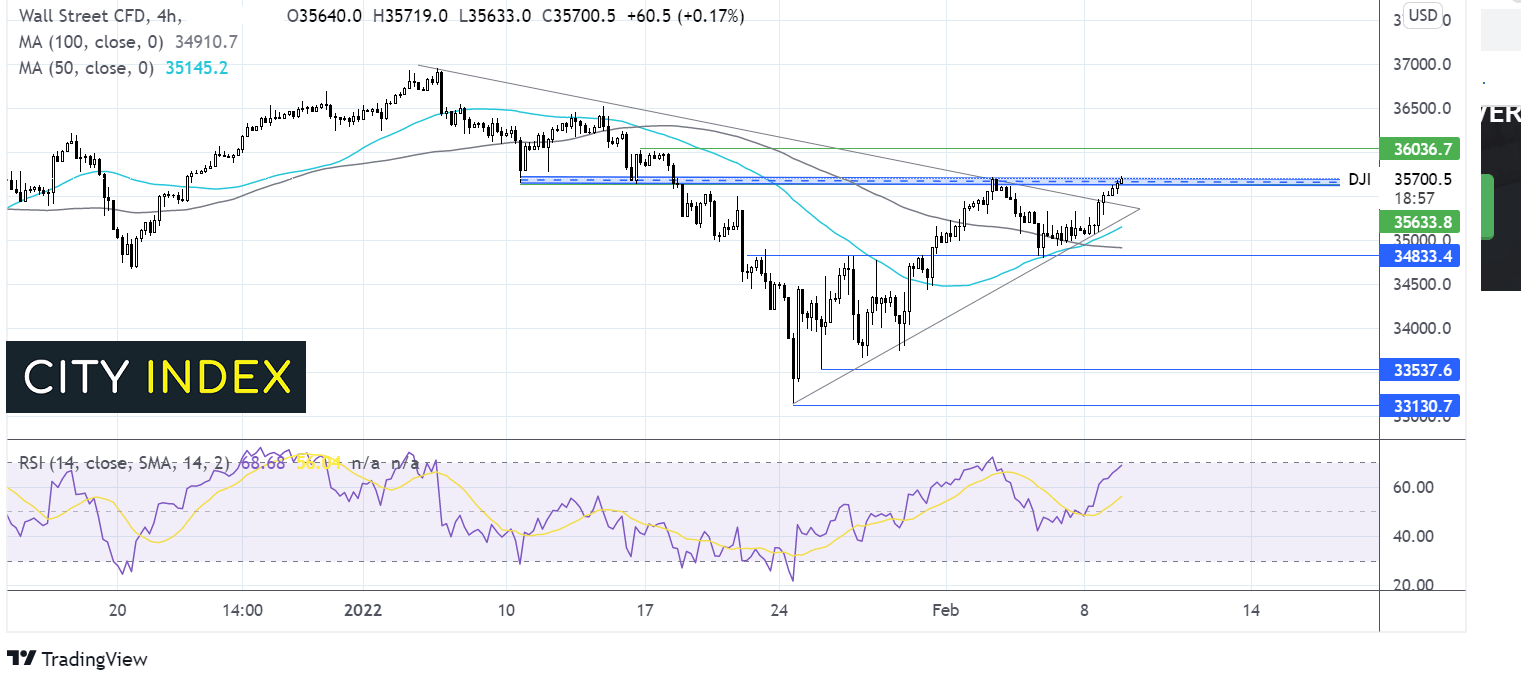
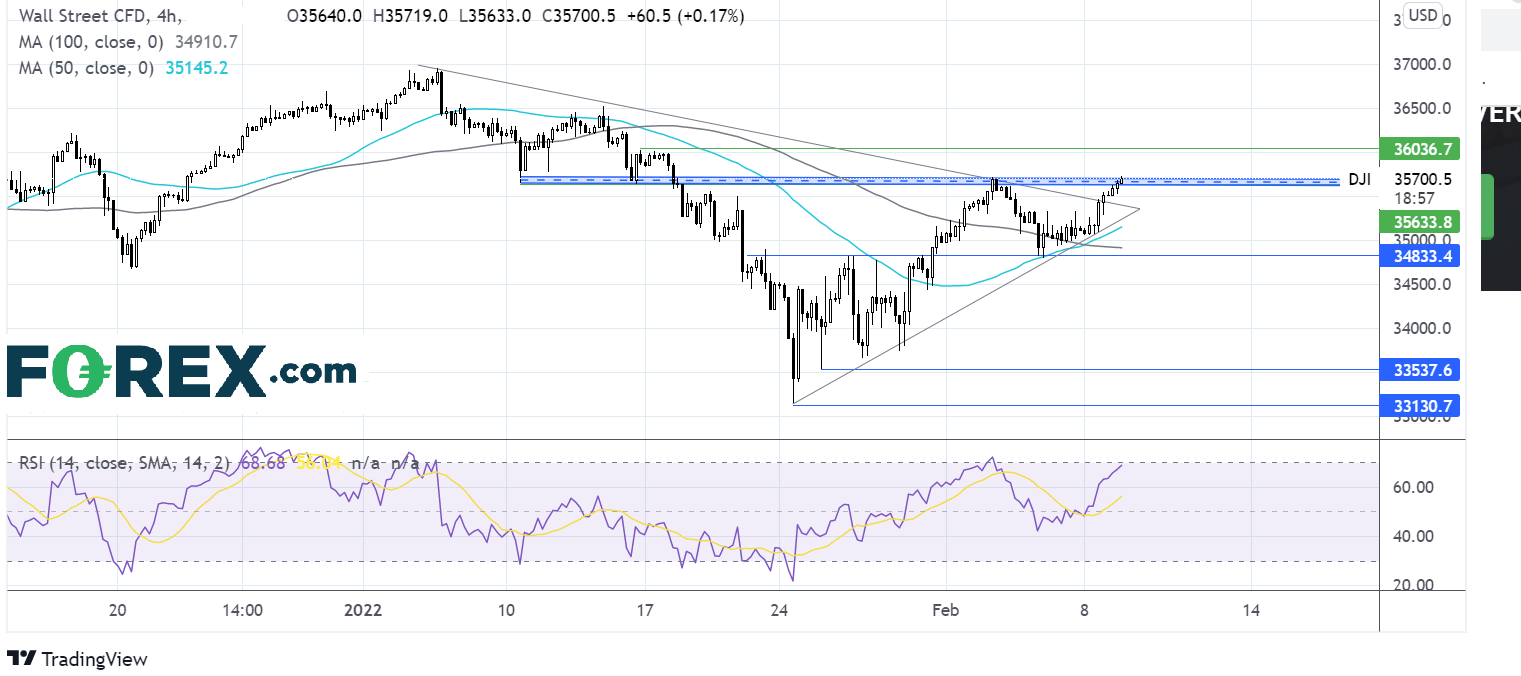
The Dow is extending its gains from the year to date low of 33145, breaking out from a symmetrical triangle formation. The 50 sma crossing above the 100 sma on the 4 hour chart, in addition to the bullish RSI, are also keeping buyers optimistic of further upside. Buyers will want to see a move above the current level of 35700, resistance from 2 Feb, but also a level of support in mid-January. A move above here could open the door to 36,000 round number and January 17 high. Failure to retake 35700 and a fall below 35380 falling trendline exposes the 50 sma at 35180. A move below 34800 could see the sellers gain momentum.
FX markets USD falls, GBP rises for 3rd day
The USD is falling, paring gains from the previous session as treasury yields ease lower. All eyes are on tomorrow’s inflation data which could cement expectations of a more hawkish Fed.
GBP/USD is rising for a third straight day despite there being no high impacting UK data for investors to sink their teeth into. Prime Minister Boris Johnson’s mini cabinet re-shuffle looks as if it could ease the Brexit deadlocks which could bee supporting the pound today. BoE’s Pill to speak.
GBP/USD +0.22% at 1.3574
EUR/USD +0.14% at 1.1433
Oil eases from 7 year high, US – Iran talk progress eyed
Oil prices are edging lower for a third straight session as they continue to ease back from the 7-year high reached last week. Whilst tight supply and concerns over Russia – Ukraine tensions boosted oil prices last week, prices have since ease back as US – Iran nuclear talks make progress.
A deal between the two sides could see Iranian oil sanctions removed and considerably more supply in the market.
Concerns over more supply mean that oil prices have fallen despite API inventory data showing a 2-million-barrel draw in stock piles.
EIA data is due later
WTI crude trades -0.3% at $88.10
Brent trades -0.3% at $90.37
Looking ahead
15:30 EIA inventories
17:00 Fed Mester speech
17:00 BoC Macklem speech
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.