



US open: Stocks rise and USD drops as core PCE cools
US stocks are rising, building on yesterday's strong gains after core PCE eased to 5% YoY, down from 5.2%.
Share this:

US futures
Dow futures +0.08% at 34590
S&P futures +0.23% at 4088
Nasdaq futures +0.23% at 12053
In Europe
FTSE -0.14% at 7579
Dax +0.7% at 14510
Personal spending rises, jobless claims fall
US stocks are set for a stronger start adding to impressive gains from the previous session. A less hawkish stance from Federal Reserve Chair Powell, combined with cooling core PCE has lifted stocks to significant levels.
The Dow Jones trades in a bull market, up 20% from its September low, while the S&P500 has pushed over the 200 sma moving average.
Yesterday Fed Chair Powell signaled that the US central bank would raise interest rates at a slower pace moving forwards, cementing expectations for a 50-basis point hike in December. Powell also said that the terminal rate would likely be above where it was forecast in September. The market didn’t pay much attention to this warning, it seems, as the Nasdaq soared 4%.
Today’s data is enough to keep the market happy that inflation is moving in the right direction. However, it is a small decline, highlighting that this is likely to be a long journey. Personal spending was also solid at 0.8%
Separately jobless claims were slightly lower than expected at 225k, down from 240k in the previous week.
Overall, the data is upbeat, showing that the economy is still holding up while inflation is cooling. If it continues like this, then a soft landing for the US economy could be likely.
US ISM manufacturing data is due shortly.
Elsewhere China is easing some lockdown restrictions, which is adding to the supportive mood towards equities.
Corporate news:
Kroger rises 3.2% pre-market after the supermarket chain raised the annual same-store sales forecast thanks to a steady demand for groceries and essentials.
Salesforce trades 7.1% lower pre-market after announcing that the co-chief executive would step down in January, raising uncertainty over future direction.
Where next for the Dow Jones?
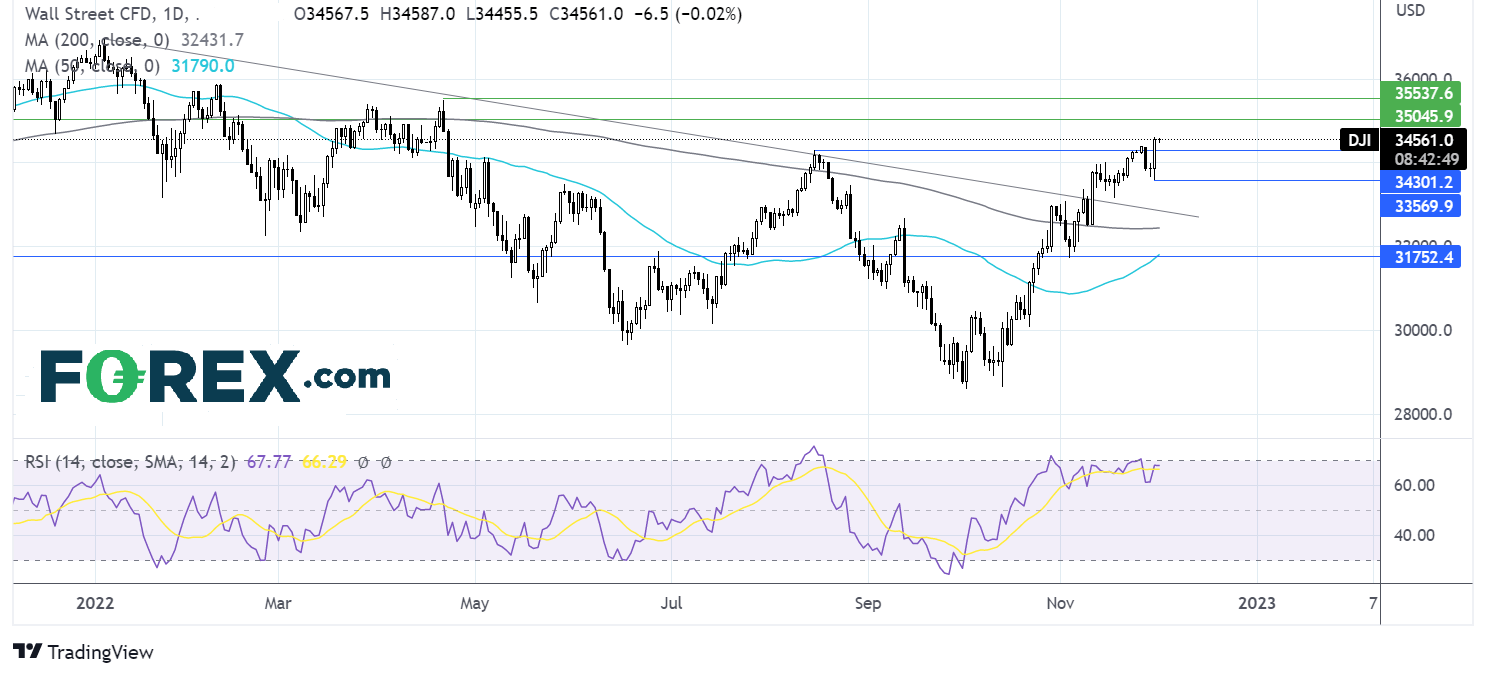
The Dow Jones rallied over 20% from its September low, rising above the 200 sma and resistance at 34300 the August high. The RSI supports further upside while it remains out of overbought territory. Buyers will be looking ahead to 35000 round number to extend gains to 35500 the April peak. On the downside, immediate support can be seen at 34300, with a break below here opening the door to 33570 the weekly low and 33000 round number.
FX markets – USD falls, EUR rises.
The USD is falling as inflation cools, supporting the Fed’s less hawkish stance.
EURUSD is rising, capitalizing on the weaker USD, despite disappointing data. German retail sales fell by more than forecast -2.8% MoM as surging energy costs reduce disposable income. Eurozone manufacturing PMI was also revised lower to 47.1.
GBP/USD is rallying hard across the board as it continues to stage an impressive recovery from the 1.0340 all time low in September. UK manufacturing OMI was upwardly revised to 46.5 in November. The pound trades at a 16-week high, boosted by Powell’s remarks, which appear to be driving flows out of the USD towards GBP. The pound his rising versus all its crosses
GBP/USD +1% at 1.2190
EUR/USD +0.39% at 1.0444
Oil rallies 7% so far this week
Oil prices are rising for a fourth straight day, trading up 7% so far this week. The latest leg higher comes as China eases lockdown restrictions in several major cities, raising the demand outlook, Fed Chair Powell talks down the US dollar, and as investors look ahead to the OPEC meeting this weekend.
There are some suggestions that as the OPEC meeting is now taking place virtually that another production cut is unlikely. “Sources “ also say that no cuts are expected. However, a further cut can’t be completely ruled out. OPEC+ has surprised the market in the past, and some of this recent rally could be explained by expectations of further cuts.
The prospect of a lower oil price cap is also supporting the market. The EU is slowly progressing towards a deal which is due to begin on Monday.
WTI crude trades +1.4% at $81.68
Brent trades at +1.3% at $88.05
Looking ahead
14:00 ISM Manufacturing PMI
15:45 ECB Lane speech
US futures
Dow futures +0.08% at 34590
S&P futures +0.23% at 4088
Nasdaq futures +0.23% at 12053
In Europe
FTSE -0.14% at 7579
Dax +0.7% at 14510
Learn more about trading indices
Personal spending rises, jobless claims fall
US stocks are set for a stronger start adding to impressive gains from the previous session. A less hawkish stance from Federal Reserve Chair Powell, combined with cooling core PCE has lifted stocks to significant levels.
The Dow Jones trades in a bull market, up 20% from its September low, while the S&P500 has pushed over the 200 sma moving average.
Yesterday Fed Chair Powell signaled that the US central bank would raise interest rates at a slower pace moving forwards, cementing expectations for a 50-basis point hike in December. Powell also said that the terminal rate would likely be above where it was forecast in September. The market didn’t pay much attention to this warning, it seems, as the Nasdaq soared 4%.
Today’s data is enough to keep the market happy that inflation is moving in the right direction. However, it is a small decline, highlighting that this is likely to be a long journey. Personal spending was also solid at 0.8%
Separately jobless claims were slightly lower than expected at 225k, down from 240k in the previous week.
Overall, the data is upbeat, showing that the economy is still holding up while inflation is cooling. If it continues like this, then a soft landing for the US economy could be likely.
US ISM manufacturing data is due shortly.
Elsewhere China is easing some lockdown restrictions, which is adding to the supportive mood towards equities.
Corporate news:
Kroger rises 3.2% pre-market after the supermarket chain raised the annual same-store sales forecast thanks to a steady demand for groceries and essentials.
Salesforce trades 7.1% lower pre-market after announcing that the co-chief executive would step down in January, raising uncertainty over future direction.
Where next for the Dow Jones?
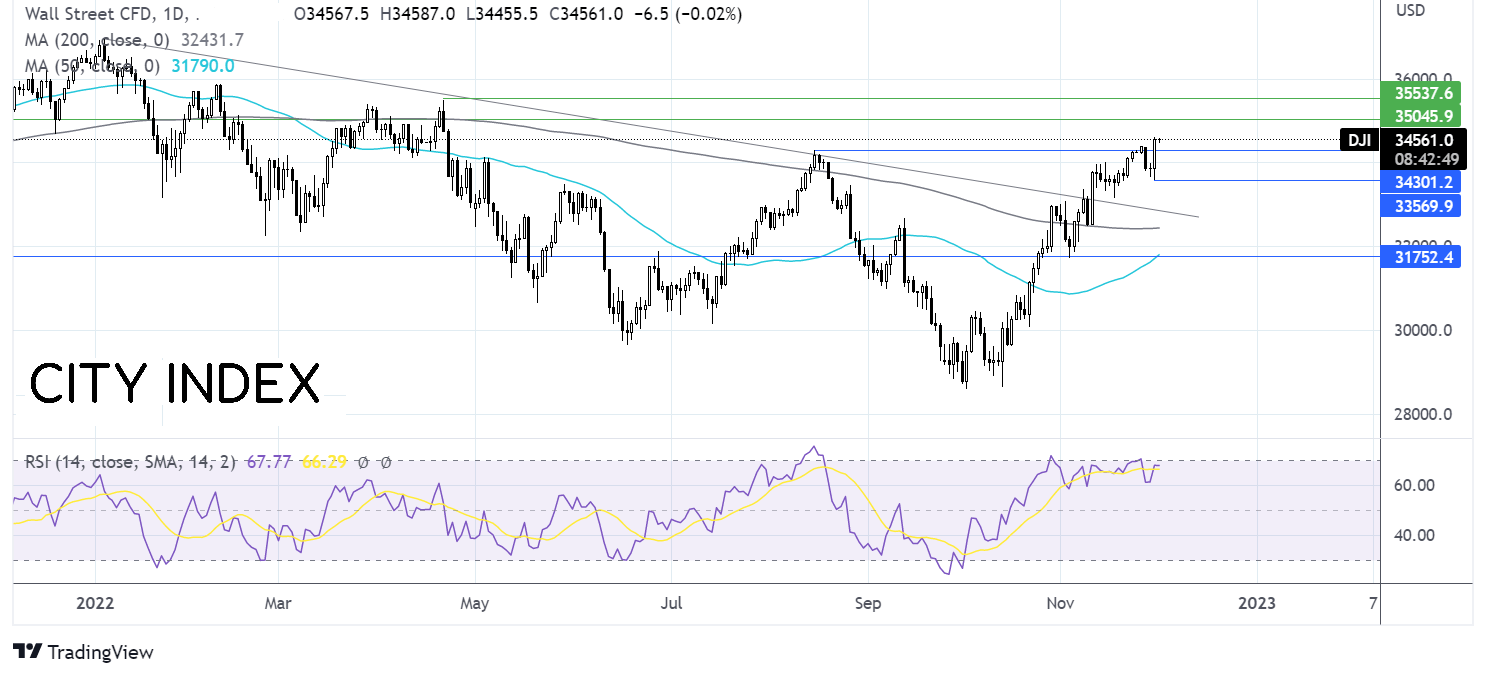
The Dow Jones rallied over 20% from its September low, rising above the 200 sma and resistance at 34300 the August high. The RSI supports further upside while it remains out of overbought territory. Buyers will be looking ahead to 35000 round number to extend gains to 35500 the April peak. On the downside, immediate support can be seen at 34300, with a break below here opening the door to 33570 the weekly low and 33000 round number.
FX markets – USD falls, EUR rises.
The USD is falling as inflation cools, supporting the Fed’s less hawkish stance.
EURUSD is rising, capitalizing on the weaker USD, despite disappointing data. German retail sales fell by more than forecast -2.8% MoM as surging energy costs reduce disposable income. Eurozone manufacturing PMI was also revised lower to 47.1.
GBP/USD is rallying hard across the board as it continues to stage an impressive recovery from the 1.0340 all time low in September. UK manufacturing OMI was upwardly revised to 46.5 in November. The pound trades at a 16-week high, boosted by Powell’s remarks, which appear to be driving flows out of the USD towards GBP. The pound his rising versus all its crosses
GBP/USD +1% at 1.2190
EUR/USD +0.39% at 1.0444
Oil rallies 7% so far this week
Oil prices are rising for a fourth straight day, trading up 7% so far this week. The latest leg higher comes as China eases lockdown restrictions in several major cities, raising the demand outlook, Fed Chair Powell talks down the US dollar, and as investors look ahead to the OPEC meeting this weekend.
There are some suggestions that as the OPEC meeting is now taking place virtually that another production cut is unlikely. “Sources “ also say that no cuts are expected. However, a further cut can’t be completely ruled out. OPEC+ has surprised the market in the past, and some of this recent rally could be explained by expectations of further cuts.
The prospect of a lower oil price cap is also supporting the market. The EU is slowly progressing towards a deal which is due to begin on Monday.
WTI crude trades +1.4% at $81.68
Brent trades at +1.3% at $88.05
Learn more about trading oil here.
Looking ahead
14:00 ISM Manufacturing PMI
15:45 ECB Lane speech
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.


EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.