



US open: Stocks rise as corporate earnings heat up
US stocks open higher ahead of a busy week for earnings and as aggressive Fed bets ease.
Share this:

US futures
Dow futures +0.85% at 31312
S&P futures +0.76% at 3891
Nasdaq futures +0.9% at 11613
In Europe
FTSE +0.7% at 7230
Dax +0.8% at 12970
Euro Stoxx +1.1% at 3512
Fed bets ease, earnings in focus
US stocks are heading for a stronger start, extending gain from the end of last week as investors look ahead to a busy week for earnings.
US indices lost ground across the previous week after hot CPI data lifted expectations of a more hawkish Fed. The market started pricing in 100 basis point rate hike in July.
Towards the end of the week, even hawkish Fed speakers said that they supported a 75-basis point rate hike. The softening of those aggressive Fed bets has lifted the market mood, boosting stocks and pulling the USD lower.
Despite the move higher, recession fears remain high, and this is more likely a bear market rally rather than a deeper fundamental change in the direction of the market.
Earnings season is ramping up with mixed numbers from the major banks and attention than moving towards tech for clues as to whether the worst is past.
In corporate news:
Bank of America is falling pre-market after reporting a fall in Q2 profits. The bank saw a fall in investment banking revenue as underwriting activity slumped.
Goldman Sachs rises pre-market after strong bond market trading results helped lift the stock higher, even as profits halved.
Where next for the S&P500?
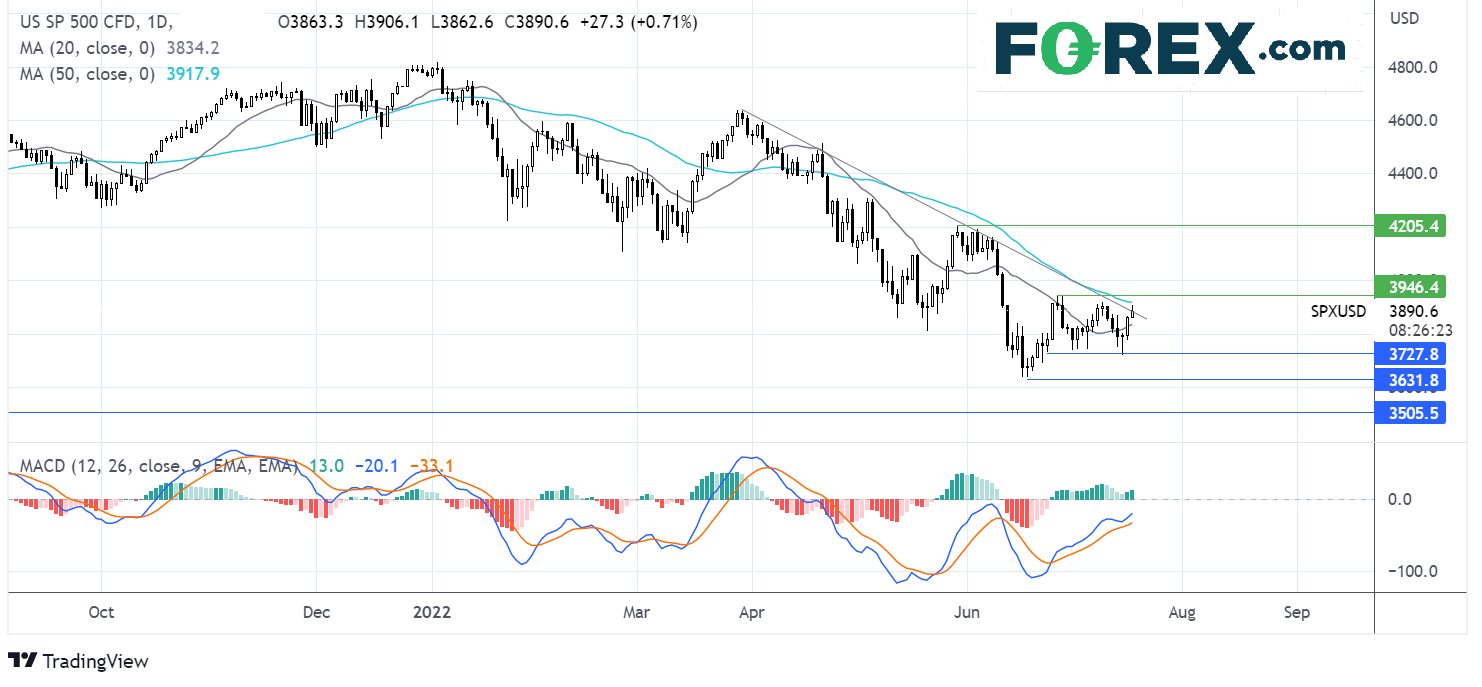
The S&P500 rebounded lower from support at 3720, rising above the 20 sma, which combined with the bullish MACD, keeps buyers hopeful of further upside. Buyers need to rise above the 50 sma at 3920 to test resistance at 3940 and create a higher. Failure to retake the 50 sma could see the index fall back towards support at 3720, with a break below here opening the door to 3635, the 2022 low.
FX markets – USD falls, GBP climbs
USD is edging lower as the markets reassess the likelihood of a 100 basis point rate hike and aggressive Fed bets ease. The Fed is now in a blackout period ahead of the FOMC at the end of the month.
EURUSD is rising back above 1.0100 as attention turns to eurozone CPI data and the ECB interest rate meeting later in the week. The ECB is expected to hike rates for the first time in a decade.
GBP/USD is rising towards 1.20, capitalizing on the weaker USD. This week is a busy week for UK macro data with unemployment figures, inflation, and retail sales data due across the week.
GBP/USD +0.76% at 1.1930
EUR/USD +0.3% at 1.0120
Oil rises but down across the week
Oil prices are rising on Monday, boosted by the softer USD and tighter supply. Oil prices are rebounding after falling over 6% last week as recession fears and rising COVID cases in China hurt the demand outlook.
On the supply side, President Biden returned from a risky political trip to Saudi Arabia without any firm agreement from the oil-producing nation to raise output. Biden is keen for the guld nations to raise output to help lower oil prices and inflation.
Attention is also on the repairs of Nord Stream 1 and whether Russia will switch it back online in a few days when the repairs are over. Failure to do so could send oil prices higher by the end of the week.
WTI crude trades +2% at $96.70
Brent trades +2% at $100.5
Looking ahead
N/A
US futures
Dow futures +0.85% at 31312
S&P futures +0.76% at 3891
Nasdaq futures +0.9% at 11613
In Europe
FTSE +0.7% at 7230
Dax +0.8% at 12970
Euro Stoxx +1.1% at 3512
Learn more about trading indices
Fed bets ease, earnings in focus
US stocks are heading for a stronger start, extending gain from the end of last week as investors look ahead to a busy week for earnings.
US indices lost ground across the previous week after hot CPI data lifted expectations of a more hawkish Fed. The market started pricing in 100 basis point rate hike in July.
Towards the end of the week, even hawkish Fed speakers said that they supported a 75-basis point rate hike. The softening of those aggressive Fed bets has lifted the market mood, boosting stocks and pulling the USD lower.
Despite the move higher, recession fears remain high, and this is more likely a bear market rally rather than a deeper fundamental change in the direction of the market.
Earnings season is ramping up with mixed numbers from the major banks and attention than moving towards tech for clues as to whether the worst is past.
In corporate news:
Bank of America is falling pre-market after reporting a fall in Q2 profits. The bank saw a fall in investment banking revenue as underwriting activity slumped.
Goldman Sachs rises pre-market after strong bond market trading results helped lift the stock higher, even as profits halved.
Where next for the S&P500?
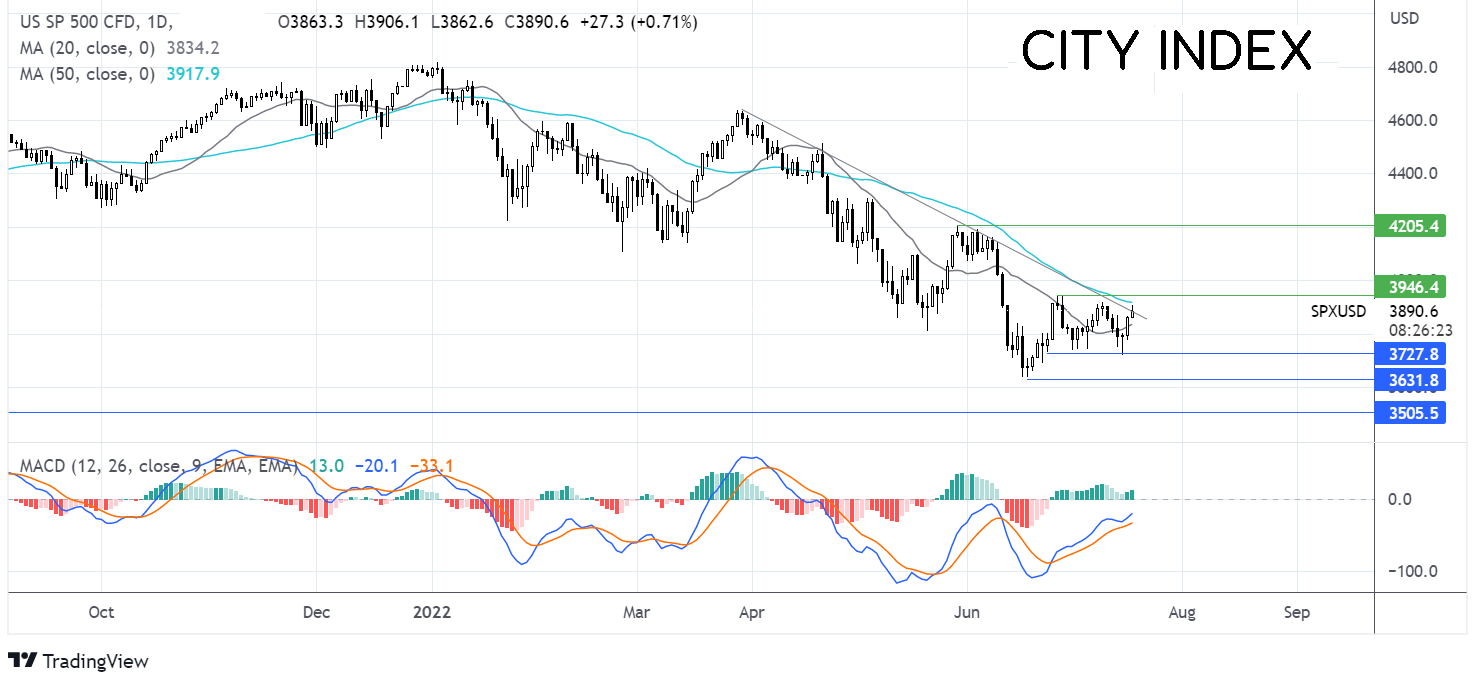
The S&P500 rebounded lower from support at 3720, rising above the 20 sma, which combined with the bullish MACD, keeps buyers hopeful of further upside. Buyers need to rise above the 50 sma at 3920 to test resistance at 3940 and create a higher. Failure to retake the 50 sma could see the index fall back towards support at 3720, with a break below here opening the door to 3635, the 2022 low.
FX markets – USD falls, GBP climbs
USD is edging lower as the markets reassess the likelihood of a 100 basis point rate hike and aggressive Fed bets ease. The Fed is now in a blackout period ahead of the FOMC at the end of the month.
EURUSD is rising back above 1.0100 as attention turns to eurozone CPI data and the ECB interest rate meeting later in the week. The ECB is expected to hike rates for the first time in a decade.
GBP/USD is rising towards 1.20, capitalizing on the weaker USD. This week is a busy week for UK macro data with unemployment figures, inflation, and retail sales data due across the week.
GBP/USD +0.76% at 1.1930
EUR/USD +0.3% at 1.0120
Oil rises but down across the week
Oil prices are rising on Monday, boosted by the softer USD and tighter supply. Oil prices are rebounding after falling over 6% last week as recession fears and rising COVID cases in China hurt the demand outlook.
On the supply side, President Biden returned from a risky political trip to Saudi Arabia without any firm agreement from the oil-producing nation to raise output. Biden is keen for the guld nations to raise output to help lower oil prices and inflation.
Attention is also on the repairs of Nord Stream 1 and whether Russia will switch it back online in a few days when the repairs are over. Failure to do so could send oil prices higher by the end of the week.
WTI crude trades +2% at $96.70
Brent trades +2% at $100.5
Learn more about trading oil here.
Looking ahead
N/A
Related tags:

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

ASX 200 Outlook: Potential to Bounce Sits on a Knife Edge
ASX 200 bounce prospects remain on a knife edge as oversold technicals clash with weak financials, commodity pressures and global risk aversion.


US dollar rally loses yield support as Nvidia looms
US yields are retreating, but the dollar isn't following. With risk aversion potentially keeping it supported, Nvidia's results could determine whether emerging reversal signals in AUD/USD and EUR/USD develop further.

GBP/USD, GBP/JPY, GBP/AUD: Sterling Eyes UK Inflation Catalyst
Sterling faces a pivotal UK inflation test as traders weigh BoE tightening, Fed minutes and Australian employment data across GBP/USD, GBP/JPY and GBP/AUD.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.