



US open: Stocks rise, jobless claims little changed, Powell next
Stocks edge higher as investors digest the latest jobless claims and look to Fed Powell who testifies again.
Share this:

US futures
Dow futures +0.3% at 30598
S&P futures +0.5% at 3776
Nasdaq futures +0.7% at 11606
In Europe
FTSE -0.5% at 7057
Dax -1.3% at 13000
Euro Stoxx -0.5% at 3427
Jobless claims around a 5-month high
US stocks are set to rise after moderate losses in the previous session, as investors digest the last jobless claims and look ahead to another testimony from Powell.
Yesterday in his testimony before Congress Powell came across as slightly less hawkish than in the previous week and also explicitly acknowledged that a recession was possible. In response Treasury yields fell, pulling the USD lower whilst lifting stocks from the session lows.
The markets have been fretting that aggressive Fed hikes could tip the economy into recession. The Fed is expected to raise rates by 75 basis points in July and 50 basis points in September.
On the data front jobless claims came in at 229k, and last weeks were upwardly revised to 231k. The numbers were little changed and sit near a five-month high, which could be indicating that tightness in the labour market is starting to ease.
The jobs market remains strong but several firms are starting to announce redundancies in recent weeks again pointing to an easing in a historically tight market.
.
Where next for the Dow Jones?
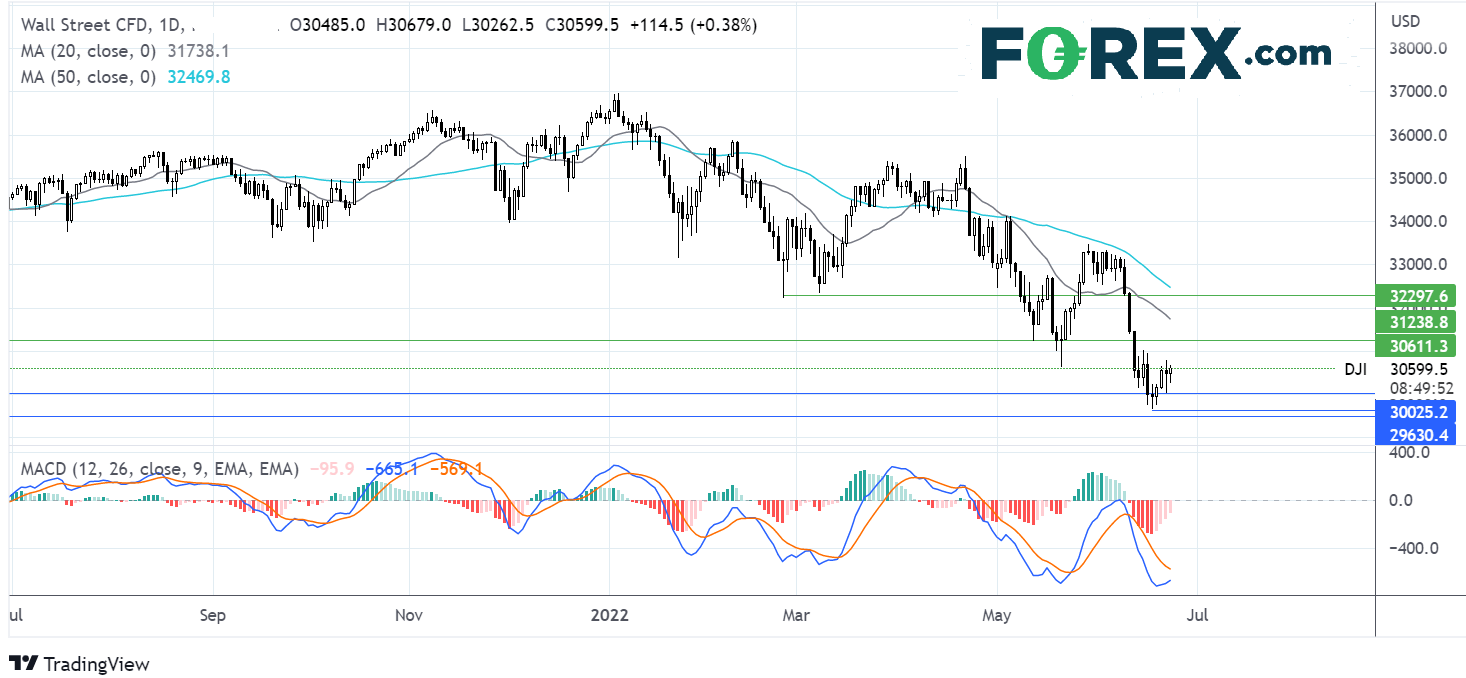
The Dow Jones has been forming a series of lower lows, running into support at 29650 last week’s low, before clawing higher. The price is testing resistance at 30600 the May 20 low, a move above here and the receding bearish bias on the MACD keep buyers hopeful of further upside. Resistance can be seen at 31000 the June 15 high and round number. A break above exposes the 20 sma. On the flip slide, the sellers could look for a break below support at 30050 to bring 29650 back into play and to create a lower low.
FX markets – USD rises, GBP falls
USD is rising, recouping losses from the previous session as it awaits PMI data and another appearance from the Fed Chair. Whilst recession concerns pulled the USD lower yesterday, today the greenback is capitalizing on the weaker PMI data in Europe, even as stocks move higher.
EURUSD is falling after dismal business activity data across the board. The composite PMI showed that the economy is losing momentum. The sharp drop in the composite PMI to 51.9 from 54.8 indicates that the economy has already started cooling rapidly, even before the ECB has started hiking.
GBP/USD is falling on the back of USD strength and despite UK services PMI coming in ahead of forecasts and in line with May’s reading of 53.4 meanwhile the composite reading held steady at 53.1. Delving deeper into the data, the numbers show that rising inflation is hitting new orders and business confidence slips to a level that is associated with a recession. The report will be a concern for the BoE as firms pay higher wages and pass on the higher costs to customers heading towards spiraling inflation.
GBP/USD -0.5% at 1.2267
EUR/USD -0.47% at 1.0557
Oil extends losses
Oil prices fell sharply yesterday and are edging lower again today, although they have picked up off the daily low.
Fears of a recession and what that will mean for oil demand is weighing on the price of oil, pulling WTI to a low of $102.32. However, the price has picked up from the lows helped by improving demand for risk assets across the financial markets. But gains are likely to be capped, it seems unlikely that oil prices will rise back to the levels seen earlier in the month while recession fears and demand destruction concerns linger.
Separately President Biden has requested a 3-month suspension on the federal gasoline tax, in order to help eases prices at the pump.
WTI crude trades +0.8% at $109.56
Brent trades +0.8% at $113.22
Looking ahead
14:45 US Composite PMI
15:00 Fed Chair Powell testifies
21:30 banks stress test
US futures
Dow futures +0.3% at 30598
S&P futures +0.5% at 3776
Nasdaq futures +0.7% at 11606
In Europe
FTSE -0.5% at 7057
Dax -1.3% at 13000
Euro Stoxx -0.5% at 3427
Learn more about trading indices
Jobless claims around a 5-month high
US stocks are set to rise after moderate losses in the previous session, as investors digest the last jobless claims and look ahead to another testimony from Powell.
Yesterday in his testimony before Congress Powell came across as slightly less hawkish than in the previous week and also explicitly acknowledged that a recession was possible. In response Treasury yields fell, pulling the USD lower whilst lifting stocks from the session lows.
The markets have been fretting that aggressive Fed hikes could tip the economy into recession. The Fed is expected to raise rates by 75 basis points in July and 50 basis points in September.
On the data front jobless claims came in at 229k, and last weeks were upwardly revised to 231k. The numbers were little changed and sit near a five-month high, which could be indicating that tightness in the labour market is starting to ease.
The jobs market remains strong but several firms are starting to announce redundancies in recent weeks again pointing to an easing in a historically tight market.
In corporate news:
read here for the latest stock news
Where next for the dow jones?
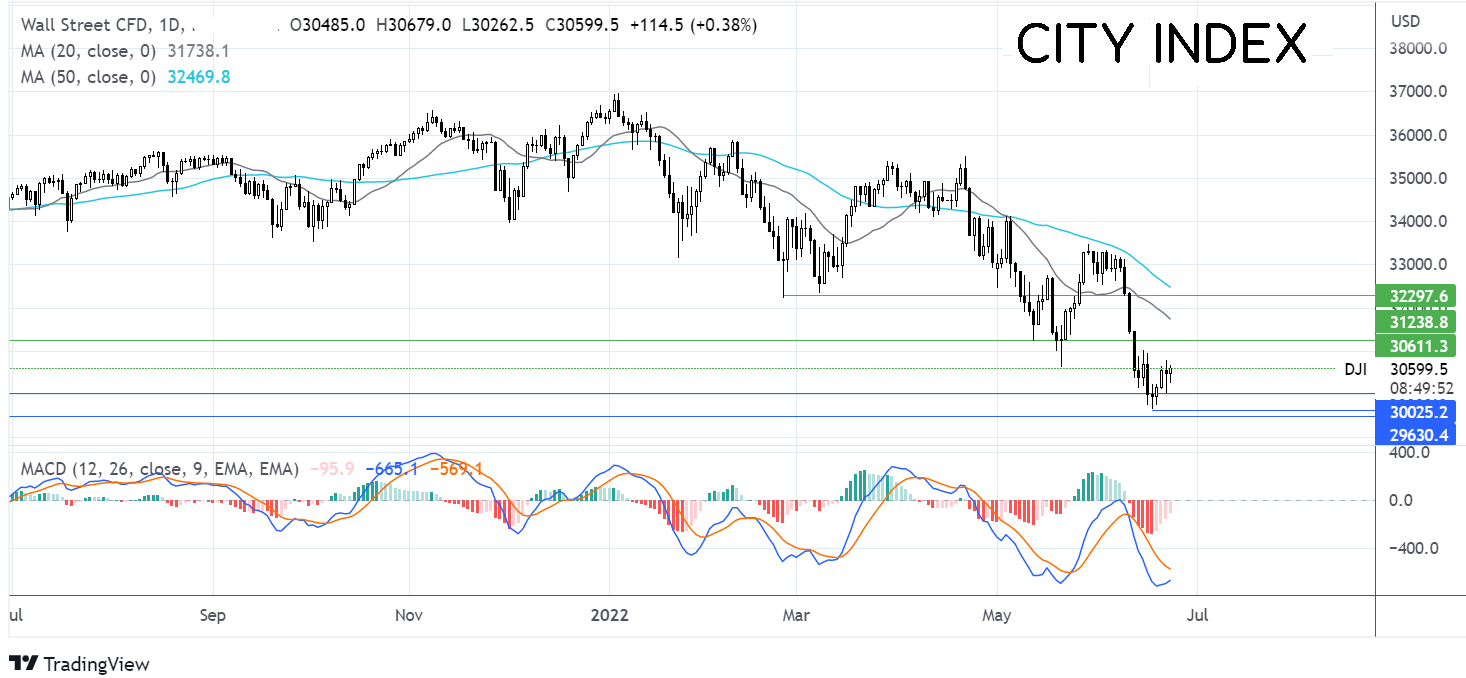
The Dow Jones has been forming a series of lower lows, running into support at 29650 last week’s low, before clawing higher. The price is testing resistance at 30600 the May 20 low, a move above here and the receding bearish bias on the MACD keep buyers hopeful of further upside. Resistance can be seen at 31000 the June 15 high and round number. A break above exposes the 20 sma. On the flip slide, the sellers could look for a break below support at 30050 to bring 29650 back into play and to create a lower low.
FX markets – USD rises, GBP falls
USD is rising, recouping losses from the previous session as it awaits PMI data and another appearance from the Fed Chair. Whilst recession concerns pulled the USD lower yesterday, today the greenback is capitalizing on the weaker PMI data in Europe, even as stocks move higher.
EURUSD is falling after dismal business activity data across the board. The composite PMI showed that the economy is losing momentum. The sharp drop in the composite PMI to 51.9 from 54.8 indicates that the economy has already started cooling rapidly, even before the ECB has started hiking.
GBP/USD is falling on the back of USD strength and despite UK services PMI coming in ahead of forecasts and in line with May’s reading of 53.4 meanwhile the composite reading held steady at 53.1. Delving deeper into the data, the numbers show that rising inflation is hitting new orders and business confidence slips to a level that is associated with a recession. The report will be a concern for the BoE as firms pay higher wages and pass on the higher costs to customers heading towards spiraling inflation.
GBP/USD -0.58% at 1.2267
EUR/USD -0.47% at 1.0557
Oil extends losses
Oil prices fell sharply yesterday and are edging lower again today, although they have picked up off the daily low.
Fears of a recession and what that will mean for oil demand is weighing on the price of oil, pulling WTI to a low of $102.32. However, the price has picked up from the lows helped by improving demand for risk assets across the financial markets. But gains are likely to be capped, it seems unlikely that oil prices will rise back to the levels seen earlier in the month while recession fears and demand destruction concerns linger.
Separately President Biden has requested a 3-month suspension on the federal gasoline tax, in order to help eases prices at the pump.
WTI crude trades +0.8% at $109.56
Brent trades +0.8% at $113.22
Learn more about trading oil here.
Looking ahead
14:45 US Composite PMI
15:00 Fed Chair Powell testifies
21:30 banks stress test
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Outlook: Potential to Bounce Sits on a Knife Edge
ASX 200 bounce prospects remain on a knife edge as oversold technicals clash with weak financials, commodity pressures and global risk aversion.

US dollar rally loses yield support as Nvidia looms
US yields are retreating, but the dollar isn't following. With risk aversion potentially keeping it supported, Nvidia's results could determine whether emerging reversal signals in AUD/USD and EUR/USD develop further.


GBP/USD, GBP/JPY, GBP/AUD: Sterling Eyes UK Inflation Catalyst
Sterling faces a pivotal UK inflation test as traders weigh BoE tightening, Fed minutes and Australian employment data across GBP/USD, GBP/JPY and GBP/AUD.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.