



US open: Stocks tumble on global growth concerns, China's lockdown
US stocks are set to extend the sell off as fears of tighter monetary policy & the ongoing China lockdown hit sentiment.
Share this:

US futures
Dow futures -1.1 % at 32530
S&P futures -1.4% at 4065
Nasdaq futures -1.86% at 12468
In Europe
FTSE -1.9% at 7265
Dax -1.5% at 13510
Euro Stoxx -1.64% at 3570
Stocks drop for a 3rd straight day
US stocks are set to open sharply lower amid concerns over higher interest rates and tighter lockdown restrictions in China. Fears of slowing global growth are pulling stocks lower for a third straight session.
Last week stocks reversed sharply on the Thursday following the Fed meeting as the market grew nervous over how quickly the Fed will need to raise interest rates in order to take 40-year inflation.
US treasury yields surged on Friday and are continuing to run higher today. The RBA, BoE, and Fed all hiked last week, with the BoE even warned of a recession.
The risk of recession is lower in the US, but more tightening is expected and is expected to be front-loaded.
In addition to central bank woes, a tighter lockdown in Shanghai as authorities press ahead with the zero-COVID policy adds to fears over the outlook for global growth. Chinese exports grew at the slowest pace in almost two years in April at 3.9%.
There is no high impacting data; sentiment is likely to continue driving the markets.
In corporate news:
Rivian tumbles 18% pre-marke5t on news that Ford is selling 8 million shares and that JP Morgan is selling a further 12 million for an unnamed investor. The EV maker’s insider lock-in period ends.
Uber also trades lower pre-market on reports that the ride-hailing app will scale back costs and hiring.
Where next for the Nasdaq?
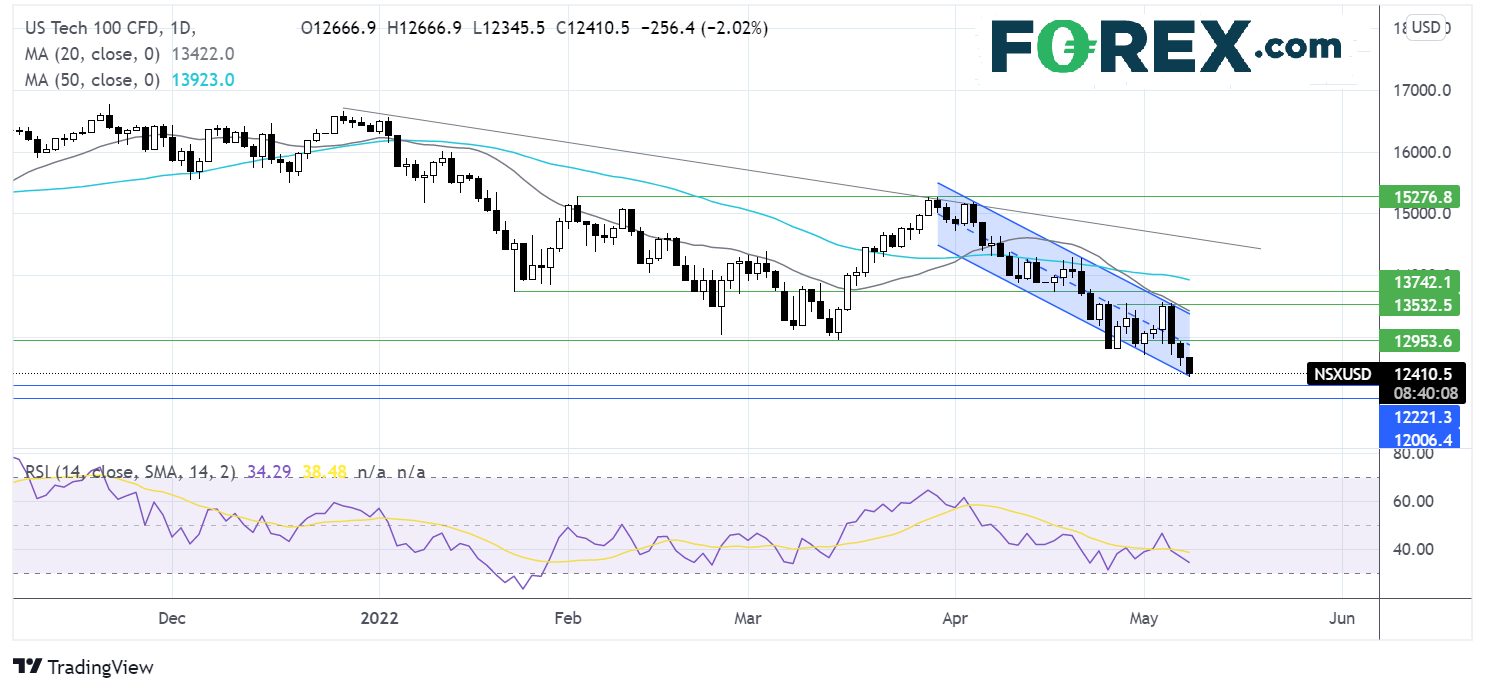
The Nasdaq continued to trade in the falling channel it has traded in since the start of April. The price trades at the lower end of the channel, which, combined with the bearish RSI, suggests that there could be more downside to come. Immediate support can be seen at 12345, today’s low, and the falling trendline support. A break below here could open the door to 12210, the March ’21 low and 12000 round number. Buyers will be looking for a move over 13000, the March low and midpoint of the falling channel, to head towards 13530, last week’s high.
FX markets USD steadies, and AUD drops.
USD is rising a few pips higher, adding to solid gains across last week on hawkish Fed bets and safe-haven flows. The Fed hiked rates by 50bp last week and is expected to continue acting aggressively to rein in 40-year high inflation; later in the week, US CPI data will be the main focus this week. Fed speakers are expected to continue the hawkish chorus. US dollar index rose to a 20-year high over 104.00 but has since pared some gains.
GBP/USD fell to 1.2250 but has managed to turn positive, heading towards the US open. The former BoE chief economist Andy Haldane warned that inflation could peak higher than 10%.
EUR/USD is rebounding after a weaker start today. Eurozone consumer confidence dropped to -22.6, below the 21.6 forecast, and down from -18 in March.
AUD/USD is the worst performer today, weighed down by the China woes and risk off trade. AUDUSD fell below 0.70 but has managed to recapture the psychological level.
GBP/USD +0.23% at 1.2370
EUR/USD +0.03% at 1.0540
Oil falls on demand fears
Oil prices are falling as China’s demand fears and the stronger USD overshadow Russian supply concerns.
Beijing is showing no signs of easing up on its strict zero-COVID policy, and tighter lockdown restrictions in Shanghai and Beijing are raising concerns over the demand picture. Concerns over the broader state of global growth add to the weaker demand picture. A slowdown in global growth means lower global oil demand.
These fears overshadow news that the G7 unveiled more sanctions on Russia over the weekend, including an embargo on Russian oil. This comes after the EU proposed a phased-in ban on Russian crude last week, the vote on which is expected to take place this week. All members must agree to the proposal.
The USD trading at a 20-year high means that oil is more expensive to buyers with foreign currencies, which hurts demand.
WTI crude trades -3.2% at $105.42
Brent trades -3.1% at $108.61
Looking ahead
N/A
US futures
Dow futures -1.1 % at 32530
S&P futures -1.4% at 4065
Nasdaq futures -1.86% at 12468
In Europe
FTSE -1.9% at 7265
Dax -1.5% at 13510
Euro Stoxx -1.64% at 3570
Learn more about trading indices
Stocks drop for a 3rd straight day
US stocks are set to open sharply lower amid concerns over higher interest rates and tighter lockdown restrictions in China. Fears of slowing global growth are pulling stocks lower for a third straight session.
Last week stocks reversed sharply on the Thursday following the Fed meeting as the market grew nervous over how quickly the Fed will need to raise interest rates in order to take 40-year inflation.
US treasury yields surged on Friday and are continuing to run higher today. The RBA, BoE, and Fed all hiked last week, with the BoE even warned of a recession.
The risk of recession is lower in the US, but more tightening is expected and is expected to be front-loaded.
In addition to central bank woes, a tighter lockdown in Shanghai as authorities press ahead with the zero-COVID policy adds to fears over the outlook for global growth. Chinese exports grew at the slowest pace in almost two years in April at 3.9%.
There is no high impacting data; sentiment is likely to continue driving the markets.
In corporate news:
Rivian tumbles 18% pre-marke5t on news that Ford is selling 8 million shares and that JP Morgan is selling a further 12 million for an unnamed investor. The EV maker’s insider lock-in period ends.
Uber also trades lower pre-market on reports that the ride-hailing app will scale back costs and hiring.
More news on the stocks to watch
Where next for the Nasdaq?
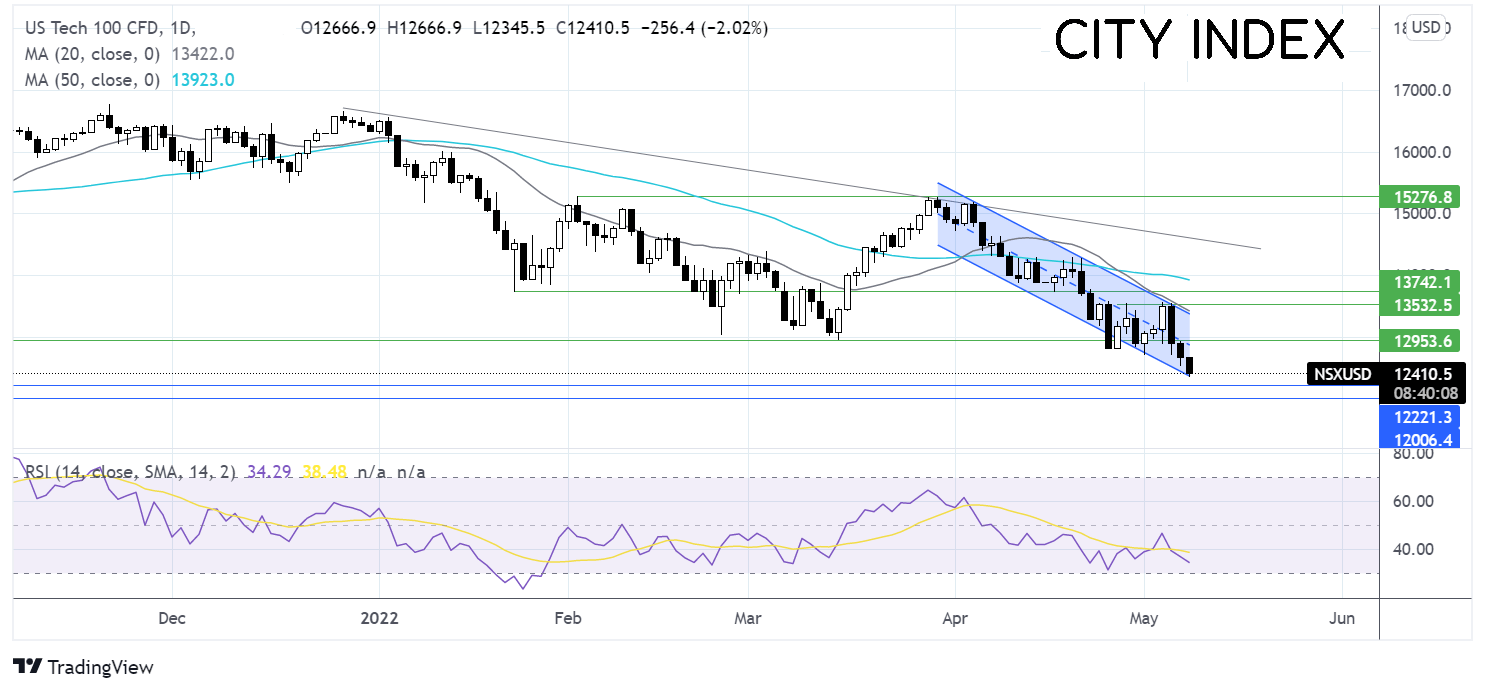
The Nasdaq continued to trade in the falling channel it has traded in since the start of April. The price trades at the lower end of the channel, which, combined with the bearish RSI, suggests that there could be more downside to come. Immediate support can be seen at 12345, today’s low, and the falling trendline support. A break below here could open the door to 12210, the March ’21 low and 12000 round number. Buyers will be looking for a move over 13000, the March low and midpoint of the falling channel, to head towards 13530, last week’s high.
FX markets USD steadies, and AUD drops.
USD is rising a few pips higher, adding to solid gains across last week on hawkish Fed bets and safe-haven flows. The Fed hiked rates by 50bp last week and is expected to continue acting aggressively to rein in 40-year high inflation; later in the week, US CPI data will be the main focus this week. Fed speakers are expected to continue the hawkish chorus. US dollar index rose to a 20-year high over 104.00 but has since pared some gains.
GBP/USD fell to 1.2250 but has managed to turn positive, heading towards the US open. The former BoE chief economist Andy Haldane warned that inflation could peak higher than 10%.
EUR/USD is rebounding after a weaker start today. Eurozone consumer confidence dropped to -22.6, below the 21.6 forecast, and down from -18 in March.
AUD/USD is the worst performer today, weighed down by the China woes and risk off trade. AUDUSD fell below 0.70 but has managed to recapture the psychological level.
GBP/USD +0.23% at 1.2370
EUR/USD +0.03% at 1.0540
Oil falls on demand fears
Oil prices are falling as China’s demand fears and the stronger USD overshadow Russian supply concerns.
Beijing is showing no signs of easing up on its strict zero-COVID policy, and tighter lockdown restrictions in Shanghai and Beijing are raising concerns over the demand picture. Concerns over the broader state of global growth add to the weaker demand picture. A slowdown in global growth means lower global oil demand.
These fears overshadow news that the G7 unveiled more sanctions on Russia over the weekend, including an embargo on Russian oil. This comes after the EU proposed a phased-in ban on Russian crude last week, the vote on which is expected to take place this week. All members must agree to the proposal.
The USD trading at a 20-year high means that oil is more expensive to buyers with foreign currencies, which hurts demand.
WTI crude trades -3.2% at $105.42
Brent trades -3.1% at $108.61
Learn more about trading oil here.
Looking ahead
N/A
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.