



US open: Stocks, USD rise after the US labour market tightens
US non-farm payrolls missed forecasts, but February saw a strong upward revision, the unemployment rate dropped and wages rose by more than expected.
Share this:

US futures
Dow futures +0.6 % at 34900
S&P futures +0.53% at 4560
Nasdaq futures +0.56% at 15125
In Europe
FTSE +0.1% at 7546
Dax +0.45% at 14490
Euro Stoxx +0.7% at 3931
Learn more about trading indices
Stocks jump, oil drops
Stocks are set to open higher after steep losses in the previous session and the previous quarter.
The new quarter is starting off on the front foot as peace talks resume, after stalling earlier in the week, and as the market digests the latest jobs data.
The US non-farm payroll report revealed that 431k jobs were added in March, slightly below the 490k forecast. However, the February report was upwardly revised to 750k.
The unemployment rate dropped by more than forecast to 3.6% down from 3.8% and wages grew at 5.6% YoY, up from 5.2% in February and above the 5.5%.
The data points to a tight labour market supporting expectations of a more hawkish Fed and support a 50 basis point rate hike from the Fed when they meet in May. Following the release, the USD rose, as did stocks, suggesting that the markets aren’t afraid of a more hawkish Fed.
In corporate news:
Automakers Ford and General Motors will be in focus after both firm decided to halt production in their Michigan factories owing to the global chip shortage.
GameStop will is trading 13% higher pre-market after announcing plans for a stock split late on Thursday.
Where next for the Nasdaq?
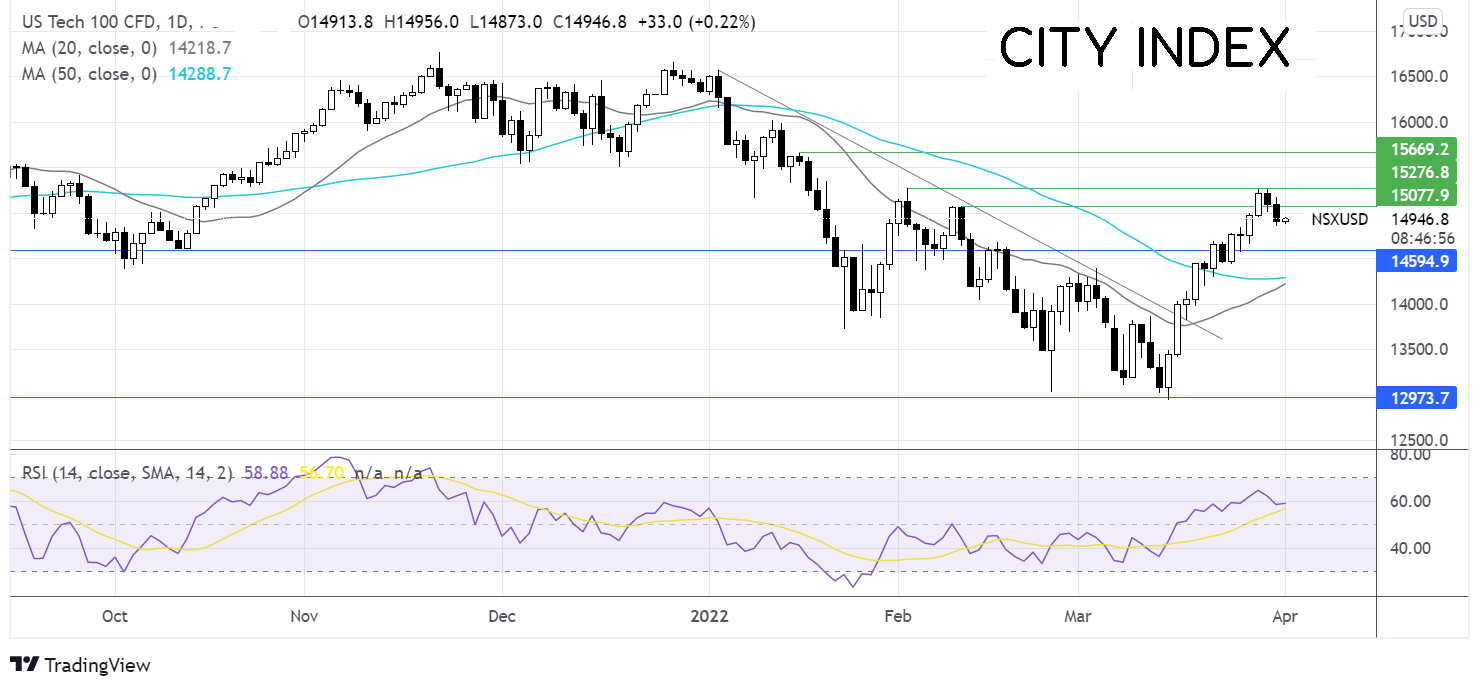
The Nasdaq extended its rebound from the 12950 low, recapturing the 20 & 50 sma, before running into resistance at 15250. After two attempts to break this level, the prices slipped low finding support at yesterday’s low of 14850. The bullish RSI combined with the 20 mas about to cross above the 50 sma keeps buyers optimistic. Immediate resistance can be seen at 15050 high 9 February, ahead of 15275 the February high. Immediate support can be seen at 14600 a level which has offered support and resistance on several occasions across the past 6 months. A break below here exposes the 50 sma at 14280.
FX markets USD rallies, EUR trades lower.
USD is rising after the jobs data and after strong gains yesterday. US data supports a hawkish move by the Fed.
The euro trades lower despite record inflation. Eurozone inflation hit 7.5% YoY in March, up from 5.9% and ahead of forecasts of 6.6%. The data could prompt the ECB to move sooner to hike rates
GBP/USD is falling as manufacturing PMI being downwardly revised to 55.2, from 55.5, marking the slowest manufacturing activity growth in 13 months.
GBP/USD -0.2% at 1.3122
EUR/USD -0.2% at 1.1104
Oil drops 5%
Oil prices fell 7% yesterday and are extending those losses again today. Oil prices are set to drop 12% across the week after booking 8% gains in the previous week. This would mark the biggest loss in oil over 2 years.
Oil has slipped back to $100 after the US announced that it could release 1 million barrels a day into the market over the coming 6 months. The steady supply back into the market has soothed supply fears which sent oil surging at the start of the war. However, it is still short of the 3 million barrels a month from Russia which are shut out from the market.
The move comes after OPEC+ kept wit their previously agreed plan, increasing output by 430,000 per day in May.
WTI crude trades -0.6% at $98.70
Brent trades -0.3% at $103.90
Learn more about trading oil here.
Looking ahead
15:00 ISM Manufacturing PMI
18:00 Baker Hughes rig count
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
US futures
Dow futures +0.6 % at 34900
S&P futures +0.53% at 4560
Nasdaq futures +0.56% at 15125
In Europe
FTSE +0.1% at 7546
Dax +0.45% at 14490
Euro Stoxx +0.7% at 3931
Stocks jump, oil drops
Stocks are set to open higher after steep losses in the previous session and the previous quarter.
The new quarter is starting off on the front foot as peace talks resume, after stalling earlier in the week, and as the market digests the latest jobs data.
The US non-farm payroll report revealed that 431k jobs were added in March, slightly below the 490k forecast. However, the February report was upwardly revised to 750k.
The unemployment rate dropped by more than forecast to 3.6% down from 3.8% and wages grew at 5.6% YoY, up from 5.2% in February and above the 5.5%.
The data points to a tight labour market supporting expectations of a more hawkish Fed and support a 50 basis point rate hike from the Fed when they meet in May. Following the release, the USD rose, as did stocks, suggesting that the markets aren’t afraid of a more hawkish Fed.
In corporate news:
Automakers Ford and General Motors will be in focus after both firm decided to halt production in their Michigan factories owing to the global chip shortage.
GameStop will is trading 13% higher pre-market after announcing plans for a stock split late on Thursday.
Where next for the Dow Jones?
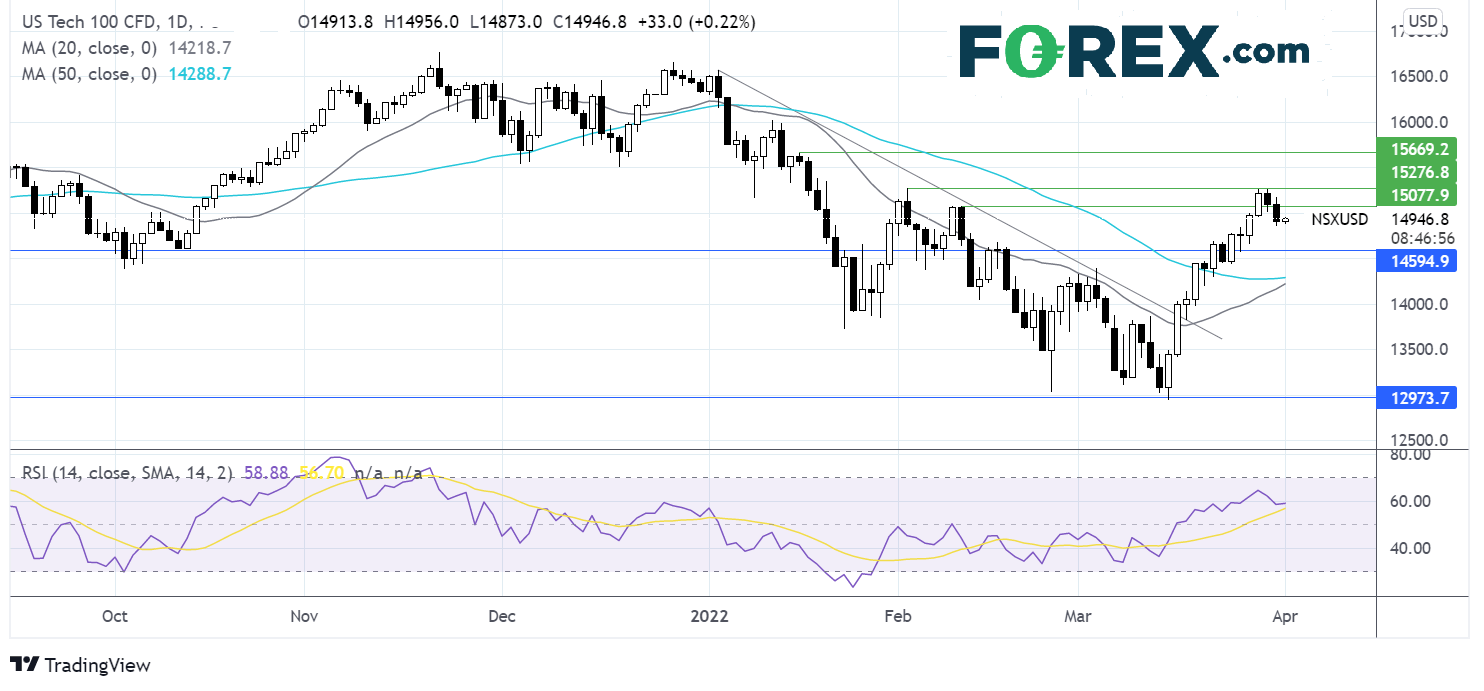
The Nasdaq extended its rebound from the 12950 low, recapturing the 20 & 50 sma, before running into resistance at 15250. After two attempts to break this level, the prices slipped low finding support at yesterday’s low of 14850. The bullish RSI combined with the 20 mas about to cross above the 50 sma keeps buyers optimistic. Immediate resistance can be seen at 15050 high 9 February, ahead of 15275 the February high. Immediate support can be seen at 14600 a level which has offered support and resistance on several occasions across the past 6 months. A break below here exposes the 50 sma at 14280.
FX markets USD rallies, EUR trades lower.
USD is rising after the jobs data and after strong gains yesterday. US data supports a hawkish move by the Fed.
The euro trades lower despite record inflation. Eurozone inflation hit 7.5% YoY in March, up from 5.9% and ahead of forecasts of 6.6%. The data could prompt the ECB to move sooner to hike rates
GBP/USD is falling as manufacturing PMI being downwardly revised to 55.2, from 55.5, marking the slowest manufacturing activity growth in 13 months.
GBP/USD -0.2% at 1.3122
EUR/USD -0.2% at 1.1104
Oil drops 5%
Oil prices fell 7% yesterday and are extending those losses again today. Oil prices are set to drop 12% across the week after booking 8% gains in the previous week. This would mark the biggest loss in oil over 2 years.
Oil has slipped back to $100 after the US announced that it could release 1 million barrels a day into the market over the coming 6 months. The steady supply back into the market has soothed supply fears which sent oil surging at the start of the war. However, it is still short of the 3 million barrels a month from Russia which are shut out from the market.
The move comes after OPEC+ kept wit their previously agreed plan, increasing output by 430,000 per day in May.
WTI crude trades -0.6% at $98.70
Brent trades -0.3% at $103.90
Looking ahead
15:00 ISM Manufacturing PMI
18:00 Baker Hughes rig count
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.