



US open: Tech stocks underperform as treasury yields jump
Inflation concerns and expectations of a sooner move by the Fed to raise interest rates, even as Omicron cases surge are unnerving investors.
Share this:

US futures
Dow futures -0.26% at 36137
S&P futures -0.35% at 4648
Nasdaq futures -1.16% at 15408
In Europe
FTSE +0.08% at 7480
Dax -0.35% at 15881
Euro Stoxx -0.5% at 4280
Learn more about trading indices
Inflation fears rise
US stocks are set to open lower as investors fret over rising inflation and the Fed hiking interest rates at the same time that Omicron cases are surging higher.
US treasury yields rose to a fresh 2 year high amid growing expectations that the Fed will tackle surging inflation head on this year raising rates at a faster pace than initially expected.
Tech stocks, which are particularly sensitive to higher interest rate expectations are once again under performing as investors rotate out of high growth stocks into value, with bank stocks rising on the prospect of a rate hike boosting net interest income.
Whilst there is no high impacting US data due for release today attention is firmly on US inflation data and a speech by Fed chair Powell later in the week. Inflation is expected to come in at 7%, which could prompt more hawkish commentary from the Fed, cementing the way to a rate hike potentially as soon as March.
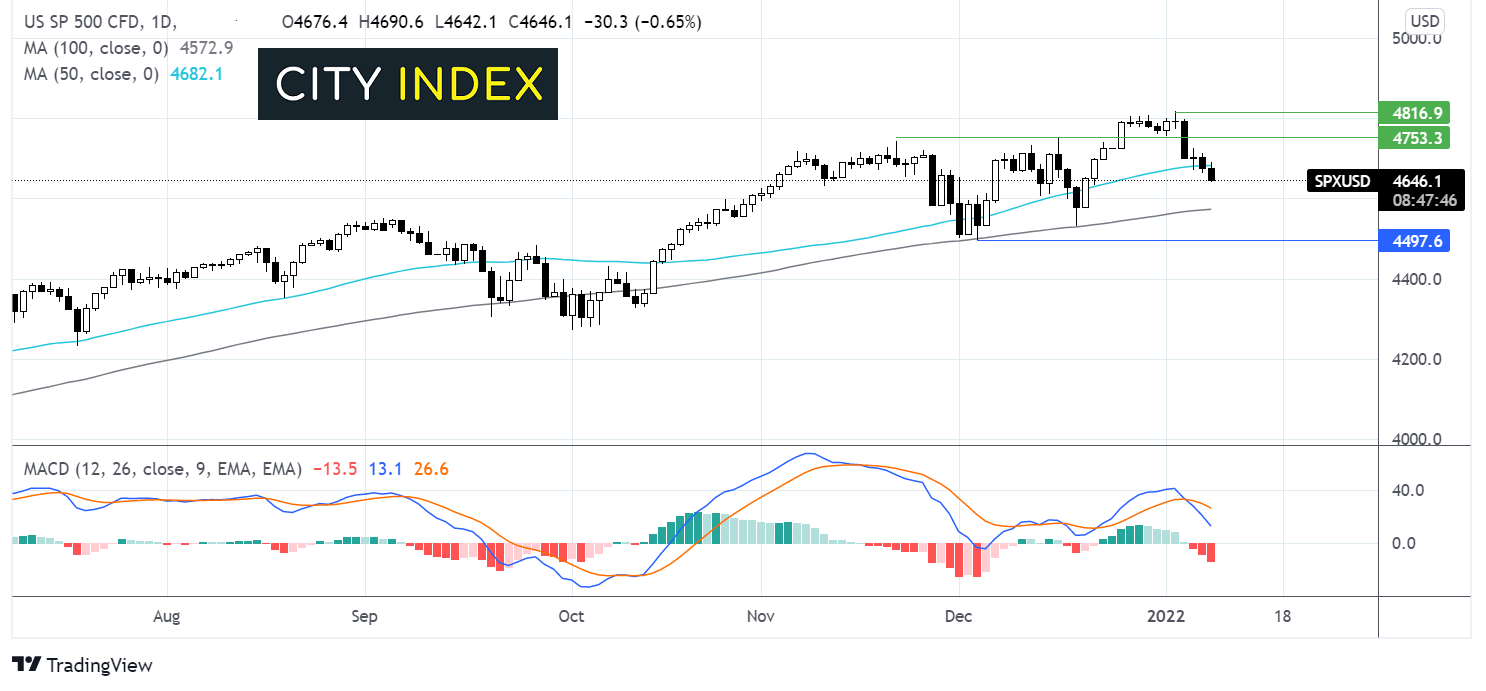
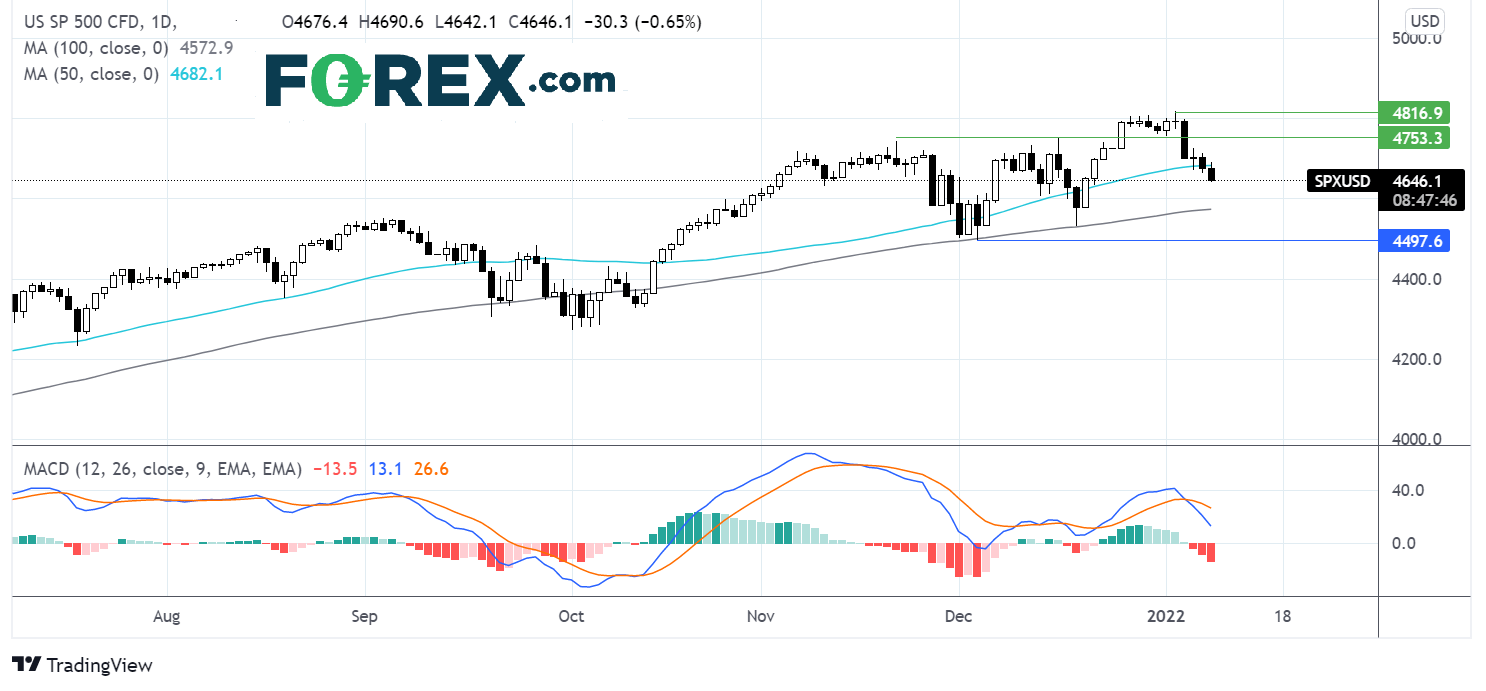
Where next for the S&P500?
After hitting an all time high of 4617 earlier in January, S&P500 is falling lower. The price declining through the 50 sma and the bearish cross over on the MACD are keeping sellers hopeful of further downside. The 100 sma has acted as a key support in November and December making it a key level to watch at 4577 ahead of 4500 the December low. On the upside a move above the 50 sma at 4680 and 4750 could see the price look back towards 4816 and fresh all-time highs.
FX – USD rebounds, EUR slumps despite upbeat data
The USD is on the rise recouping losses from the previous week. The greenback fell sharply on Friday after the headline non-farm payroll figure significantly missed forecasts. However, inflation fears are back, along with expectations of a sooner move by the Fed to raise rates, boosting the USD.
EUR/USD trades under pressure despite upbeat data from the bloc. Unemployment in the Eurozone continues to decline, dropping to 7.2%, down from 7.3%. Meanwhile Sentix investor sentiment unexpectedly improved in January to 14.9, up from 13.5. The data suggests that investors are not expecting economic momentum to stall in the new year despite rising COVID cases.
GBP/USD -0.15% at 1.3573
EUR/USD -0.37% at 1.1314
Oil steadies after strong gains
Oil prices are holding steady after booking big gains in the previous week. Oil jumped almost 5% across last week amid output disruption in Kazakhstan and Libya. Supply concerns remain, however, these are being offset by concerns over future demand as Omicron cases surge across the globe.
Protests in Kazakhstan had hit production at Tengiz, the country’s top oil field. However, output is gradually returning which could act as a tailwind on oil prices.
News that OPEC+ is failing to keep up with the allowed 253,000 bpd increase agreed is supporting the price of oil. OPEC+ managed to increase production by just 70,000 bpd in December compared to the previous month.
WTI crude trades -0.74% at $78.04
Brent trades -0.6% at $81.07
Learn more about trading oil here.
Looking ahead
N/A
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.