



USDJPY BOJ related rally stalls as JGB yields surge
The dollar’s choppiness has been a dominant theme for several weeks now, but as we come to the business end of this week, it could finally make a more decisive move in one or the other direction.
Share this:

The dollar’s choppiness has been a dominant theme for several weeks now, but as we come to the business end of this week, it could finally make a more decisive move in one or the other direction. The indecisiveness is a reflection of a tired bullish trend: market participants have been piling in on the greenback for several months amid an improving macro picture in the US and speculation over further rate hikes from the Federal Reserve. However, the Fed’s near term tightening cycle outlook may already be either fully or partially priced in by now, while investors are also aware that at the same time other major central banks such as the Bank of Canada and Bank of England are tightening their belts, which has been or could be boosting the values of their currencies. Yet, to complicate things further, some other central banks such as the Bank of Japan remain stubbornly dovish, which is keeping the dollar bulls still in the game.
Decent pre-NFP leading indicators so far
But with the FOMC and nonfarm payrolls on tap this week, the dollar may make a more decisive move. Today we have had the first key leading indicators for NFP in the form of the ADP private sector payrolls report and the employment component of the ISM services PMI. Both have been stronger than expected, which bodes well for Friday’s official jobs report – if one can trust these to be good employment leading indicators. The ADP report showed a sizeable 219,000 net private sector jobs gained in the month of July versus 186,000 expected. However, the ADP and NFP do not always have a good correlation with each other and we have seen sizeable deviations in the past. And that’s where the good news ended. A few moments ago we had the July ISM manufacturing PMI, which came in weaker at 58.1 vs. 59.4 expected and 60.2 last. The detail of the report showed a few unwelcome surprises, too. The Prices Paid index fell to 73.2 vs. 75.3 and 76.8 last, New Orders dipped to 60.2 vs. 63.5 last, but crucially Employment sub index rose to 56.5 vs. 56.0 last. Elsewhere, construction spending unexpectedly fell 1.1% month-over-month in June.
FOMC likely to be a non-event
The employment index on non-manufacturing sector PMI will be released after the NFP on Friday. So, we will have a key pre-NFP leading indicator for this month’s jobs data missing. Meanwhile the Federal Reserve’s meeting tonight is likely to be a non-event as rates are likely to be lifted at the September meeting instead. Indeed, there is no press conference scheduled for tonight’s rate decision. Still, the policy statement may convey some particularly hawkish or dovish messages, which could lead to some volatility for the dollar. But the NFP is likely to garner more attention on Friday and it could be a long wait until then.
Rising Japanese yields may undermine USD/JPY
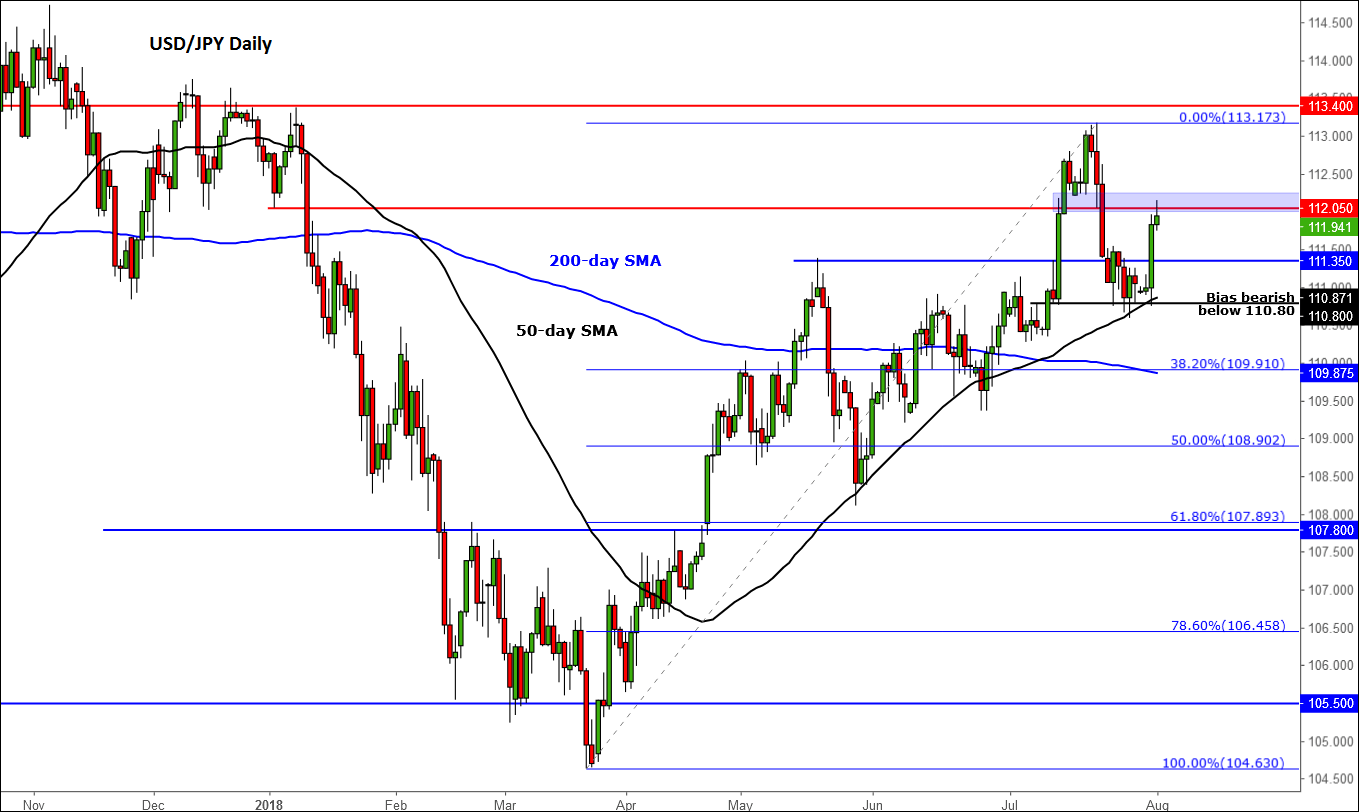
Meanwhile, the dollar has stopped going up against the yen today. The USD/JPY was trading only a touch higher at the time of writing after its sizeable rally the day before, when it jumped on the back of a dovish Bank of Japan. What’s interesting is the reaction of the Japanese government bonds which have sold off, pushing yields higher. The yield on the 10-year has risen above 0.13% today, its highest level since January 2017. In fact, it has risen faster than the equivalent US 10-year yield today, which climbed above 3% again. This may be an indication that the USD/JPY may be unable to hold onto its BoJ-related gains. Indeed, the USD/JPY had already reacted off of 112.00/112.20 resistance area earlier today, before bouncing back a little. If this level holds as resistance then rates could be pushed down again later on. But a daily close above here would probably be game over for the short-term USD/JPY bears.
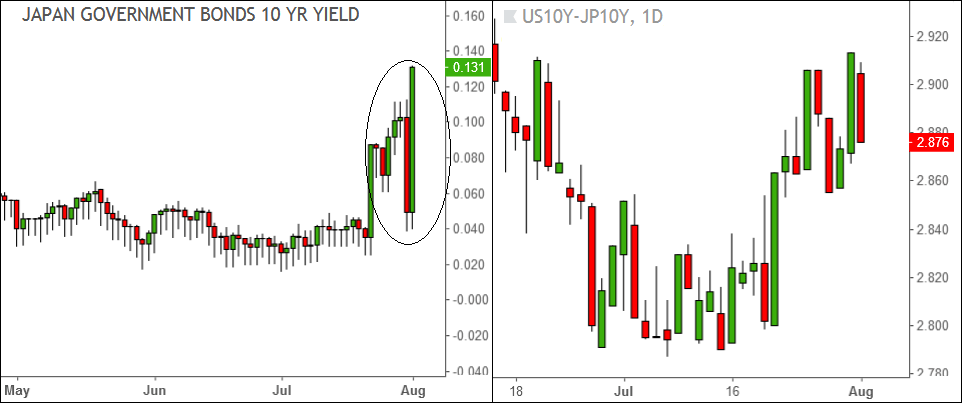
Source: TradingView.com and FOREX.com.
Source: TradingView.com and FOREX.com.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.