



Week Ahead RBNZ Eurozone CPI and G20 meetings
Heading into the new week, we are expecting to see further short term gains for stocks amid bullish technical momentum arising from this week’s central bank action, but we are not too sure whether the bulls will go all out buying every single dip given the increased risks to economic growth and ongoing trade tensions.
Share this:

This week was all about the major central banks as the race to zero and beyond resumed, with the Fed and ECB signalling potential rate cuts while the BoE was slightly less hawkish than had been expected. The RBA’s governor hinted at the prospects of loosening monetary policy even more after the 25 basis point cut earlier in the month, while the BoJ was unsurprisingly dovish as well. With all these banks willing to keep yields depressed, global stocks rallied which saw the S&P 500 hit a fresh record high. Buck-denominated and noninterest-bearing precious metals also rallied with gold soaring above $1400 to reach its best level since September 2013.
Heading into the new week, we are expecting to see further short term gains for stocks amid bullish technical momentum arising from this week’s central bank action, but we are not too sure whether the bulls will go all out buying every single dip given the increased risks to economic growth and ongoing trade tensions. Speaking of which, the focus will slowly turn to the upcoming G20 meetings in Japan towards the end of next week. Donald Trump has already told us that he had a good phone conversation with Chinese Premier Xi and that their teams will be meeting ahead of the G20 summit in preparations. Fresh comments via Trump’s twitter handle on this topic could move the markets, so watch out.
However, before the G20 meetings start, there will be one more major central bank interest rates decision to come: the Reserve Bank of New Zealand, on Wednesday. Given the somewhat unexpected cut last month, the RBNZ is unlikely to trim rates again at this meeting, but it may well give a clear indication about another potential cut at a near future meeting.
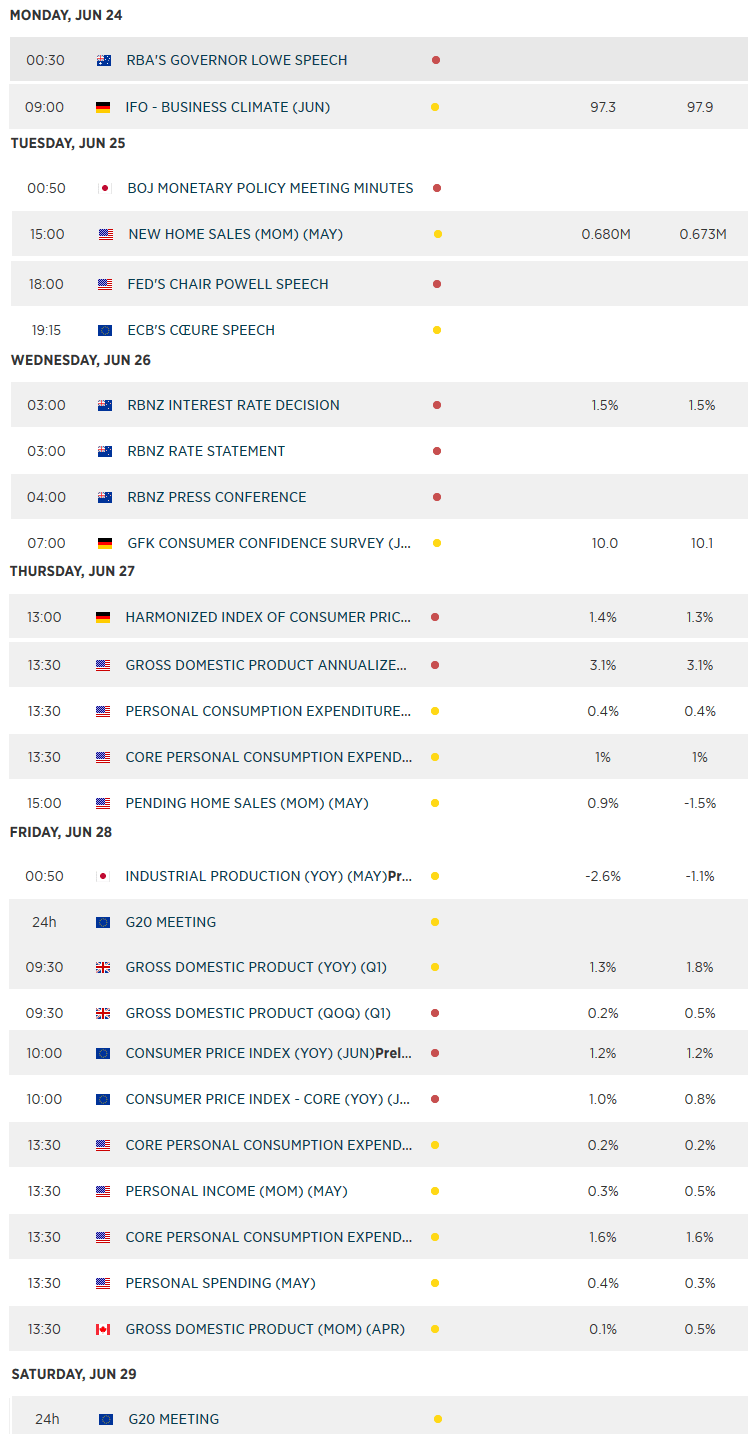
Among next week’s other highlights, we will have Eurozone CPI and a few macro pointers from the US towards the end of the week, as shown in the edited-down economic calendar, below. All eyes will be on incoming Eurozone data after the ECB signalled it may cut interest rates soon, and CPI will be key in that regard. However, Friday’s PMI data surprised to the upside, suggesting the Eurozone economy may have bottomed and the EUR/USD spiked above 1.1350 late in the day on Friday. If we see further strength in Eurozone data, then Draghi and co. at the ECB may have to switch back to a neutral stance.This week was all about the major central banks as the race to zero and beyond resumed, with the Fed and ECB signalling potential rate cuts while the BoE was slightly less hawkish than had been expected. The RBA’s governor hinted at the prospects of loosening monetary policy even more after the 25 basis point cut earlier in the month, while the BoJ was unsurprisingly dovish as well. With all these banks willing to keep yields depressed, global stocks rallied which saw the S&P 500 hit a fresh record high. Buck-denominated and noninterest-bearing precious metals also rallied with gold soaring above $1400 to reach its best level since September 2013.
Heading into the new week, we are expecting to see further short term gains for stocks amid bullish technical momentum arising from this week’s central bank action, but we are not too sure whether the bulls will go all out buying every single dip given the increased risks to economic growth and ongoing trade tensions. Speaking of which, the focus will slowly turn to the upcoming G20 meetings in Japan towards the end of next week. Donald Trump has already told us that he had a good phone conversation with Chinese Premier Xi and that their teams will be meeting ahead of the G20 summit in preparations. Fresh comments via Trump’s twitter handle on this topic could move the markets, so watch out.
However, before the G20 meetings start, there will be one more major central bank interest rates decision to come: the Reserve Bank of New Zealand, on Wednesday. Given the somewhat unexpected cut last month, the RBNZ is unlikely to trim rates again at this meeting, but it may well give a clear indication about another potential cut at a near future meeting.
Among next week’s other highlights, we will have Eurozone CPI and a few macro pointers from the US towards the end of the week, as shown in the edited-down economic calendar, below. All eyes will be on incoming Eurozone data after the ECB signalled it may cut interest rates soon, and CPI will be key in that regard. However, Friday’s PMI data surprised to the upside, suggesting the Eurozone economy may have bottomed and the EUR/USD spiked above 1.1350 late in the day on Friday. If we see further strength in Eurozone data, then Draghi and co. at the ECB may have to switch back to a neutral stance.

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.