



Weekly COT report: Divergences form between FX prices and trader positioning
As the data was compiled ahead of the FOMC meeting its likely there are some distortions in this week’s speculative positioning report.
Share this:
As of Tuesday 25th January 2022:
- Net-long exposure to the US dollar fell for a second week, down -$2.3 billion to $10.7, according to data compiled by IMM
- Traders were their most bullish on euro futures in 23-weeks
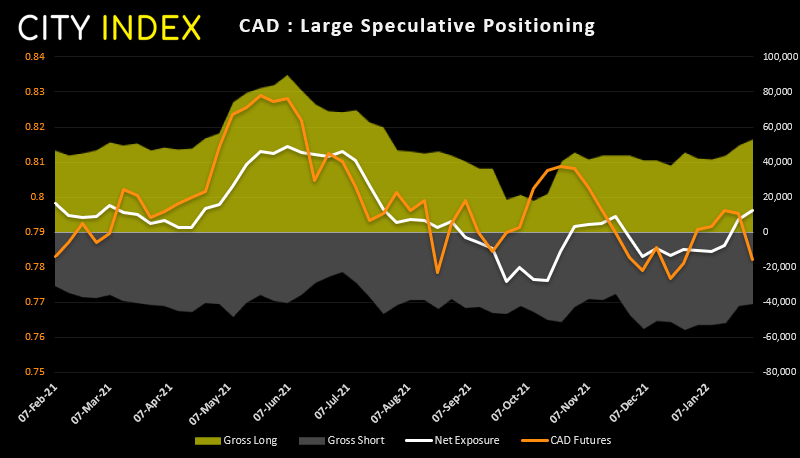
- Net-long exposure to CAD futures rose to their highest level in 8-months
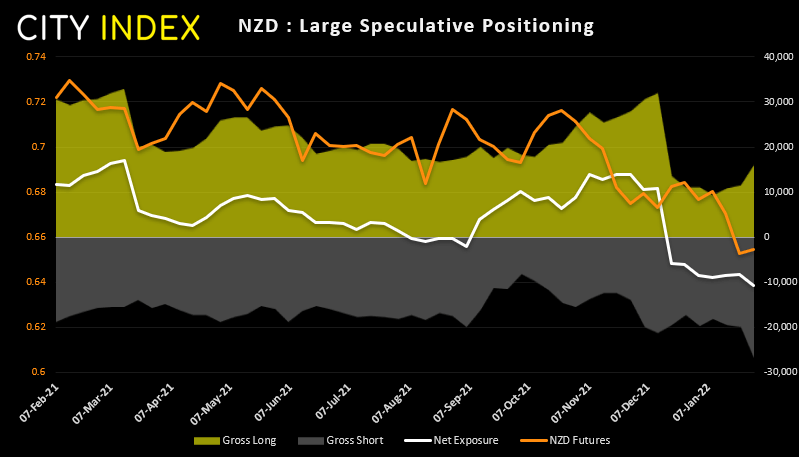
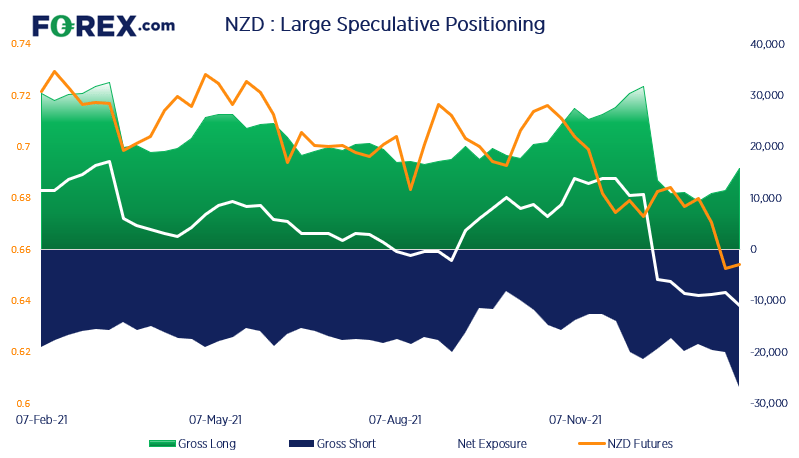
- Net-short exposure to NZD future rose to its most bearish level since June 2020


Read our guide on how to interpret the weekly COT report
Read our guide on how to interpret the weekly COT report
Euro futures:
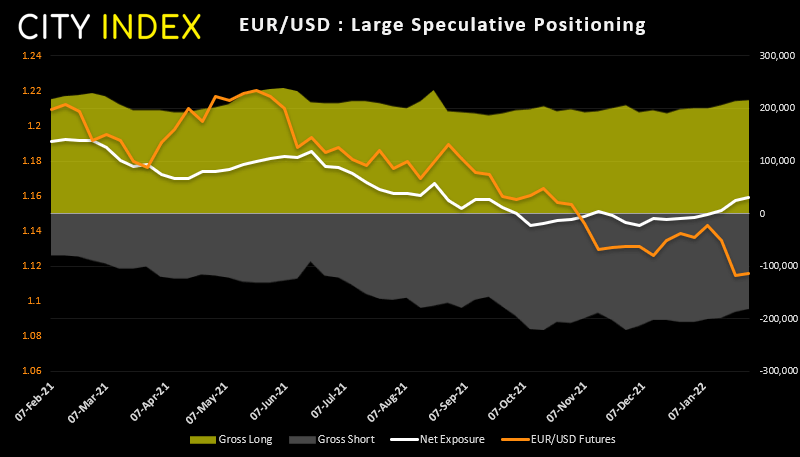
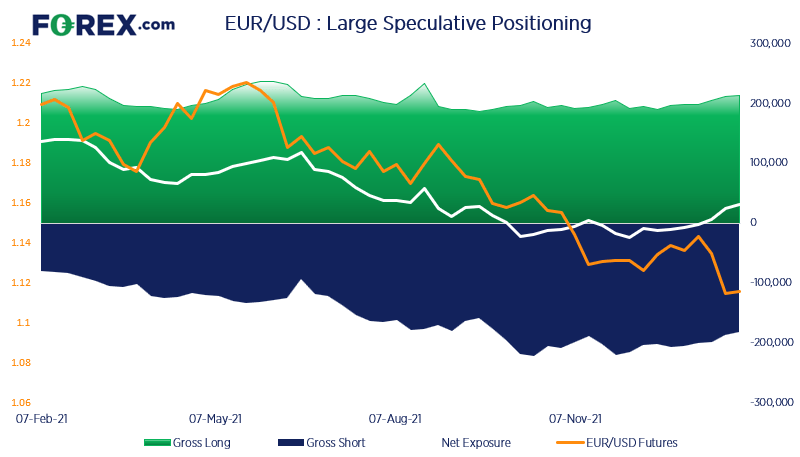
Net-long exposure to euro futures rose to a 23-week high as of last Tuesday. And the move has been powered by a fast rise in gross longs with a sharp reduction of net-shorts. Yet since this report was compiled, EUR/USD has fallen to a 19-month low thanks for the hawkish press conference after the FOMC meeting. So, which one is correct? Yield differentials favour a lower euro and we have likely seen some of those longs closed out and new shorts initiated. We therefore think EUR/USD is more likely to test 1.10 before it reclaims 1.13.
This image will only appear on cityindex websites!
CAD futures:
The Canadian dollar is another currency which is trading in the opposite way that speculative positioning suggests. Net-long exposure sits at a 27-week high with rising longs and diminishing short. Yet like the euro we have also had a hawkish FOMC meeting to contend with which weighed on all currencies except the US dollar. And that could see a reversal in net-long exposure over the coming weeks as it potentially flips back to net-short positioning.
Read our guide on the A guide to CAD
Read our guide on the A guide to CAD

NZD futures:
The New Zealand dollar remains very much unloved with net-short exposure rising to its most bearish level since June 2020. However, whilst gross shorts have also risen to their highest level if the same period, gross longs have also increased. It seems some investors are either hedging their bets or stepping in to pick up a bargain at these lows. And we lean towards the latter given that RBNZ remain hawkish and inflation continues to surge well above RBNZ’s target.
As of Tuesday 25th January 2022:
- Net-long exposure to platinum futures nearly doubled, and rose to its most bullish level in 10-weeks
- Traders increased net-long exposure to copper futures for a second week, and to a 3-month high
- Traders increased their net-long exposure to gold to a 7-week high
Platinum futures:
Net-long exposure rose to a 10-week high, from 7.3k to 13.8k contracts. However, this is mostly a function of short-covering as -6.4k short contracts were closed whilst longs added a mere 125 contract. Still, price action does suggest the market is trying to bottom and every trend change must start somewhere. Going forward rising prices alongside increase of gross longs is desirable for the bull-case.


How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.
EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.


Crude Oil Weekly Outlook: Geopolitics vs Oversupply Risks
Crude Oil Weekly Outlook: The IEA has flagged the risk of an oil supply surplus since the Iran war began. Yet WTI and Brent have held onto bullish rebounds from key support near 84 and 89, respectively, as geopolitical risks persist.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.