EUR/USD unchanged post EZ CPI and ahead of US data
- Eurozone CPI falls back to 2% target in December
- US ADP payrolls, ISM services PMI is due later
- EUR/USD hovers below 1.17

EUR/USD is unchanged as Eurozone inflation eases and as investors look ahead to U.S. economic data later in the session.
Eurozone inflation fell to 2% year on year in December, hitting the ECB's target for the first time since the summer and supporting the case for interest rates to remain on hold. The figure was in line with expectations and down from 2.1% recorded in November.
The data comes after the ECB left rates unchanged at 2% for the 4th consecutive meeting in December, with no further rate cuts expected from the central bank this year. The ECB forecast inflation will average at 1.9% this year, down from 2.1% in 2025. Meanwhile, growth is expected to be more resilient with the central bank expecting GDP growth of 1.2%, up from a previous estimate of 1%.
Meanwhile, the US donor is trading quietly against its major peers as the FX markets have largely brushed off deepening geopolitical fractures around the world in quiet trade despite the US intervention in Venezuela and the capture of President Maduro.
The market is in a wait-and-see mode ahead of the US ADP private payrolls job openings data and ISM services PMI figures. These data points come ahead of Friday's nonfarm payroll report and could provide some clarity on the outlook for rates. Investors have struggled to get an accurate read of the world economy following the US government shutdown
EUR/USD forecast – technical analysis
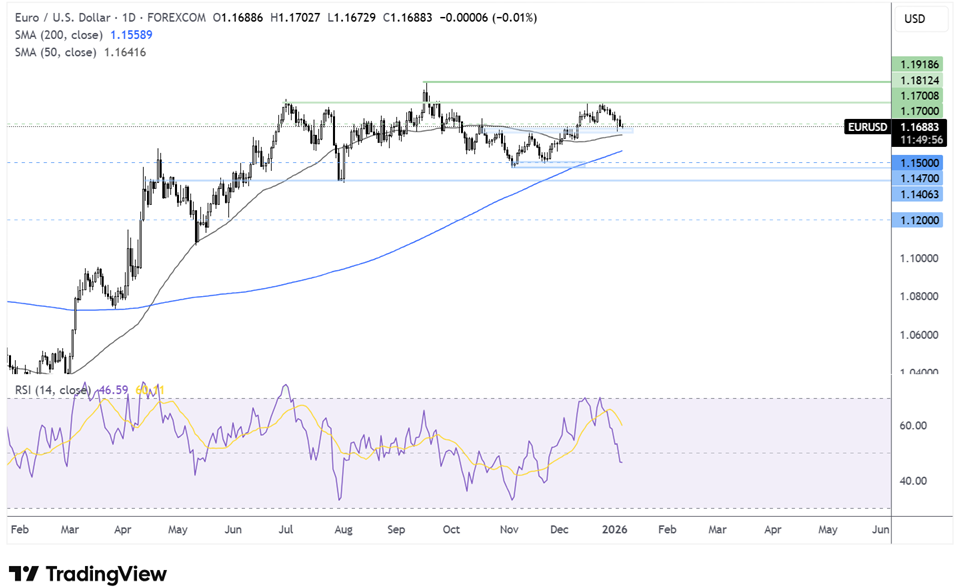
EUR/USD’s recovery from 1.15 November low ran into resistance at 1.18 and has eased lower. The price is testing the 1.1650-1.1680 support zone.
Sellers supported by the RSI below 50 will look to break below the support zone and the 50 SMA at 1.1640, exposing the 200 SMA at 1.550. A break below here brings 1.15 and the November low back into focus.
FTSE ends 4-day winning streak as oil prices drop
- FTSE eases from record high
- Oil majors track oil prices lower
- Miners track precious metal prices lower
- FTSE holds above 10,000
The FTSE 100 His falling on Wednesday following a record high yesterday and four consecutive days of gains. UK indexes are being dragged lower by heavyweight commodity stocks, amid a drop in oil and precious metal prices.
Oil majors such as Shell and BP are down more than 2% after President Trump said Venezuela would send up to 50 million barrels of oil to the market for sale. This is a bearish development for oil, with prices already 18% lower across 2025. The prospect of higher supply has pulled oil prices down a further 1%, with oil majors tracking the price lower.
Gold and silver prices were also easing lower, trimming recent gains for miners. Fresnillo is trading 3% lower, and Endeavour Mining is down just over 1%.
The market will continue to monitor developments in the US and Greenland following Trump's announcement of plans to acquire the territory. This is a move that European top leaders have voiced concerns about.
Looking ahead, attention will be on US ADP payroll reports and the November JOLTS job reports, which precede Friday's nonfarm payrolls report.
Looking at individual stocks, NatWest is lower after a downgrade, while most of Vodafone is topping the 5100 following an upgrade from Berenberg to buy from hold.
FTSE forecast - technical analysis
The FTSE trades above its rising trendline dating back to April and rose to a record high of 10,160 in the previous session. The price has eased back slightly today but remains above the key 10,000 psychological level. The RSI is coming out of overbought territory.
Buyers will look to extend gains beyond 10,160 towards 10,200 and 10,300 as the next logical levels.
Support is seen at 9920, the November high. Below here 9800, the rising trendline support comes into play. It would take a move below 9600, the December low to create a lower low.