


AUD/USD, ASX 200 rebound on China market surge, not RBA
The RBA continues to see the risk that rates may increase again despite delivering updated forecasts showing faster progress in bringing inflation back to within its target band. For AUD/USD traders, there was more interest in the rally in Chinese stocks and currency than what the bank had to say.
Share this:
- The RBA retained a tightening bias at its February interest rate decision
- It remains concerned about services inflation which is heavily influenced by labour market conditions
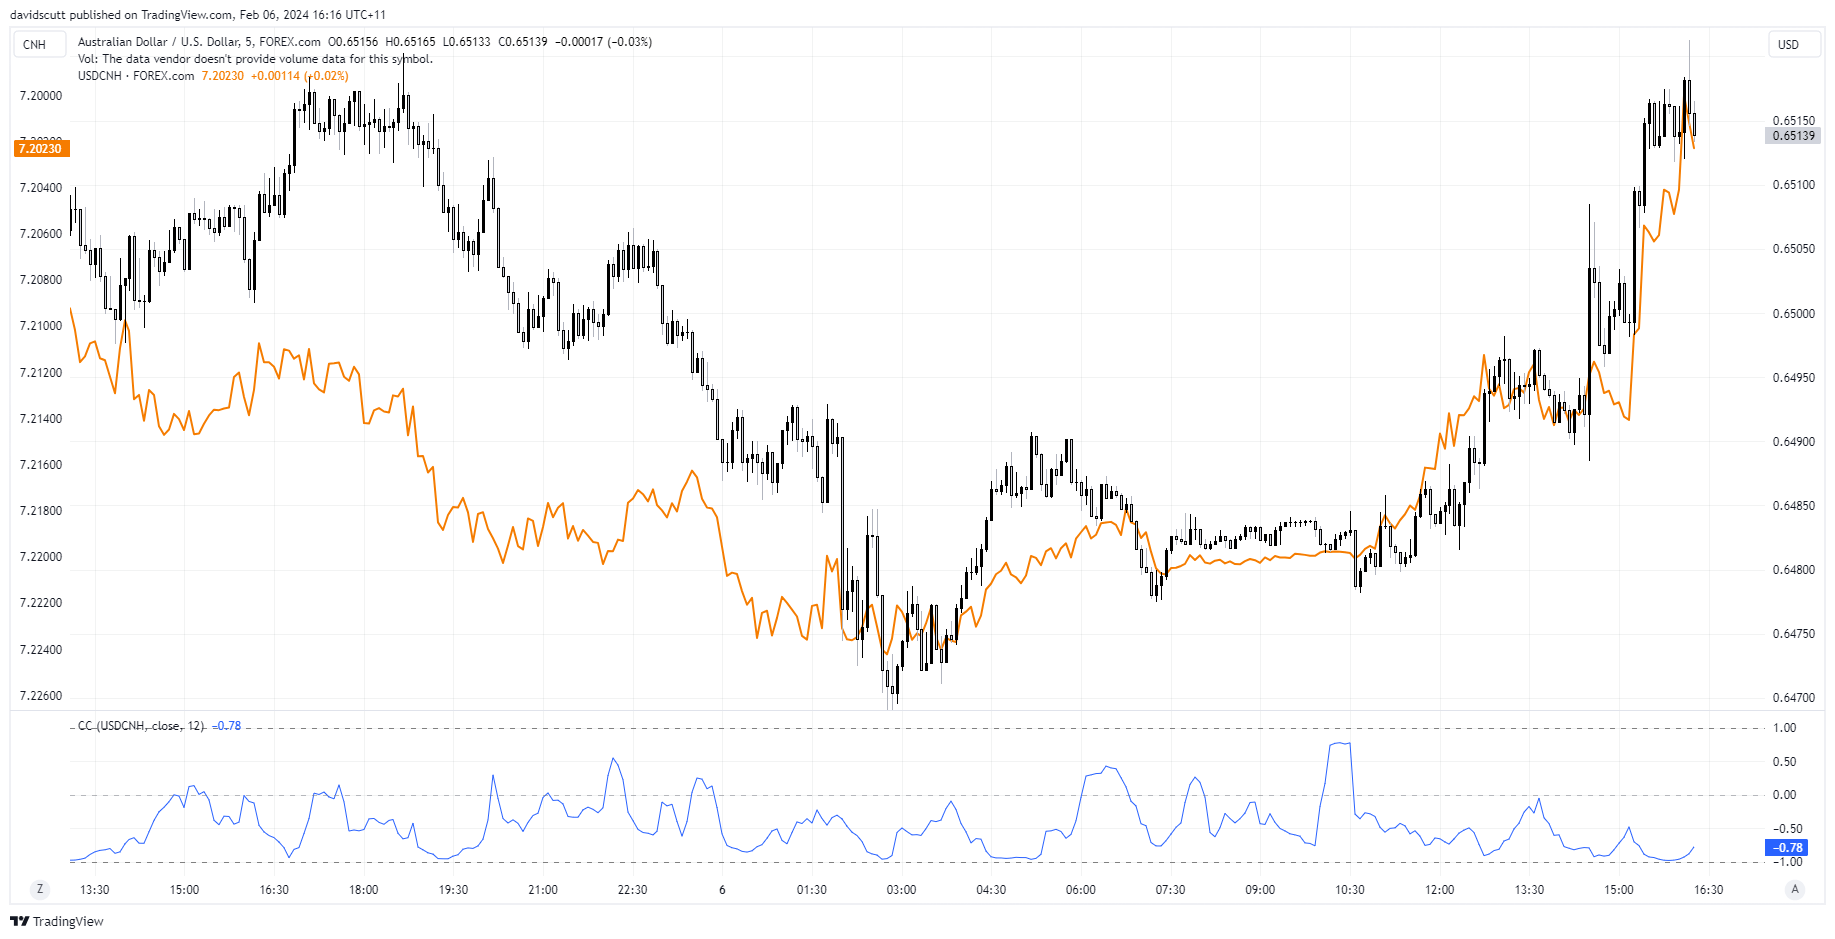
- AUD/USD traded in lockstep with Chinese markets throughout much of the RBA press conference
The Reserve Bank of Australia (RBA) continues to see the risk that rates may increase again despite delivering updated forecasts showing faster progress in bringing inflation back to within its target band. For AUD/USD traders, there was more interest in the rally in Chinese stocks and currency than what the bank had to say. ASX 200 traders received the message that rate cuts are unlikely to occur imminently.
RBA retains right to hike again… for now
Ahead of today’s decision which not only included the policy statement but also updated forecasts and a press conference from Governor Michelle Bullock, the main question markets wanted answered was whether the RBA would jettison its tightening bias, indicating the risk that rates may need to be increased further.
It did.
“The path of interest rates that will best ensure that inflation returns to target in a reasonable timeframe will depend upon the data and the evolving assessment of risks, and a further increase in interest rates cannot be ruled out,” it said.
While a softer tone than that offered two months ago when policymakers last met, perhaps because the statement is now written by the board rather than the Governor solely, it signals the RBA is not yet ready to signal the top is in for rates.
The pivot party will have to wait for another day.
RBA’s forecasts are more dovish than three months ago
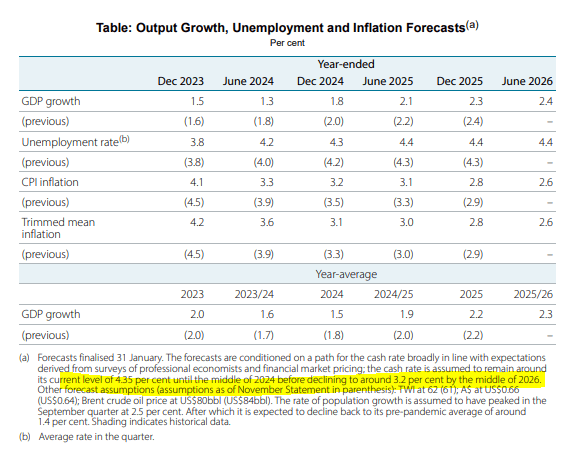
However, the bank’s updated quarterly forecasts suggest the bank is not too far away from joining most other developed central bank peers in shifting the debate as to when to begin cutting rates.
Source: RBA
Relative to three months ago, GDP growth was downgraded, unemployment seen higher while headline and core inflation are now expected to move towards the bank’s 2-3% target bank earlier. Importantly, those forecasts were premised on the cash rate being reduced by over 100 basis points between the middle of this year and mid-2026, far more easing that what was incorporated into the forecasts three
Job market data should increase in importance
While the RBA says it needs to be “confident that inflation is moving sustainably towards the target range” before pivoting towards rate cuts, its main concern is services inflation which is influenced by labour market conditions, including wage pressures and productivity growth.
It means that for the RBA to get the confidence it needs to cut, it probably needs to see the job market weaken more than it already has. For traders, that gives you a good clue as to what data releases the markets will be paying closer attention looking ahead.
The washup from the event was markets pared back expectations for the timing of the RBA’s first rate, pricing an August move at around 80%. Late last week, a cut was 100% priced for June. The shift largely reflects a recalibration of expectations on when and how much the Federal Reserve will cut.
AUD/USD driven by Chinese yuan, stocks
While the RBA provided plenty of talking points – including the standard of the questions provided to the Governor at her press conference – apart from a small pop on the bank retaining a tightening bias, AUD/USD traders were more fixated on what was going on in China than RBA headquarters at the top of Martin Place in Sydney.
I posted the below chart on social media following the conclusion of the press conference, showing the correlation between AUD/USD and USD/CNH running at -0.9 or lower over much of the event. That suggests that during Asian trade this week, the performance of Chinese markets may dictate how the Aussie fares.
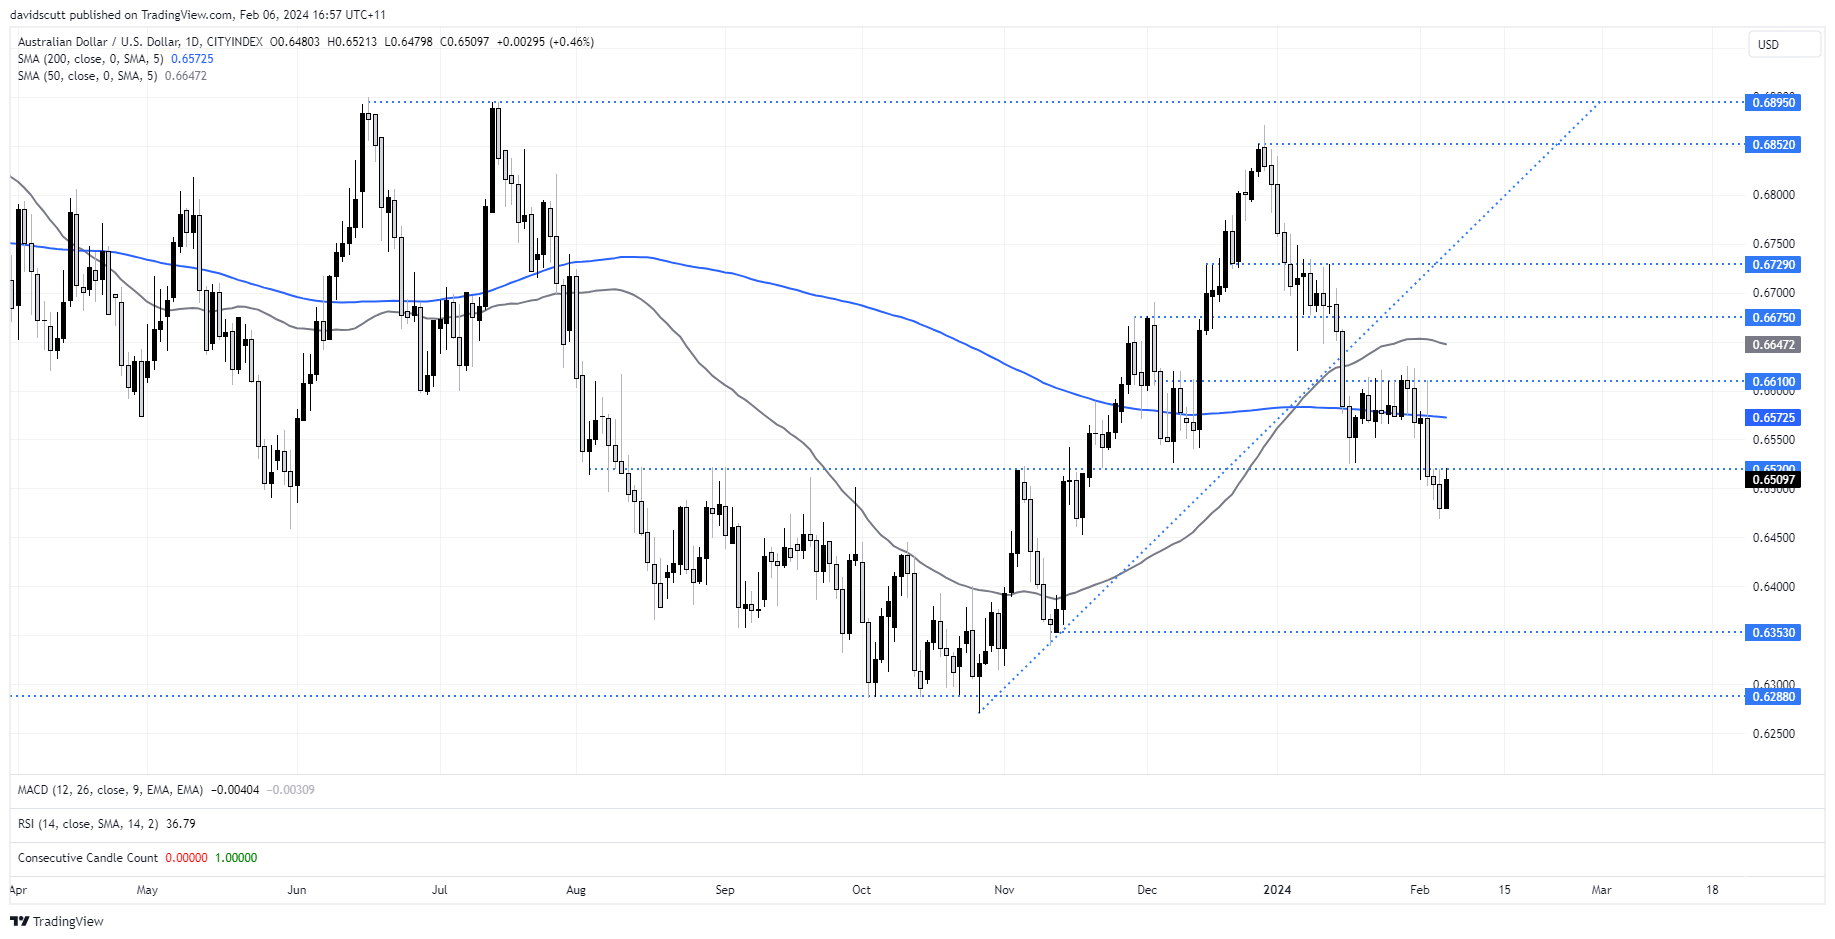
Zooming out on the AUD/USD using the daily chart, the pair traded up to resistance at .6520 on the back of the China surge before stalling, putting it on track for a third straight failure at this level. Below, apart form minor support around .6450, there’s not else visible until you get back to .6350. On the topside, a clean break of .6520 opens the door for a bounce back to resistance at .6610.
ASX 200 not impressed by lack of rate cut urgency
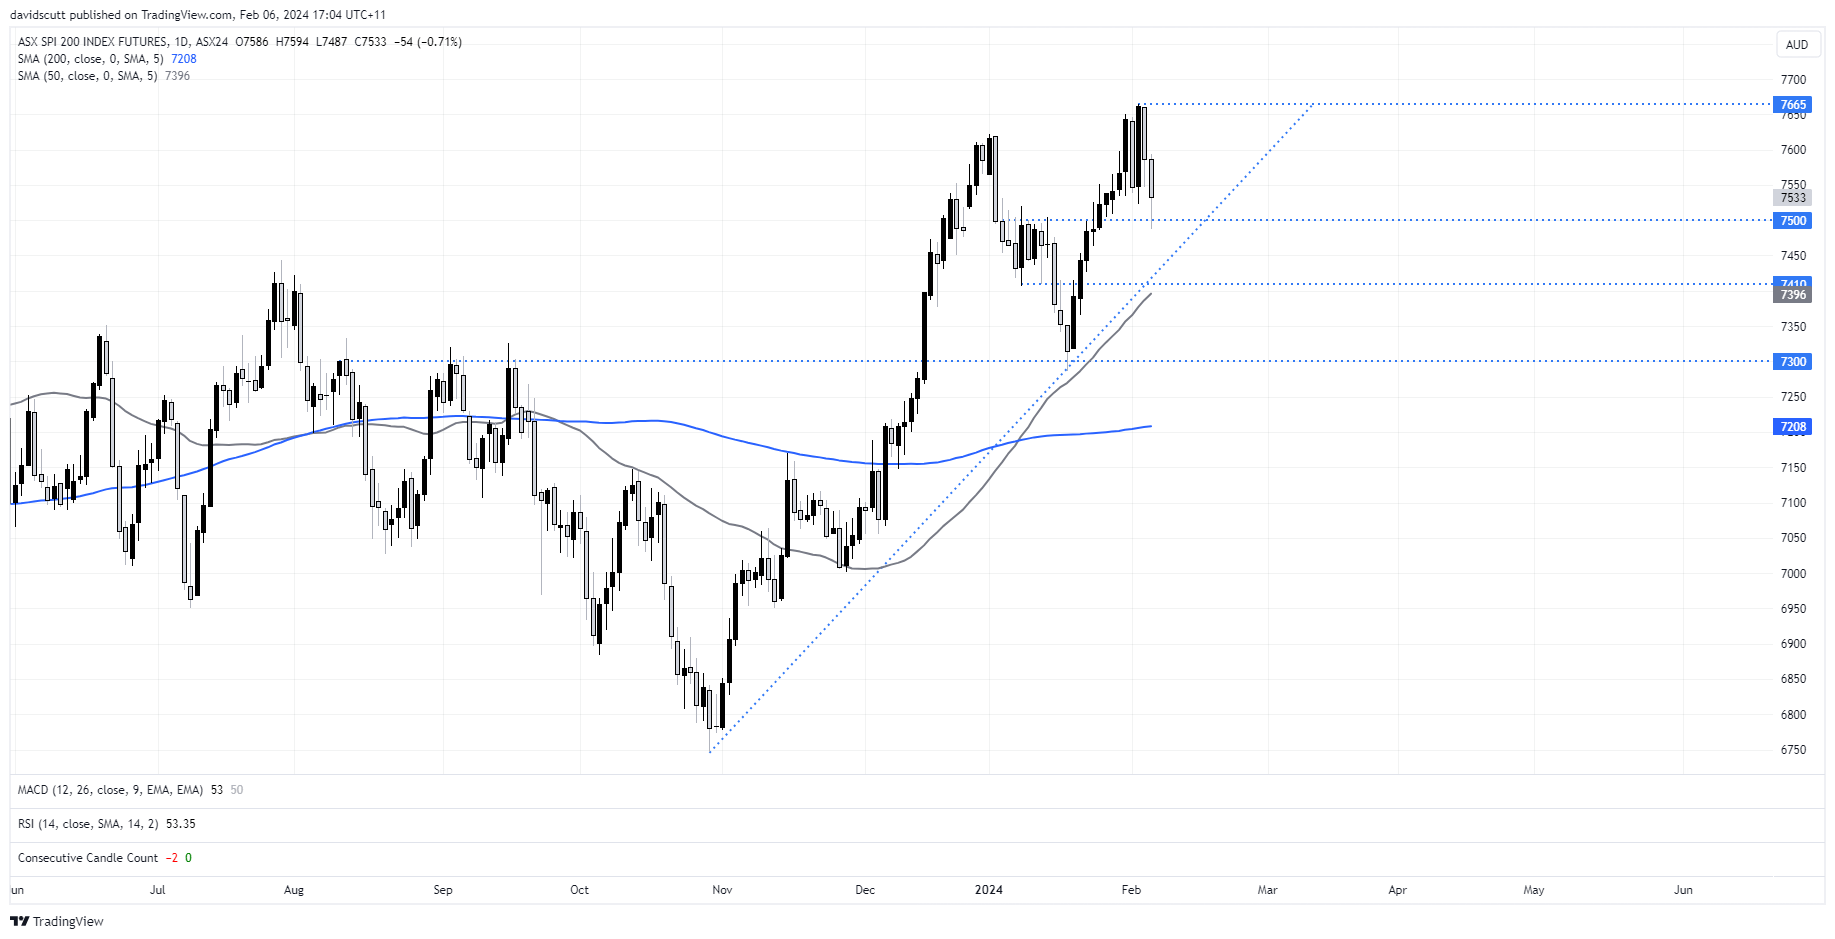
ASX 200 traders were a little more interested in what the RBA had to say, although futures did find a late bid as Chinese stocks rallied. Resistance is located at the prior record high of 7665 with support located at 7500, 7410 and again at 7300.
-- Written by David Scutt
Follow David on Twitter @scutty
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Outlook: A Rates Trade Disguised as a Stock Market?
Australian bond futures have exhibited a far stronger relationship with the ASX 200 than Wall Street over recent months. Now both markets are displaying remarkably similar price structures.
GBP/AUD falling wedge points to bullish breakout risk ahead of RBA minutes
GBP/AUD is forming a potential bullish continuation pattern, with RBA minutes, Australian unemployment and Bank of England commentary among the catalysts that could spark a breakout.
Equities Weekly Outlook: Q3 Banks Earnings - JPM, GS, WFG
Q3 Earnings Season kicks off with JP Morgan, Goldman Sachs and Wells Fargo Group on October .

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.