




AUD/USD mulls 64c breakout, US yields hint at swing high post Fed
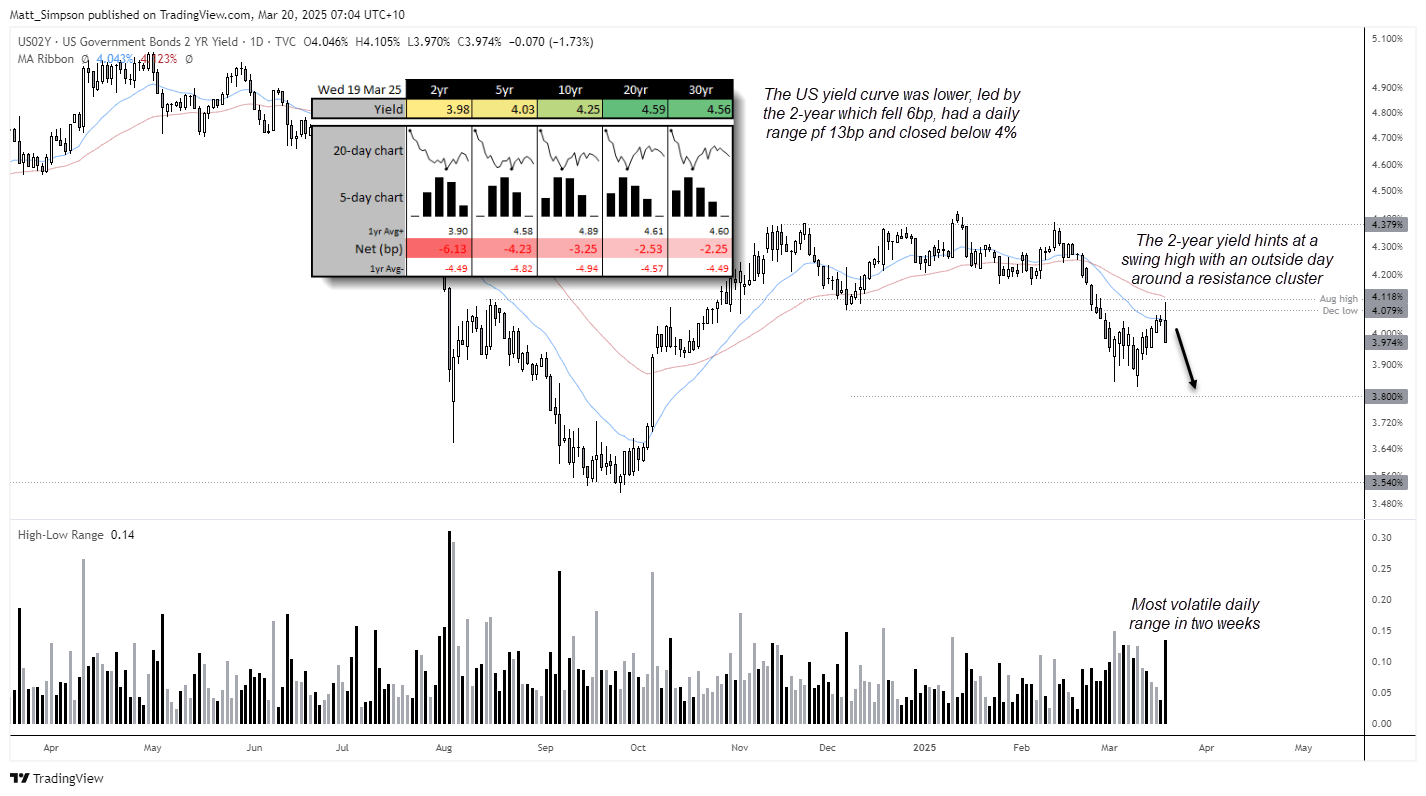
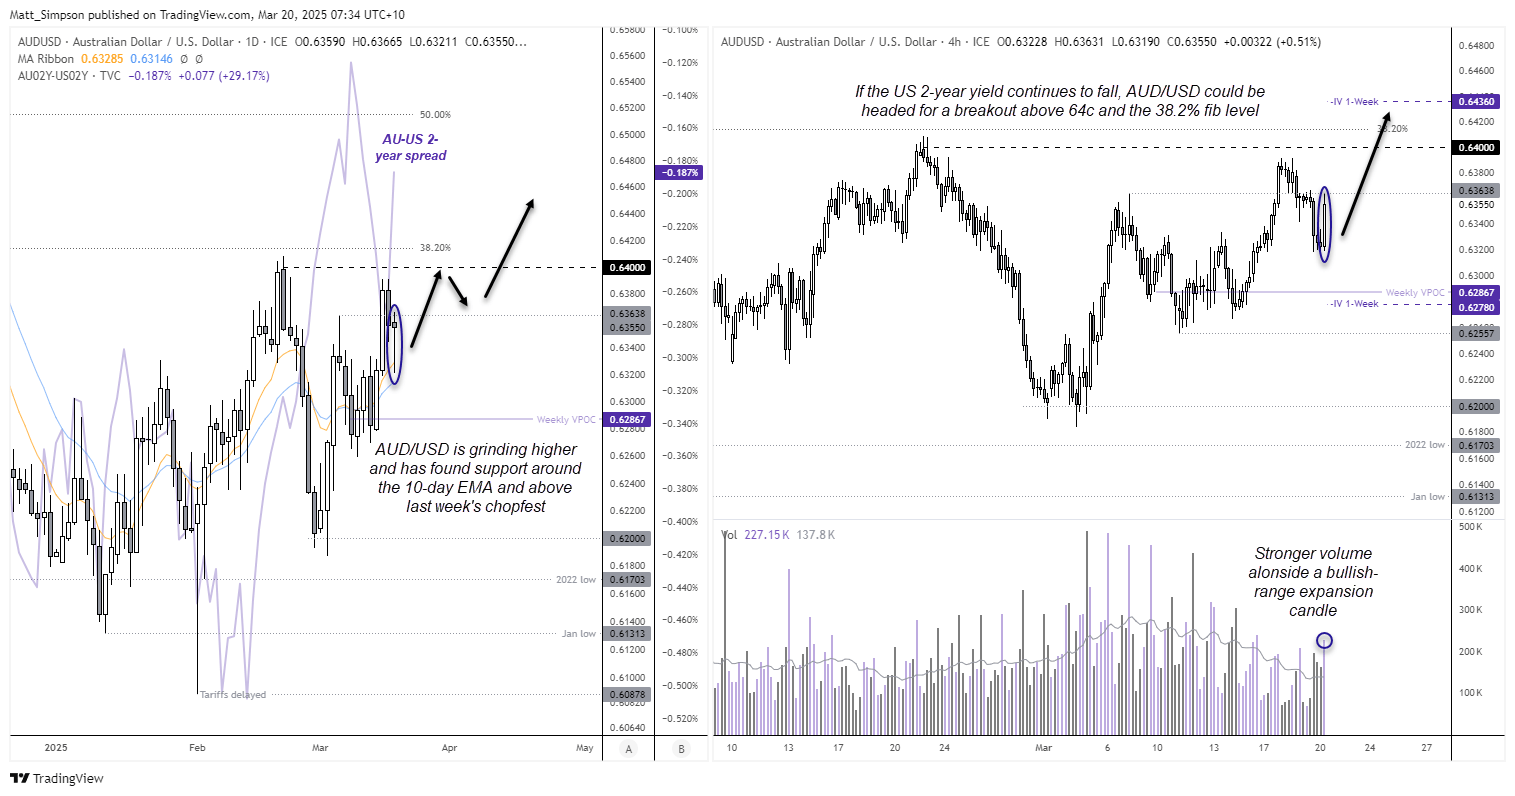
With US yields lower and hinting at a swing high, the relationship between AUD/USD and the AU-US 2-year spread appear to be back on talking terms. And that could bode well for AUD/USD bulls if US yields continue to fall in line with my bias.
Share this:
View related analysis:
- AUD/USD Forecast: FOMC, AU Jobs to Wake the Aussie Up From Its Lull?
- USD/JPY Hits Speed Bump at 150 Ahead of BOJ and FOMC, ASX to Open Lower
- Gold's Surge is Leaving Traders for Dust: Matt's 2-Minute Take
View related analysis:
While the Fed downgraded growth and upgraded their inflation forecast in light of Trump’s tariffs, they opted for a ‘wait and see’ approach regarding rates by keeping them at 3.9% for 2025, unchanged from their December forecasts. If anything, I felt they may have trimmed some easing out of the equation for this year, so from that angle it could be seen as dovish for the Fed to retain 50bp of cuts on the table.
- The Fed held rates steady at 4.25% - 4.5% as widely expected
- Lowered their 2025 growth outlook to 1.7% (down from 2.1%) and 2026 GDP to 1.8% (down from %)
- Core PCE for 2025 increased to 2.7% (2.5% prior)
- PCE increased to 2.8% (2.5% prior)
- Fed Funds rate unchanged at 3.9% for 2025 and 3.4% for 2026
- Balance sheet runoff to be slowed from April
Wall Street traders took the dovish tilt as good news, with the S&P 500, Nasdaq and Dow Jones were all up on the day. Although volatility was contained. Gold continued to a new high, as it doesn’t seem to know how to do much else these days.
It was the most volatile day for the 2-year yield in two weeks, with its bearish outside day spanned 13bp to close -6bp lower and back beneath 4%. The recovery from 3.83% stalled around the December low, August high and 50-day EMA, further adding to the case that a swing high on yields may have been seen.
AUD/USD technical analysis
While AUD/USD closed flat following the Fed meeting, its lower wick on the day shows demand around the 10 and 20-day EMAs, around last week’s choppy range. And as messy as price action may have been, it is grinding higher since its rebound from 62c.
Yield differentials appear to be making a comeback, with the AU-US 2-year rising alongside AUD/USD this week. The relationship between the two was weak heading into last week, but they appear to now be back on talking terms again.
It should be noted that the differential is rising due to a drop in US yields as opposed to a rise in AU yields, but the bearishness of the US 2-year chart does look appealing enough to at least support AUD/USD over the near term.
The 4-hour chart shows a strong bullish bar accompanied with rising volume, which suggest a swing low around 0.6320. Bulls could seek dips within that candles range in anticipation of a move up to 64c. But for a break above it strong enough to clear the 38.2% Fibonacci level, we likely need a strong AU employment report alongside a continued selloff on the US 2-year yield.
Economic events in focus (AEDT)
The Bank of England (BOE) are likely to become the third major central bank to hold rates this week. Sticky inflation gives little room for cuts, even if there are two dissenters within the ranks – which likely leaves it 7-2 in favour of no action today. Still, some estimate that there could be as many as three cuts this year.
You can read my thoughts on Australia’s employment situation in the AUD/USD outlook article linked above, but in a nutshell it is likely to remain robust and not allow RBA doves to jeer for an imminent RAB rate cut. If it comes in strong enough, it could help AUD/USD head for 64c again.
- 00:00 – Japanese Public Holiday (Vernal Equinox)
- 08:45 – New Zealand Q4 GDP
- 11:30 – Australian Employment (Feb)
- 12:00 – PBOC Loan Prime Rate
- 18:00 – UK Earnings, Claimant Count, Employment Change
- 19:30 – SNB Interest Rate Decision (25bp cut expected)
- 23:00 – BOE Interest Rate Decision, MPC Votes (No Change Expected)
- 23:30 – BOE Governor Bailey Speaks
- 23:30 – US Jobless Claims, Philly Fed Manufacturing
ASX 200 at a glance
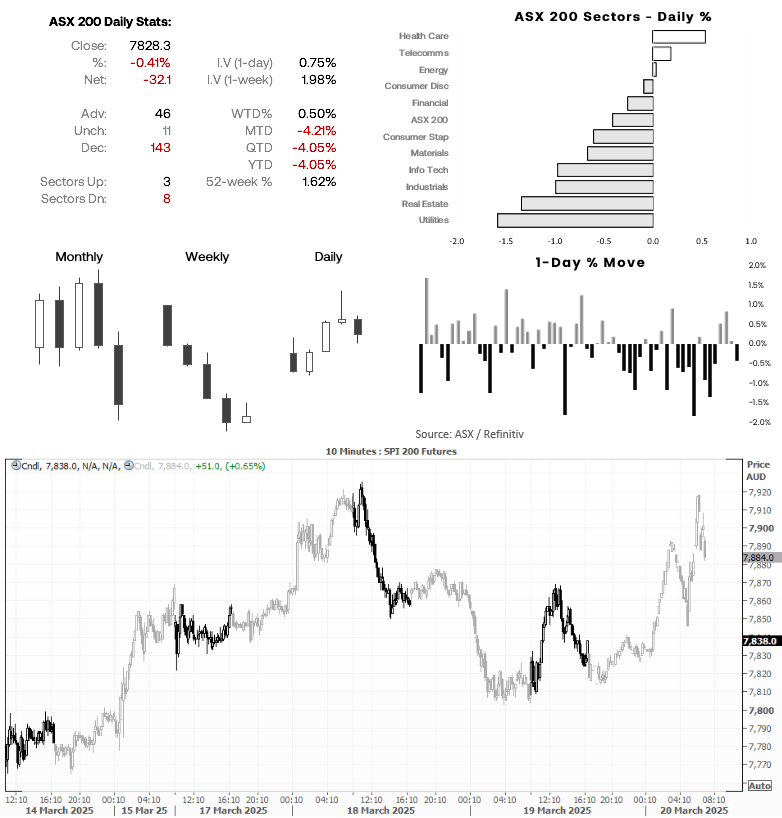
- The ASX 200 snapped a 3-day winning streak,
- Info tech is the weakest the 10 ASX sectors this past four weeks, down -19.3% while utilities is the only ASX sector to gain at 4%
- The bounce on Wal Street helped ASX 200 (SPI 200) futures rise 0.5% overnight, which points to a positive open for the ASX cash index today
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Analysis: Resilient U.S. Labor Market Continues to Pressure XAU/USD
Recent trading sessions have not been particularly favorable for gold in the short term. XAU/USD has fallen nearly 2.5% over the last three sessions, reflecting that selling pressure is once again gaining relevance and that the metal continues to struggle to regain momentum.
US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.

Nasdaq 100 forecast: Stocks rebound but AI concerns linger
The Nasdaq 100 was finding some support at 28,000 after recent sell-off amid concerns about the AI trade. Even with oscillators oversold, the risk to the near-term forecast is tilted to the downside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.