




AUD/USD, ASX 200 Analysis: Market Brief - 30th May 2023
Whilst the ASX posted a strong gain yesterday, it seems the debt-ceiling deal has been priced in, and AUD/USD may have risen for a second day but we're seeking a swing trade short opportunity.
Share this:

Market summary
- US and UK stock markets were closed yesterday and some futures markets had limited trading hours due to the 3-day weekend
- The debt ceiling deal is ready to make its way over to congress for the required vote to officially get it over the line
- Both Biden and McCarty claim to have enough votes to seal the deal, but the hurdle must be cleared for them to successfully kick the can down the road
- Some hard-right Republicans were quick to hit the wires and push back and vowed to block the deal, leaving an air of uncertainty over the deal
- US index futures posted modest gains in cautiously optimistic trade, with the growing realisation that it simply changes (but not solves) the problem and that they’ll likely have another Fed hike to contend with in June
- China has rejected a US request for defence chiefs to meet on the side lines at an annual security forum in Singapore this weekend
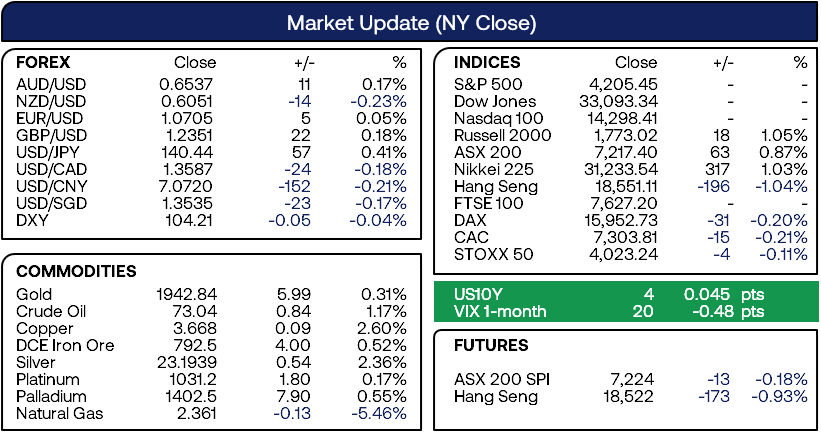
- The US dollar rally – fuelled by Fed-hike bets and apparent debt-ceiling deal – took a pause in low-liquidity trade.
- This allowed AUD/USD to retrace higher for a second day and USD/JPY pull back from its 6-month high but held above 140
- Meanwhile, EUR/USD remains locked near last week’s lows as it eyes a potential break below 1.0700 (but the longer it fails to do so, the greater the odds of a countertrend bounce)

Events in focus (AEDT):
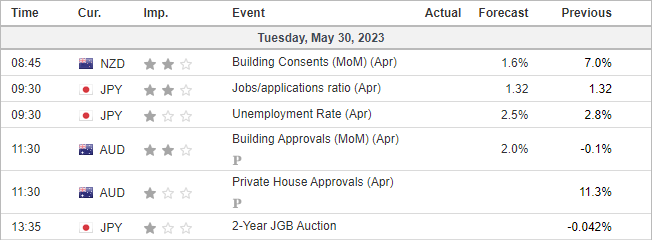
- 09:30 – Japan’s employment report
- 11:30 – Australian building permits
- 19:00 – Eurozone business and consumer survey, consumer inflation expectation
ASX 200 at a glance:
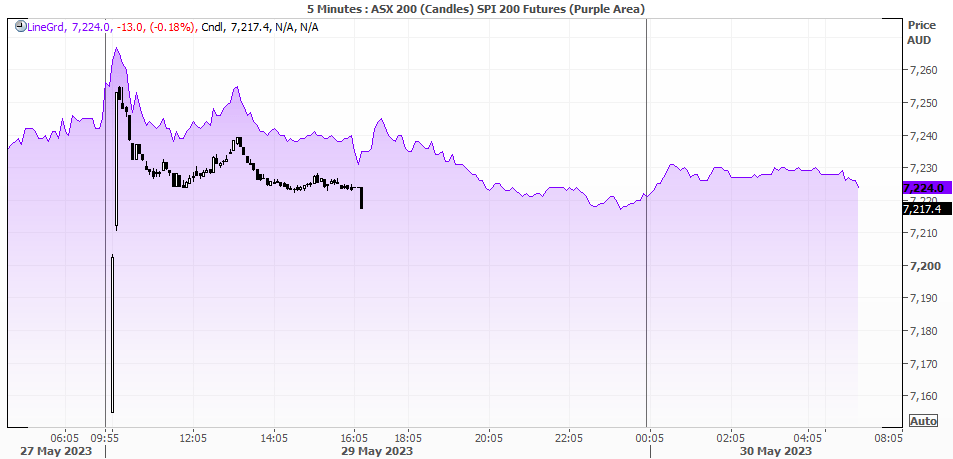
Close: 7217.4 (0.71%)
Daily trading volume: 502.6 mn
138 stocks advanced
17 stocks were unchanged
45 stocks declined
- The ASX enjoyed its most bullish day in 7 weeks
- However, prices jumped to the high of the day at the open then drifted lower throughout the day as debt-ceiling news was already priced in
- A daily shooting star formed on the IT and communication sectors to warn of trend exhaustion over the near-term
- A potential bear flag is forming on the daily chart of the consumer discretionary sector
- SPI futures are down -0.18%, pointing towards a slightly soft open
AUD/USD 4-hour chart:
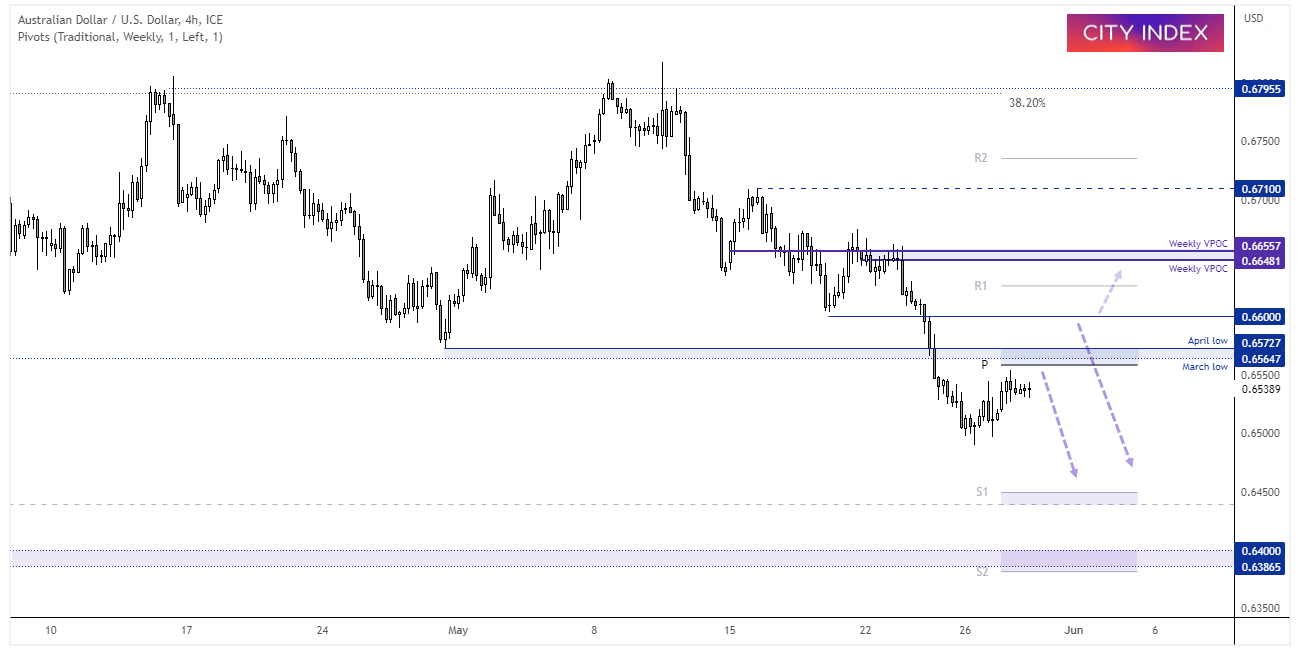

The Aussie retraced against its bearish trend for a second day, during low-liquidity trade. A bearish engulfing week saw it close to a fresh YTD low, so a retracement against that move seems healthy, and may provide another opportunity for bears to re-enter at or around resistance levels. For today, we’re looking for evidence of a swing high within the 0.6500 – 0.6572 range, which includes the weekly pivot, March and April low. Should prices continue to rise, 0.6600 is the next line of defence for bears – a break above which could see prices return towards the two weekly VPOC’s around 0.6650.
Asia Data Calendar (AEDT):
Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.