



Crude Oil, Indices Price Outlook: Negotiations vs Hormuz Risks
Crude oil, indices price outlook: Negotiations and Hormuz risks are supporting rebounds across both crude oil and US indices, as the US, Iran, and Israel continue to search for a resolution to the conflict. The US CPI release today is another key catalyst, reflecting the inflationary impact of ongoing tensions.
Share this:
Negotiations and Hormuz risks remain central to market direction, supporting rebounds across crude oil and US indices. At the same time, today’s US CPI print is expected to reflect persistent inflation pressures, driven by rising energy costs and supply disruptions linked to the Middle East conflict.
- The S&P 500 and Dow Jones are holding rebounds of over 8% from yearly lows, currently testing the 6,830 and 48,000 resistance levels respectively
- Nasdaq is rebounding over 10% from yearly lows, approaching the 25,200 resistance level
- Crude oil has rebounded over 10% from the recent $85 low, holding above the $90 threshold
US indices are maintaining their recovery, supported by constructive technical signals while testing critical resistance levels. This comes as Middle East negotiations fluctuate between optimism and uncertainty, with ongoing risks tied to Hormuz disruption and its implications for global supply chains, energy prices, and inflation.
In crude oil markets, renewed rhetoric around Hormuz risks has pushed prices higher by more than 10%, reinforcing inflationary pressures already visible globally, particularly in fuel and energy costs. This keeps the risk premium elevated and places strong focus on today’s US CPI data.
Today’s US CPI Expectations
- Core CPI (m/m): 0.2% → 0.3%
- CPI (m/m): 0.3% → 1.0%
- CPI (y/y): 2.4% → 3.4%
A reading in line with or above these expectations would reinforce upside risks for the US dollar, while increasing downside pressure on US indices and precious metals, particularly as elevated energy prices and higher insurance premiums linked to Hormuz disruptions persist.
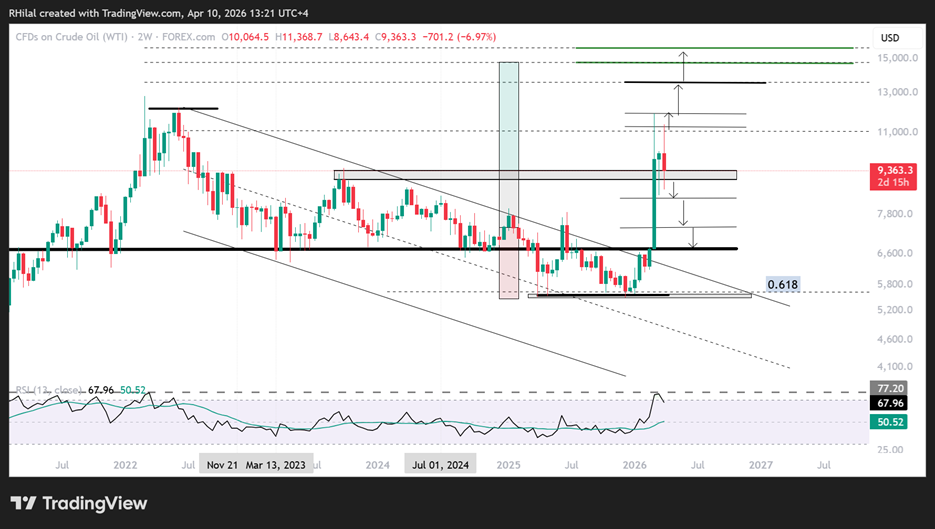
Crude Oil Price Outlook: 2 Week Time Frame – Log Scale
Source: Trading view
Crude oil price action can be divided into three key zones:
Upper range (strength continuation):
Price remains above the 2023 highs, with weekly closes holding above the $88 zone. A move above $110 and $118 could open the path toward $135, $145, and the $157–160 range.
Middle range (stabilization zone):
A move below $84 may still see strong rejection from this level. However, a confirmed break could expose downside toward $82 and $74, aligning with previous Middle East conflict highs.
Lower range (extended weakness):
A weekly close below $74 could expose a move toward the $60 zone, signaling a return to broader consolidation aligned with policy normalization trends.
With prices heavily driven by headlines, it remains essential to confirm moves through higher time frame closes to avoid noise during ongoing negotiations.
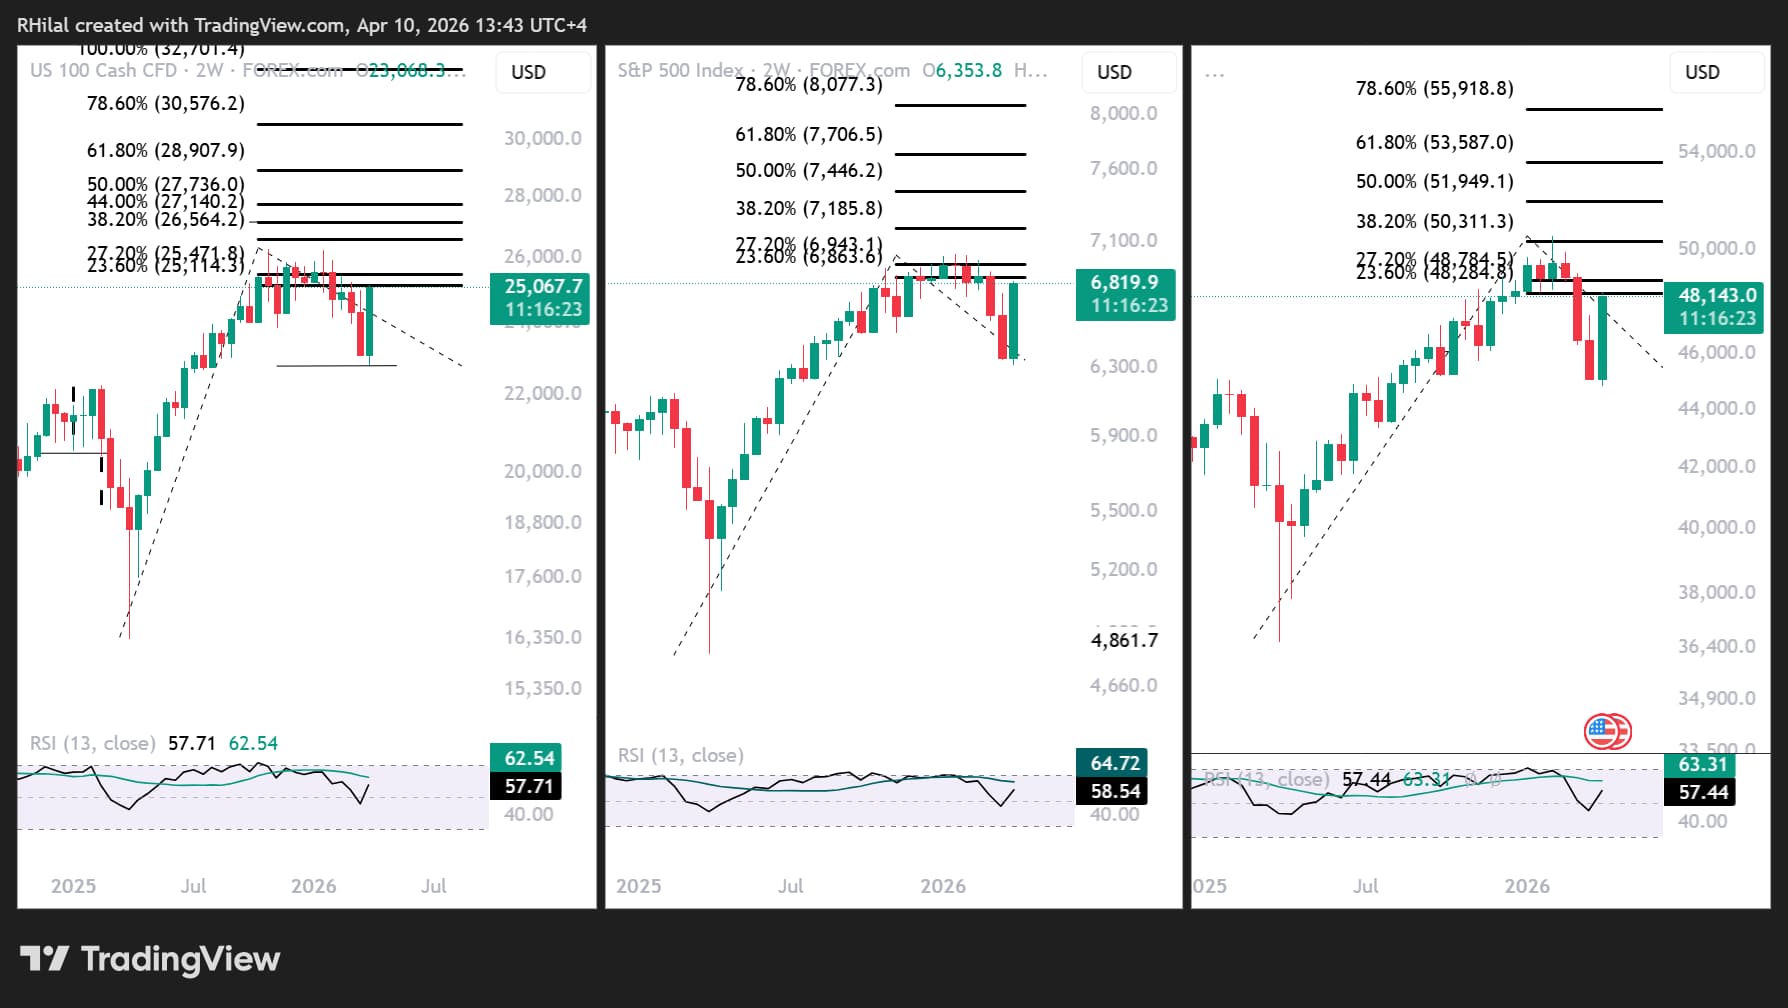
US Indices Price Outlook: 2-Week Time Frame – Log Scale
Source: Trading view
A similar structure is visible across Nasdaq, S&P 500, and Dow Jones, where recent rebounds are testing the 0.236 Fibonacci retracement of the move between April 2025 lows, January 2026 highs, and March 2026 lows.
This alignment suggests a constructive setup, where a break above resistance levels could reinforce market strength and risk appetite. Key levels include:
- Nasdaq: 25,000–25,500
- S&P 500: 6,830–6,940
- Dow Jones: 48,200–48,800
On the downside, pullback risks remain given inflation pressures tied to energy markets. If negotiations deteriorate or extend, key support levels to watch include:
- Nasdaq: 24,200–23,800
- S&P 500: 6,600–6,530
- Dow Jones: 46,800–46,200
In line with the broader outlook, headline-driven sentiment may continue to trigger sharp market swings. Higher time frame closes remain essential to confirm whether markets are entering a structural continuation or a reversal phase.
Written by Razan Hilal, CMT
Follow on X: @Rh_waves
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar, GBP/USD, USD/CAD, USD/CHF, Gold Weekly Technical Outlook 11 2 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

Nasdaq 100 Forecast: NDX rebounds as oil prices fall and ahead of Apple earnings
U.S. stock indices are moving higher on Monday as tech and AI-related stocks steady following a shocking October. The mood remains cautious following the AI wobble, with more tech earnings due this week, U.S. midterm elections and a full U.S. economic data calendar.

Have Markets Found a Turning Point Ahead of the Elections?
Fed rate-hike bets topping 70% have pressured markets, including precious metals and U.S. indices, toward key support levels. Could these levels signal a turning point ahead of the U.S. midterm elections?
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.