



EU indices up this morning TA focus on Chr Hansen
European stocks report | Associated British Foods | BMW | Chr Hansen...
Share this:
INDICES
Yesterday, European stocks were broadly lower. Germany's DAX 30 declined 0.4%, while both France's CAC 40 and the U.K.'s FTSE 100 were down 0.2% each.
EUROPE ADVANCE/DECLINE
55% of STOXX 600 constituents traded higher yesterday.
42% of the shares trade above their 20D MA vs 39% Tuesday (below the 20D moving average).
43% of the shares trade above their 200D MA vs 42% Tuesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.59pt to 30.13, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: none
3mths relative low: none
Europe Best 3 sectors
travel & leisure, energy, health care
Europe worst 3 sectors
automobiles & parts, basic resources, banks
INTEREST RATE
The 10yr Bund yield rose 2bps to -0.45% (below its 20D MA). The 2yr-10yr yield spread fell 3bps to -26bps (below its 20D MA).
ECONOMIC DATA
EC 10:00: May Unemployment Rate, exp.: 7.3%
EC 10:00: May PPI YoY, exp.: -4.5%
EC 10:00: May PPI MoM, exp.: -2%
FR 10:00: 10-Year OAT auction, exp.: 0.02%
UK 10:45: 5-Year Treasury Gilt auction, exp.: 0.04%
GE 13:00: Bundesbank Wuermeling speech
EC 14:00: ECB Mersch speech
UK 17:00: BoE Financial Stability Report
UK 17:00: BoE FPC Record
EC 18:00: ECB Schnabel speech
UK 00:01: Jun Gfk Consumer Confidence final, exp.: -36
MORNING TRADING
In Asian trading hours, EUR/USD held gains at 1.1258 and GBP/USD advanced further to 1.2483. USD/JPY edged up to 107.52. AUD/USD was little changed at 0.6916. This morning, official data showed that Australia recorded a trade surplus of 80.25 billion Australian dollars in May (90 billion Australian dollars surplus expected).
Spot gold remained subdued at $1,768 an ounce.
#UK-IRELAND#
Associated British Foods, a food processing and retailing company, posted a 3Q trading update: "Group revenue from continuing businesses for the 40 weeks ended 20 June 2020 was 13% lower than the same period last year at constant currency and 14% lower at actual exchange rates. (...) For the full year we continue to expect strong progress in the aggregate adjusted operating profit of our Sugar, Grocery, Agriculture and Ingredients businesses. (...) Nearly all Primark stores are now trading again and we estimate that, absent a significant number of further store closures, adjusted operating profit for Primark, excluding exceptional charges, will be in the range £300-350m for the full year compared to £913m reported for the last financial year."
Meggitt, an aerospace and defence company, issued a 2Q trading update: "Overall, we expect Group organic revenue to be c.30% lower in the second quarter. (...) Group revenue in the first half is expected to be c.15% lower than in H1 2019 on an organic basis, with growth in Defence more than offset by lower revenues in both civil aerospace and Energy."
Wizz Air, a low-cost airline company, reported that passenger number dropped 86.1% on year to 502,253 in June and the load factor fell to 52.2% from 95.0% in the prior-year period.
BHP Group, a giant metals miner, was downgraded to "hold" from "buy" at Deutsche Bank, while its peers Rio Tinto was upgraded to "buy" from "hold".
National Grid, an electricity and gas utility company, was downgraded to "hold" from "buy" at HSBC.
#GERMANY#
BMW, a vehicle manufacturer, announced that U.S. auto sales (including Mini) declined 38.3% on year to 56,245 units in 2Q.
Daimler, an automobile group, reported that U.S. vehicle sales dropped 16.4% on year to 71,130 units in 2Q.
Porsche, a sports cars maker, posted U.S. auto sales slid 20.0% on year to 12,192 units in 2Q.
Deutsche Bank, a banking group, was downgraded to "sell" from "hold" at Societe Generale.
#BENELUX#
Heineken, a Dutch brewing giant, was downgraded to "neutral" from "overweight" at JPMorgan.
#SCANDINAVIA - DENMARK#
Chr Hansen, a bioscience group, announced that 3Q net income grew 5% on year to 70 million euros and adjusted EBIT rose 5% to 97 million euros on revenue of 314 million euros, up 4% (+7% organic growth). From a chartist point of view, the stock is supported by a rising trendline drawn since March the 16th and its 20 and 50-period moving averages. Furthermore, the share is aiming the previous all-time high at 758DKK.

Source: GAIN Capital, TradingView
Assa Abloy, an access solutions provider, was upgraded to "buy" from "hold" at Deutsche Bank.
EX-DIVIDEND
National Grid:32p, Teleperformance: E2.4, Unibail-Rodamco-Westfield: E5.4
Yesterday, European stocks were broadly lower. Germany's DAX 30 declined 0.4%, while both France's CAC 40 and the U.K.'s FTSE 100 were down 0.2% each.
EUROPE ADVANCE/DECLINE
55% of STOXX 600 constituents traded higher yesterday.
42% of the shares trade above their 20D MA vs 39% Tuesday (below the 20D moving average).
43% of the shares trade above their 200D MA vs 42% Tuesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.59pt to 30.13, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: none
3mths relative low: none
Europe Best 3 sectors
travel & leisure, energy, health care
Europe worst 3 sectors
automobiles & parts, basic resources, banks
INTEREST RATE
The 10yr Bund yield rose 2bps to -0.45% (below its 20D MA). The 2yr-10yr yield spread fell 3bps to -26bps (below its 20D MA).
ECONOMIC DATA
EC 10:00: May Unemployment Rate, exp.: 7.3%
EC 10:00: May PPI YoY, exp.: -4.5%
EC 10:00: May PPI MoM, exp.: -2%
FR 10:00: 10-Year OAT auction, exp.: 0.02%
UK 10:45: 5-Year Treasury Gilt auction, exp.: 0.04%
GE 13:00: Bundesbank Wuermeling speech
EC 14:00: ECB Mersch speech
UK 17:00: BoE Financial Stability Report
UK 17:00: BoE FPC Record
EC 18:00: ECB Schnabel speech
UK 00:01: Jun Gfk Consumer Confidence final, exp.: -36
MORNING TRADING
In Asian trading hours, EUR/USD held gains at 1.1258 and GBP/USD advanced further to 1.2483. USD/JPY edged up to 107.52. AUD/USD was little changed at 0.6916. This morning, official data showed that Australia recorded a trade surplus of 80.25 billion Australian dollars in May (90 billion Australian dollars surplus expected).
Spot gold remained subdued at $1,768 an ounce.
#UK-IRELAND#
Associated British Foods, a food processing and retailing company, posted a 3Q trading update: "Group revenue from continuing businesses for the 40 weeks ended 20 June 2020 was 13% lower than the same period last year at constant currency and 14% lower at actual exchange rates. (...) For the full year we continue to expect strong progress in the aggregate adjusted operating profit of our Sugar, Grocery, Agriculture and Ingredients businesses. (...) Nearly all Primark stores are now trading again and we estimate that, absent a significant number of further store closures, adjusted operating profit for Primark, excluding exceptional charges, will be in the range £300-350m for the full year compared to £913m reported for the last financial year."
Meggitt, an aerospace and defence company, issued a 2Q trading update: "Overall, we expect Group organic revenue to be c.30% lower in the second quarter. (...) Group revenue in the first half is expected to be c.15% lower than in H1 2019 on an organic basis, with growth in Defence more than offset by lower revenues in both civil aerospace and Energy."
Wizz Air, a low-cost airline company, reported that passenger number dropped 86.1% on year to 502,253 in June and the load factor fell to 52.2% from 95.0% in the prior-year period.
BHP Group, a giant metals miner, was downgraded to "hold" from "buy" at Deutsche Bank, while its peers Rio Tinto was upgraded to "buy" from "hold".
National Grid, an electricity and gas utility company, was downgraded to "hold" from "buy" at HSBC.
#GERMANY#
BMW, a vehicle manufacturer, announced that U.S. auto sales (including Mini) declined 38.3% on year to 56,245 units in 2Q.
Daimler, an automobile group, reported that U.S. vehicle sales dropped 16.4% on year to 71,130 units in 2Q.
Porsche, a sports cars maker, posted U.S. auto sales slid 20.0% on year to 12,192 units in 2Q.
Deutsche Bank, a banking group, was downgraded to "sell" from "hold" at Societe Generale.
#BENELUX#
Heineken, a Dutch brewing giant, was downgraded to "neutral" from "overweight" at JPMorgan.
#SCANDINAVIA - DENMARK#
Chr Hansen, a bioscience group, announced that 3Q net income grew 5% on year to 70 million euros and adjusted EBIT rose 5% to 97 million euros on revenue of 314 million euros, up 4% (+7% organic growth). From a chartist point of view, the stock is supported by a rising trendline drawn since March the 16th and its 20 and 50-period moving averages. Furthermore, the share is aiming the previous all-time high at 758DKK.
Source: GAIN Capital, TradingView
Assa Abloy, an access solutions provider, was upgraded to "buy" from "hold" at Deutsche Bank.
EX-DIVIDEND
National Grid:32p, Teleperformance: E2.4, Unibail-Rodamco-Westfield: E5.4
INDICES
Yesterday, European stocks were broadly lower. Germany's DAX 30 declined 0.4%, while both France's CAC 40 and the U.K.'s FTSE 100 were down 0.2% each.
EUROPE ADVANCE/DECLINE
55% of STOXX 600 constituents traded higher yesterday.
42% of the shares trade above their 20D MA vs 39% Tuesday (below the 20D moving average).
43% of the shares trade above their 200D MA vs 42% Tuesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.59pt to 30.13, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: none
3mths relative low: none
Europe Best 3 sectors
travel & leisure, energy, health care
Europe worst 3 sectors
automobiles & parts, basic resources, banks
INTEREST RATE
The 10yr Bund yield rose 2bps to -0.45% (below its 20D MA). The 2yr-10yr yield spread fell 3bps to -26bps (below its 20D MA).
ECONOMIC DATA
EC 10:00: May Unemployment Rate, exp.: 7.3%
EC 10:00: May PPI YoY, exp.: -4.5%
EC 10:00: May PPI MoM, exp.: -2%
FR 10:00: 10-Year OAT auction, exp.: 0.02%
UK 10:45: 5-Year Treasury Gilt auction, exp.: 0.04%
GE 13:00: Bundesbank Wuermeling speech
EC 14:00: ECB Mersch speech
UK 17:00: BoE Financial Stability Report
UK 17:00: BoE FPC Record
EC 18:00: ECB Schnabel speech
UK 00:01: Jun Gfk Consumer Confidence final, exp.: -36
MORNING TRADING
In Asian trading hours, EUR/USD held gains at 1.1258 and GBP/USD advanced further to 1.2483. USD/JPY edged up to 107.52. AUD/USD was little changed at 0.6916. This morning, official data showed that Australia recorded a trade surplus of 80.25 billion Australian dollars in May (90 billion Australian dollars surplus expected).
Spot gold remained subdued at $1,768 an ounce.
#UK-IRELAND#
Associated British Foods, a food processing and retailing company, posted a 3Q trading update: "Group revenue from continuing businesses for the 40 weeks ended 20 June 2020 was 13% lower than the same period last year at constant currency and 14% lower at actual exchange rates. (...) For the full year we continue to expect strong progress in the aggregate adjusted operating profit of our Sugar, Grocery, Agriculture and Ingredients businesses. (...) Nearly all Primark stores are now trading again and we estimate that, absent a significant number of further store closures, adjusted operating profit for Primark, excluding exceptional charges, will be in the range £300-350m for the full year compared to £913m reported for the last financial year."
Meggitt, an aerospace and defence company, issued a 2Q trading update: "Overall, we expect Group organic revenue to be c.30% lower in the second quarter. (...) Group revenue in the first half is expected to be c.15% lower than in H1 2019 on an organic basis, with growth in Defence more than offset by lower revenues in both civil aerospace and Energy."
Wizz Air, a low-cost airline company, reported that passenger number dropped 86.1% on year to 502,253 in June and the load factor fell to 52.2% from 95.0% in the prior-year period.
BHP Group, a giant metals miner, was downgraded to "hold" from "buy" at Deutsche Bank, while its peers Rio Tinto was upgraded to "buy" from "hold".
National Grid, an electricity and gas utility company, was downgraded to "hold" from "buy" at HSBC.
#GERMANY#
BMW, a vehicle manufacturer, announced that U.S. auto sales (including Mini) declined 38.3% on year to 56,245 units in 2Q.
Daimler, an automobile group, reported that U.S. vehicle sales dropped 16.4% on year to 71,130 units in 2Q.
Porsche, a sports cars maker, posted U.S. auto sales slid 20.0% on year to 12,192 units in 2Q.
Deutsche Bank, a banking group, was downgraded to "sell" from "hold" at Societe Generale.
#BENELUX#
Heineken, a Dutch brewing giant, was downgraded to "neutral" from "overweight" at JPMorgan.
#SCANDINAVIA - DENMARK#
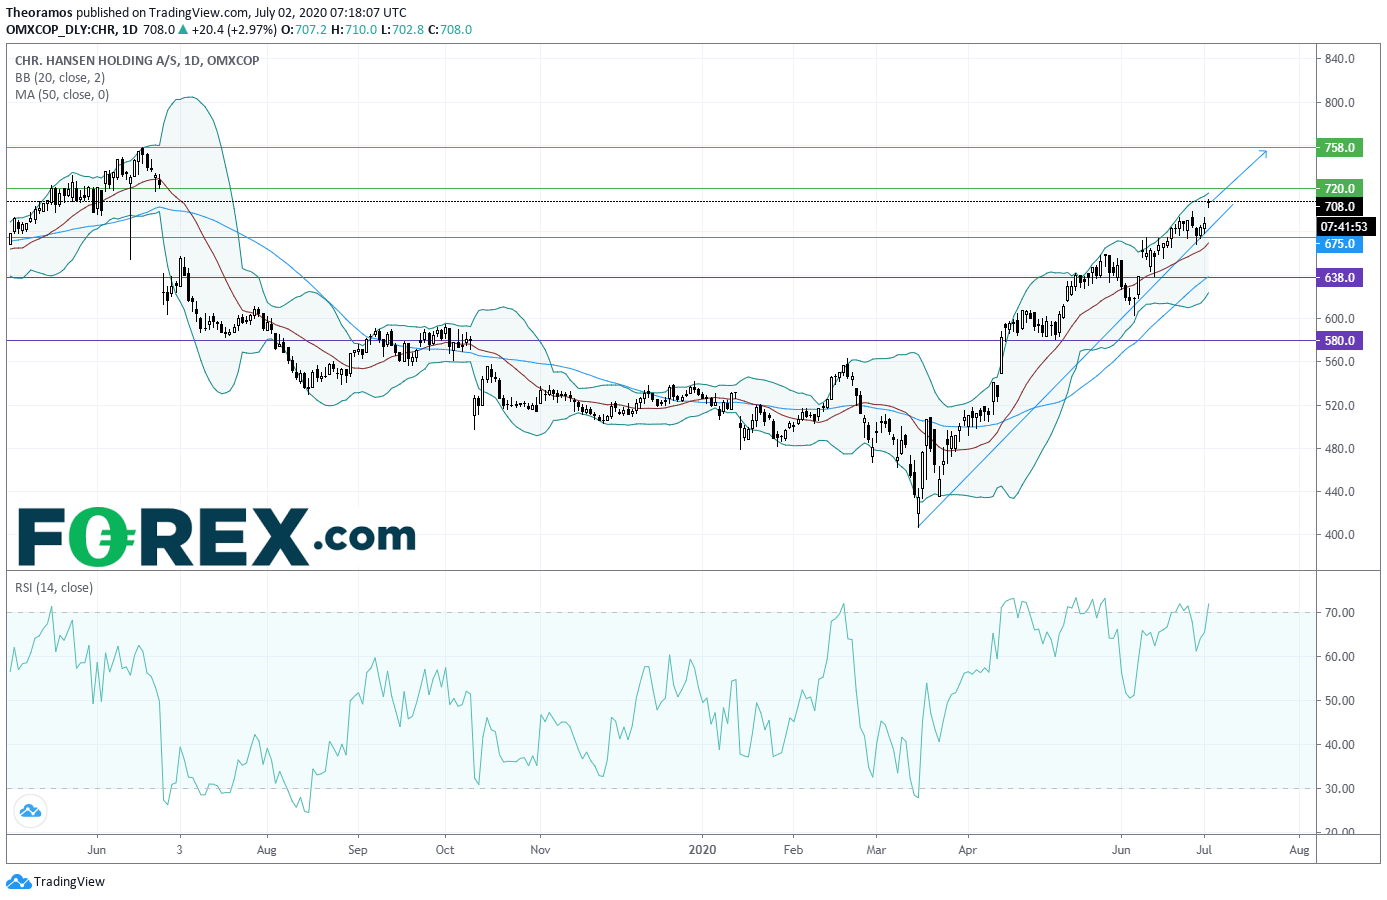
Chr Hansen, a bioscience group, announced that 3Q net income grew 5% on year to 70 million euros and adjusted EBIT rose 5% to 97 million euros on revenue of 314 million euros, up 4% (+7% organic growth). From a chartist point of view, the stock is supported by a rising trendline drawn since March the 16th and its 20 and 50-period moving averages. Furthermore, the share is aiming the previous all-time high at 758DKK.
Source: GAIN Capital, TradingView
Assa Abloy, an access solutions provider, was upgraded to "buy" from "hold" at Deutsche Bank.
EX-DIVIDEND
National Grid:32p, Teleperformance: E2.4, Unibail-Rodamco-Westfield: E5.4
Yesterday, European stocks were broadly lower. Germany's DAX 30 declined 0.4%, while both France's CAC 40 and the U.K.'s FTSE 100 were down 0.2% each.
EUROPE ADVANCE/DECLINE
55% of STOXX 600 constituents traded higher yesterday.
42% of the shares trade above their 20D MA vs 39% Tuesday (below the 20D moving average).
43% of the shares trade above their 200D MA vs 42% Tuesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.59pt to 30.13, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: none
3mths relative low: none
Europe Best 3 sectors
travel & leisure, energy, health care
Europe worst 3 sectors
automobiles & parts, basic resources, banks
INTEREST RATE
The 10yr Bund yield rose 2bps to -0.45% (below its 20D MA). The 2yr-10yr yield spread fell 3bps to -26bps (below its 20D MA).
ECONOMIC DATA
EC 10:00: May Unemployment Rate, exp.: 7.3%
EC 10:00: May PPI YoY, exp.: -4.5%
EC 10:00: May PPI MoM, exp.: -2%
FR 10:00: 10-Year OAT auction, exp.: 0.02%
UK 10:45: 5-Year Treasury Gilt auction, exp.: 0.04%
GE 13:00: Bundesbank Wuermeling speech
EC 14:00: ECB Mersch speech
UK 17:00: BoE Financial Stability Report
UK 17:00: BoE FPC Record
EC 18:00: ECB Schnabel speech
UK 00:01: Jun Gfk Consumer Confidence final, exp.: -36
MORNING TRADING
In Asian trading hours, EUR/USD held gains at 1.1258 and GBP/USD advanced further to 1.2483. USD/JPY edged up to 107.52. AUD/USD was little changed at 0.6916. This morning, official data showed that Australia recorded a trade surplus of 80.25 billion Australian dollars in May (90 billion Australian dollars surplus expected).
Spot gold remained subdued at $1,768 an ounce.
#UK-IRELAND#
Associated British Foods, a food processing and retailing company, posted a 3Q trading update: "Group revenue from continuing businesses for the 40 weeks ended 20 June 2020 was 13% lower than the same period last year at constant currency and 14% lower at actual exchange rates. (...) For the full year we continue to expect strong progress in the aggregate adjusted operating profit of our Sugar, Grocery, Agriculture and Ingredients businesses. (...) Nearly all Primark stores are now trading again and we estimate that, absent a significant number of further store closures, adjusted operating profit for Primark, excluding exceptional charges, will be in the range £300-350m for the full year compared to £913m reported for the last financial year."
Meggitt, an aerospace and defence company, issued a 2Q trading update: "Overall, we expect Group organic revenue to be c.30% lower in the second quarter. (...) Group revenue in the first half is expected to be c.15% lower than in H1 2019 on an organic basis, with growth in Defence more than offset by lower revenues in both civil aerospace and Energy."
Wizz Air, a low-cost airline company, reported that passenger number dropped 86.1% on year to 502,253 in June and the load factor fell to 52.2% from 95.0% in the prior-year period.
BHP Group, a giant metals miner, was downgraded to "hold" from "buy" at Deutsche Bank, while its peers Rio Tinto was upgraded to "buy" from "hold".
National Grid, an electricity and gas utility company, was downgraded to "hold" from "buy" at HSBC.
#GERMANY#
BMW, a vehicle manufacturer, announced that U.S. auto sales (including Mini) declined 38.3% on year to 56,245 units in 2Q.
Daimler, an automobile group, reported that U.S. vehicle sales dropped 16.4% on year to 71,130 units in 2Q.
Porsche, a sports cars maker, posted U.S. auto sales slid 20.0% on year to 12,192 units in 2Q.
Deutsche Bank, a banking group, was downgraded to "sell" from "hold" at Societe Generale.
#BENELUX#
Heineken, a Dutch brewing giant, was downgraded to "neutral" from "overweight" at JPMorgan.
#SCANDINAVIA - DENMARK#
Chr Hansen, a bioscience group, announced that 3Q net income grew 5% on year to 70 million euros and adjusted EBIT rose 5% to 97 million euros on revenue of 314 million euros, up 4% (+7% organic growth). From a chartist point of view, the stock is supported by a rising trendline drawn since March the 16th and its 20 and 50-period moving averages. Furthermore, the share is aiming the previous all-time high at 758DKK.
Source: GAIN Capital, TradingView
Assa Abloy, an access solutions provider, was upgraded to "buy" from "hold" at Deutsche Bank.
EX-DIVIDEND
National Grid:32p, Teleperformance: E2.4, Unibail-Rodamco-Westfield: E5.4
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
AUD/USD Analysis: What's Next for the Australian Dollar After the RBA Decision?
Recent trading sessions have reflected a more neutral tone around the Australian dollar. This can be seen in AUD/USD price action, which has posted moves of roughly 0.2% over the last two sessions without establishing a clear direction. Much of this lack of momentum is linked to expectations surrounding the next policy moves from both the Reserve Bank of Australia (RBA) and the Federal Reserve.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.