



Futures turn positive after Trump Softens on China | Markets Eyes Rebound
European equities opened firmer on Monday as Trump’s softer weekend comments toward China eased trade fears and lifted sentiment after last week’s sharp sell-off. Gold hit a new record above $4,000/oz as safe-haven demand persisted, while oil rebounded modestly. Investors focus on the upcoming earnings deluge and Powell’s Tuesday speech amid the US shutdown. Asian trade was mixed, with China’s exports surprising to the upside and Japan closed for a holiday.
Share this:

Monday, 13 October 2025
Market Overview
- Europe: Equity futures point to a modest rebound following last Friday’s heavy sell-off. Euro Stoxx 50 futures +0.3%, after cash markets closed down –1.7% on trade fears.
- APAC: Regional equities started lower on Friday’s tariff shock but pared losses after Trump’s conciliatory weekend remarks (“Don’t worry about China, it will all be fine!”). Japan closed for holiday; China, Hong Kong, South Korea partially shut.
- US futures: Recover modestly after sharp Friday declines (SPX –2.7%, NDX –3.5%, DJI –1.9%).
- Upcoming data: German WPI (Sep), OPEC MOMR, and speakers from BoE, Fed, and RBA.
- Holidays: US Columbus Day (bond market shut), Canadian Thanksgiving.
- US CPI: BLS confirms September CPI to be published Oct 24, 08:30 EDT / 13:30 BST.
Big Earnings week starting again
Big big week for companies especially with anticipated lowering of interest rates – so J Powells speech will be especially important on Tuesday.
Tuesday 14th: Premarket: J P Morgan Chase & Co, Johnson & Johnson, Wells Fargo & Company, Goldman Sachs Group, Inc, Citigroup.
Wednesday 15th: Premarket: ASML Holdings N.V, Bank of America Corporation, Morgan Stanley, Abbott Laboratories.
Thursday 16th: Premarket: Taiwan Semiconductor Manufacturing Company Ltd, The Charles Schwab Corporation
Friday 17th: Premarket: American Express Company, State Street Corporation, Truist Financial Corporation.
Trade & Tariffs
- US–China tensions:
- Trump announced 100% tariffs on Chinese imports effective Nov 1, plus export controls on critical software.
- Over the weekend, softened tone via Truth Social, signalling willingness to cooperate with Beijing.
- China’s response:
- Commerce Ministry labelled tariffs as “double standards” and said it “will not be afraid to fight.”
- Defended rare earth export controls as legitimate; stressed they are not a full export ban.
- Introduced special port fees on US vessels as countermeasures.
- Other trade headlines:
- US considering tariff rebates, no decision yet.
- EU planning 50% steel import tariffs above 2013 quota (FT).
- US rejects UN global carbon tax proposal, considering probes and sanctions on supporting nations.
- Canada drafting new industrial strategy to offset US tariffs; exploring new markets.
- Switzerland–China to accelerate FTA upgrade.
Macro & Policy
- Fed outlook:
- Musalem (2025 voter): inflation still high, labour cooling; open to another insurance rate cut but warned of limited room for easing.
- Industrial Production data delayed due to shutdown; data gaps persist.
- Shutdown impact: Federal layoffs in the thousands; administration diverted funds to pay troops.
- US domestic:
- Trump warned “Democrat-oriented” layoffs; reiterated shutdown blame.
- VP Vance confirmed Justice Department not following Trump orders to prosecute opponents.
- New research (FT): capital rule easing could unlock $2.6tn in US bank lending capacity.
APAC Session
- Japan: Closed for holiday.
- ASX 200: Lower on tech, energy, and telecom weakness; gold miners rallied as spot gold rebounded above $4,000/oz, a new record.
- KOSPI: Down; Samsung Electronics hit with USD 445.5m patent verdict.
- China: Exports +8.3% YoY (exp. +6%), Imports +7.4% YoY (exp. +1.5%); trade surplus $90.45bn.
- FX:
- USD steady (DXY flat) amid mixed tone and thin trading.
- EUR rangebound; France political reshuffle (Lecornu reappointed PM).
- GBP steady near highs; reports of £7bn pension tax raid in upcoming UK Budget.
- JPY slightly weaker; USD/JPY >150 with BoJ holiday.
- AUD/NZD firmer on commodity rebound.
- Rates:
- USTs little changed (US bond market closed).
- Bunds slightly lower ahead of German WPI.
- JGB auction saw strong demand despite earlier yield rise.
- Commodities:
- Oil: Modest rebound post Friday’s 3–4% drop; Brent regains some ground.
- Gold: Record >$4,000/oz, Goldman Sachs lifts Dec-2026 forecast to $4,900/oz.
- Copper: Firm after Trump’s softer China tone; risk appetite improving.
- Crypto: Bitcoin volatile, partially rebounding after prior week’s “crypto meltdown.”
EU: DAX Technical Analysis
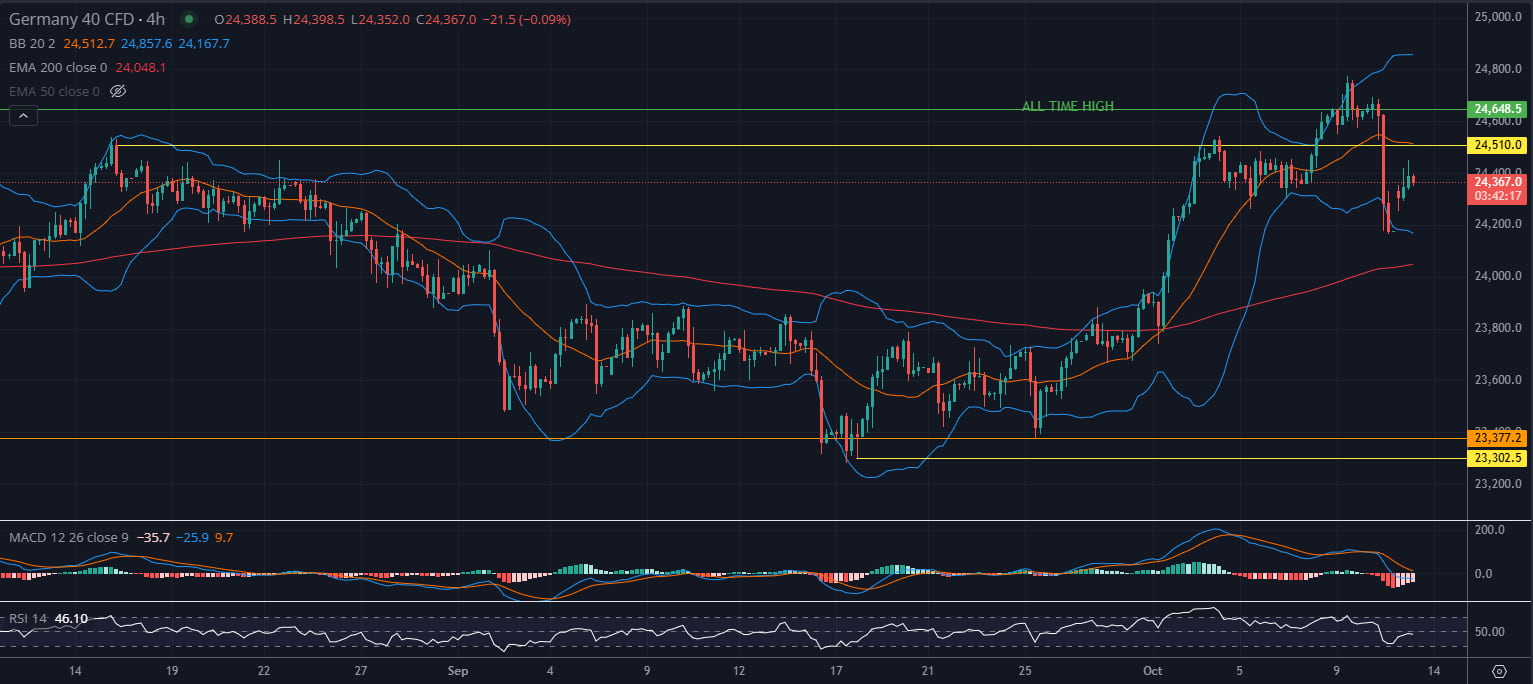
The Germany 40 (4H) has pulled back after failing to hold above the 24,510 breakout level, slipping toward the 24,300–24,350 zone. Price is now hovering near the 200 EMA (24,050), which is acting as dynamic support. The RSI (46) shows neutral-to-weak momentum, while the MACD remains below the signal line, confirming short-term bearish pressure but not a breakdown.
Structurally, the uptrend remains intact as long as price holds above 24,000. Resistance is seen at 24,510, followed by the all-time high (24,648). A recovery above 24,510 would reinstate the bullish bias, while a decisive break below the 200 EMA could open room toward 23,900–23,800. Tone: corrective pullback within a broader uptrend.
Geopolitics
Middle East
- Egypt Summit: Over 20 world leaders (including Trump, Starmer, Macron, Costa) to attend Gaza peace signing.
- Hostage release: Israel expects 20 hostages freed early Monday; Palestinian prisoners to follow.
- Iran: Rejects joining Abraham Accords, calls idea “wishful thinking”; open to “fair and balanced” US nuclear proposal via mediators.
Russia–Ukraine
- Trump: Considering sending Tomahawk missiles to Ukraine but “not looking for escalation.”
- Zelensky: Spoke with Trump, thanked US for support; said missiles would target military sites only.
- Russia: Massive drone/missile barrage; Ukraine hit energy infrastructure.
- EU: Agreed to restrict movement of Russian diplomats amid sabotage concerns.
Other global
- Pakistan–Afghanistan: Deadly border clashes (22 Pakistani troops, >200 Afghan deaths).
- Philippines–China: Naval collision near Sandy Cay; both sides blame each other.
- North Korea–Russia: Kim and Medvedev discussed deeper military cooperation; DPRK vows to “destroy all threats.”
- EU–UK:
- UK PM Starmer revising planning bill and preparing tax rises & spending cuts for November Budget.
- France: Lecornu confirms government reformation; Roland Lescure stays Finance Minister.
- ECB’s Vujcic: “Rates are at a good place,” signalling stable policy stance.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

dax-record-high-banks-cyclicals-election-relief-rally-european-stocks
The DAX has surged to fresh record highs as investors continue to rotate into banks, industrials and cyclical stocks following the US midterm elections. Falling bond yields, lower oil prices and improving sentiment have supported risk appetite across Europe, helping the index move decisively above 26,000. The focus now shifts from political relief to whether earnings and macroeconomic data can justify the rally's next leg higher.
dax-26000-bayer-siemens-energy-sektorrotation-us-zwischenwahlen
The DAX briefly reclaimed the 26,000 level as investors used post-election weakness as an opportunity to rotate into industrial, healthcare and energy-transition leaders. Strong gains in Bayer, Siemens and Siemens Energy helped offset weakness in consumer and AI-related growth stocks. With bond yields easing and the dollar weakening after the US midterm elections, investors are increasingly focusing on earnings quality, visible demand and infrastructure-related growth themes.
DAX Tests 26,000 as Markets Await AMD and US Election Results
The DAX remains close to 26,000 points after extending its recovery, but the market's attention is shifting away from geopolitics and back toward earnings, economic data and US politics. Reports from Bayer, Lufthansa and Fresenius Medical Care highlight a market increasingly rewarding profit growth while punishing weak guidance. With US midterm elections, JOLTS job openings and AMD earnings on today's agenda, the next move in equities may depend less on technicals and more on whether earnings and economic data justify current valuations.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.