



European Open: EUR/USD and EUR/GBP in focus for eurozone CPI
Both EUR/GBP and EUR/GBP are hugging various pivot points ahead of the open, but whichever way they break initially our bias is for a break to new lows.
Share this:

Asian Indices:
- Australia's ASX 200 index fell by -24.5 points (-0.33%) and currently trades at 7,290.00
- Japan's Nikkei 225 index has fallen by -368.78 points (-0.0134%) and currently trades at 27,104.32
- Hong Kong's Hang Seng index has risen by 110.95 points (0.54%) and currently trades at 20,534.79
- China's A50 Index has fallen by 0.02 points (0%) and currently trades at 13,561.60
UK and Europe:
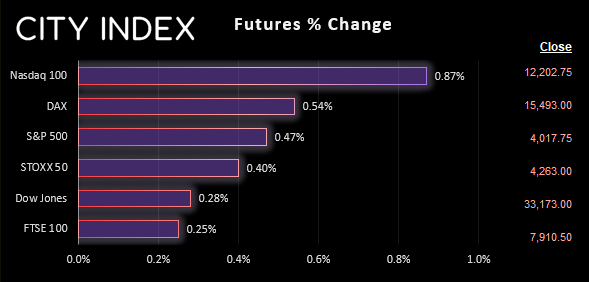
- UK's FTSE 100 futures are currently up 20 points (0.25%), the cash market is currently estimated to open at 7,950.63
- Euro STOXX 50 futures are currently up 18 points (0.42%), the cash market is currently estimated to open at 4,260.88
- Germany's DAX futures are currently up 83 points (0.54%), the cash market is currently estimated to open at 15,482.89
US Futures:
- DJI futures are currently up 95 points (0.29%)
- S&P 500 futures are currently up 105.5 points (0.87%)
- Nasdaq 100 futures are currently up 18.5 points (0.46%)

- Trading volumes were lower overnight due to the public holiday celebrating the Emperor’s Birthday in Japan
- AUD was the strongest major overnight following a positive Capex (capital expenditure) report
- Capex rose 2.2% q/q, above 0.8% expected and rose 3.6% y/y. Volumes were also their highest since September 2015 and firms had a positive outlook for financial year 23-24
- Asian equities were mostly lower overnight thanks to the weak lead from Wall Street, with Japan’s equity markets leading the way lower
- Oil prices rose slightly from their 2-week low, but stirring geopolitical tensions and the threat of hawkish central banks continue to weigh on demand outlook and therefore prices
- Gold has corrected slightly higher overnight, but our bias remains bearish and for an eventual move down through 1820 to 1800
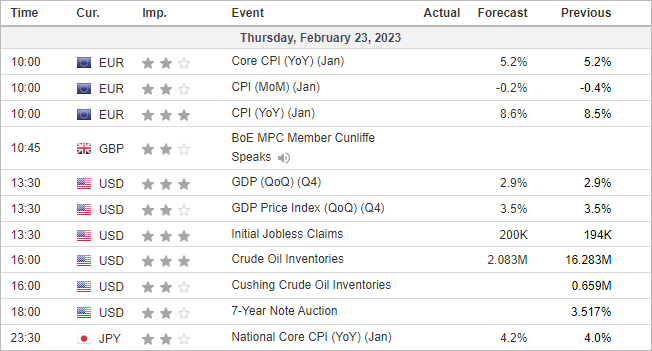
The main event today is euro area inflation data at 10:00 GMT. CPI is expected to contract by -0.2% m/m, or 8.6% y/y whilst core CPI is expected to remain steady at 5.2% y/y. Given the stronger business sentiment reads across the week, a soft inflation report would be welcomed and likely weigh on the euro, whilst a stronger inflation report simply keeps the pressure on the ECB to hike more aggressively and likely send the euro higher.
Keeping in mind how markets reacted following the extremely hot NFP report this month, it’s worth keeping an eye on initial jobless claims to see if there’s any large deviations. For example, a significantly lower number than 200k would likely be bullish for the US dollar and traders increase bets of a 50bp Fed hike in March. It may be a nothing burger, but it warrants a look.
The final Q4 GDP report for the US is released at 13:30 GMT, although it’s unlikely to be a market move due to its large lag (and it being the final revision), unless we see a significant revision. Even then. It’s backwards looking.
At 09:30 GMT, BOE’s MPC member Catherine Mann speaks at the Resolution Foundation on “The results of rising rates: Expectations, lags and the transmission of monetary policy”
EUR/USD 1-hour chart
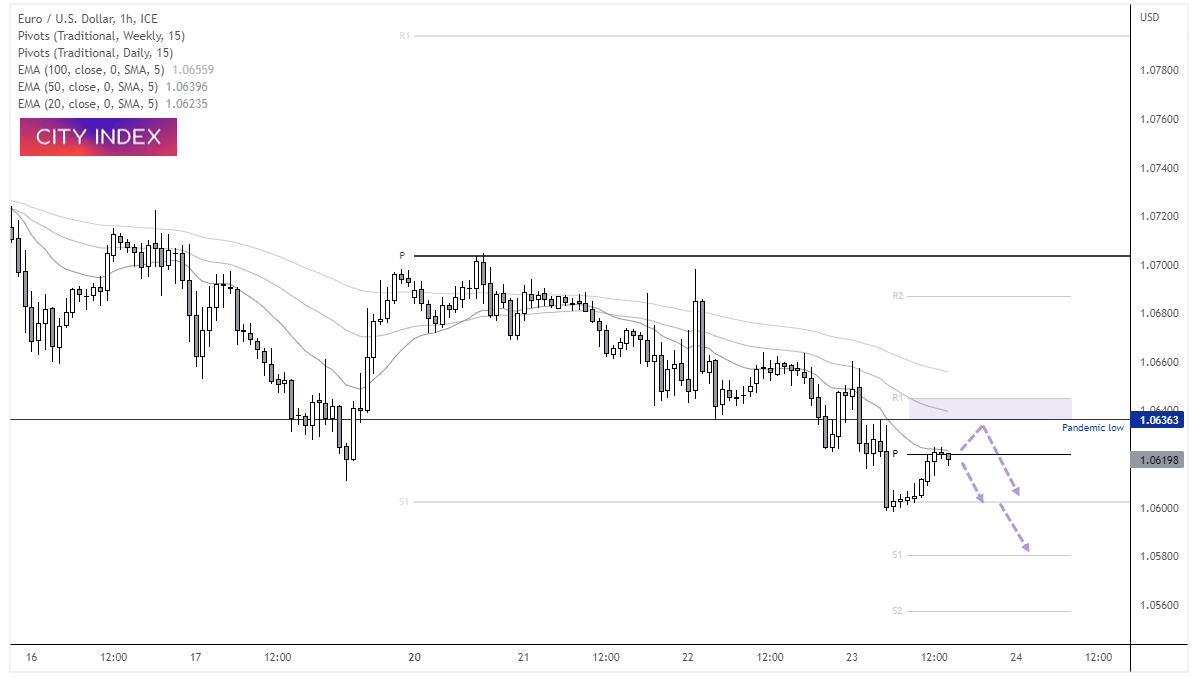
The euro remains within a downtrend on the 1-hour chart, with prices remaining beneath the 20, 50 and 100-bar EMA’s. That said, support was found at the weekly S1 yesterday and a countertrend move has since pulled back to the daily pivot point. It’s a bit of a coin flip, as to how prices will interact around the daily pivot at the market open, but given the bearish trend and that prices remain below the ‘pandemic low’, today’s bias is bearish and we’d prefer to seek short opportunities below the daily R1 pivot / pandemic low zone.
EUR/GBP 4-hour chart:
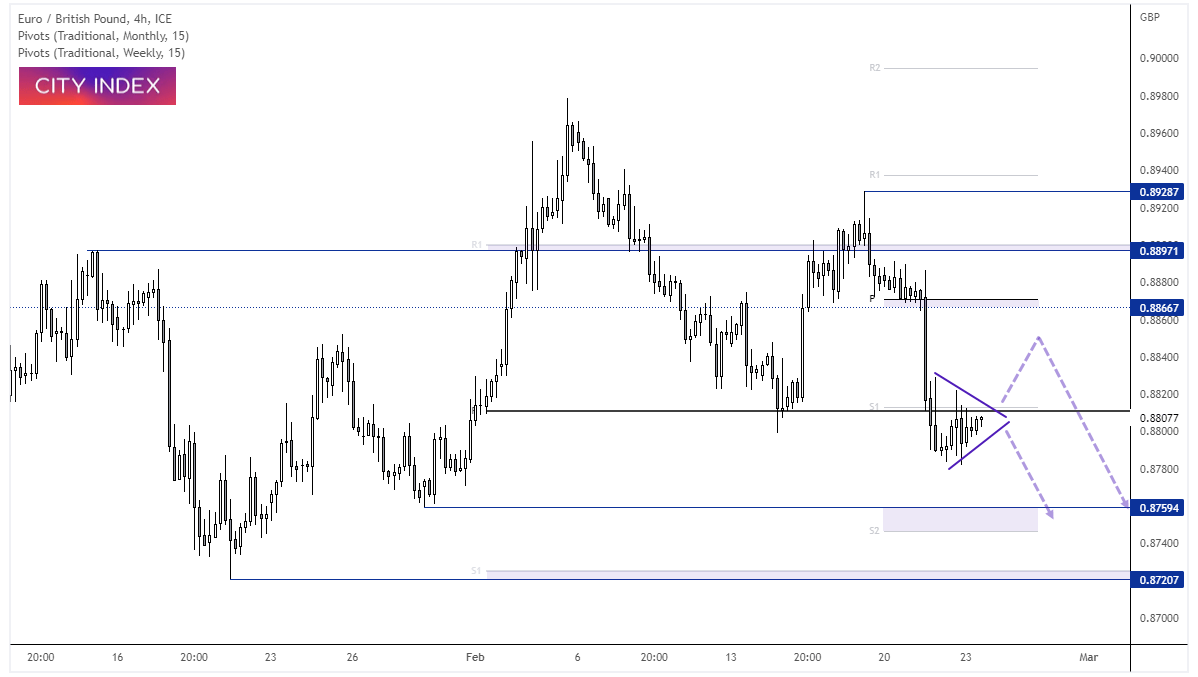
EUR/GBP is consolidating near its 3-week lows, which suggests we’re approaching a bout of volatility. As the trend is hard to decipher, we’re open to an initial breakout from the consolidation in either direction, but the bias overall is for a move down to the weekly S2 / 0.8760 zone. Clearly, today’s inflation report could rive the direction of the initial breakout from compression.
Economic events up next (Times in GMT)

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.


USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.