


FOMC meeting preview: 100bps unlikely, but longer rate hike path in play
In our view, the possibility of a 100bps rate hike is overblown...but that doesn't mean the Fed won't come off as hawkish.
Share this:

When is the FOMC monetary policy meeting?
The FOMC’s September monetary policy meeting will conclude at 14:00 ET on Wednesday, September 21. Fed Chairman Jerome Powell’s accompanying press conference will begin at 14:30 ET.
What are traders expecting from the Fed meeting?
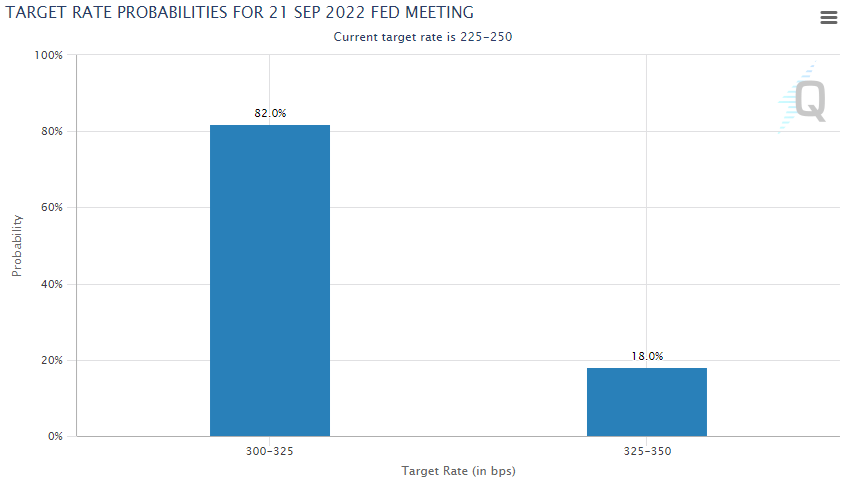
According to the CME’s FedWatch tool, traders and economists are pricing in about 84% chance of a 75bps (0.75%) interest rate increase to the 3.00-3.25% range, with an outside shot (~16%) of a full 100bps (1.00%) rate hike.
Source: CME FedWatch
FOMC meeting preview
It seems like a lifetime ago, but at this time last month, traders were thinking the Fed was more likely to raise interest rates by just 50bps (0.50%) in its September monetary policy meeting. However, after a hawkish address from Fed Chairman Powell at Jackson Hole, another solid NFP report, and a much hotter-than-expected CPI report, the market has completely thrown out any possibility of a mere 50bps rate hike and even started to price in an outside chance of a full 100bps (1.00%) rise.
In our view, the possibility of a 100bps rate hike is overblown. Lost amongst traders’ handwringing over the Fed’s clear focus on defeating inflation and the hotter-than-anticipated CPI reading is the fact that inflation is still declining relatively sharply. After all, the year-over-year CPI inflation rate has fallen from 9.1% to 8.5% to 8.3% over the last two months.
While the Fed would certainly have preferred to see a rate closer to 8.0% last month, other measures of inflation are clearly falling rapidly, suggesting that the hotter-than-expected CPI reading may be a one-off outlier. For example, the recently-released New York Fed survey showed that 1-year inflation expectations fell to 5.7% (from 6.2%) previously, and the survey’s average 3-year expectation for inflation fell from 3.2% to 2.8%, within shouting distance of the Fed’s long-term target near 2%. In other words, there is no evidence that we are entering a self-fulfilling cycle of rising prices; if anything, the evidence suggests that consumers and businesses expect price pressures to keep dropping in the coming quarters.
Instead of pointing to a 100bps rate hike this month, the stubborn inflation readings of late suggest that the central bank may be forced to raise interest rates for longer, perhaps into the first half of 2023, rather than pausing the current tightening cycle at the end of this year. A month ago, traders were pricing the peak interest rate for this cycle around 4.00% in January; now the market expects rates to peak closer to 4.50-4.75% in Q2 2023.
Notably, this meeting will provide an updated Summary of Economic Projections (SEP), including the infamous “dot plot” of Fed members’ interest rate expectations. Traders will be keen to see when and where Federal Reserve policymakers see this tightening cycle coming to an end. Finally, the central bank is still ramping up its Quantitative Tightening (QT) program to wind down its balance sheet, so any comments around how Jerome Powell and Company see that developing could move markets as well.
Technical view: US dollar index
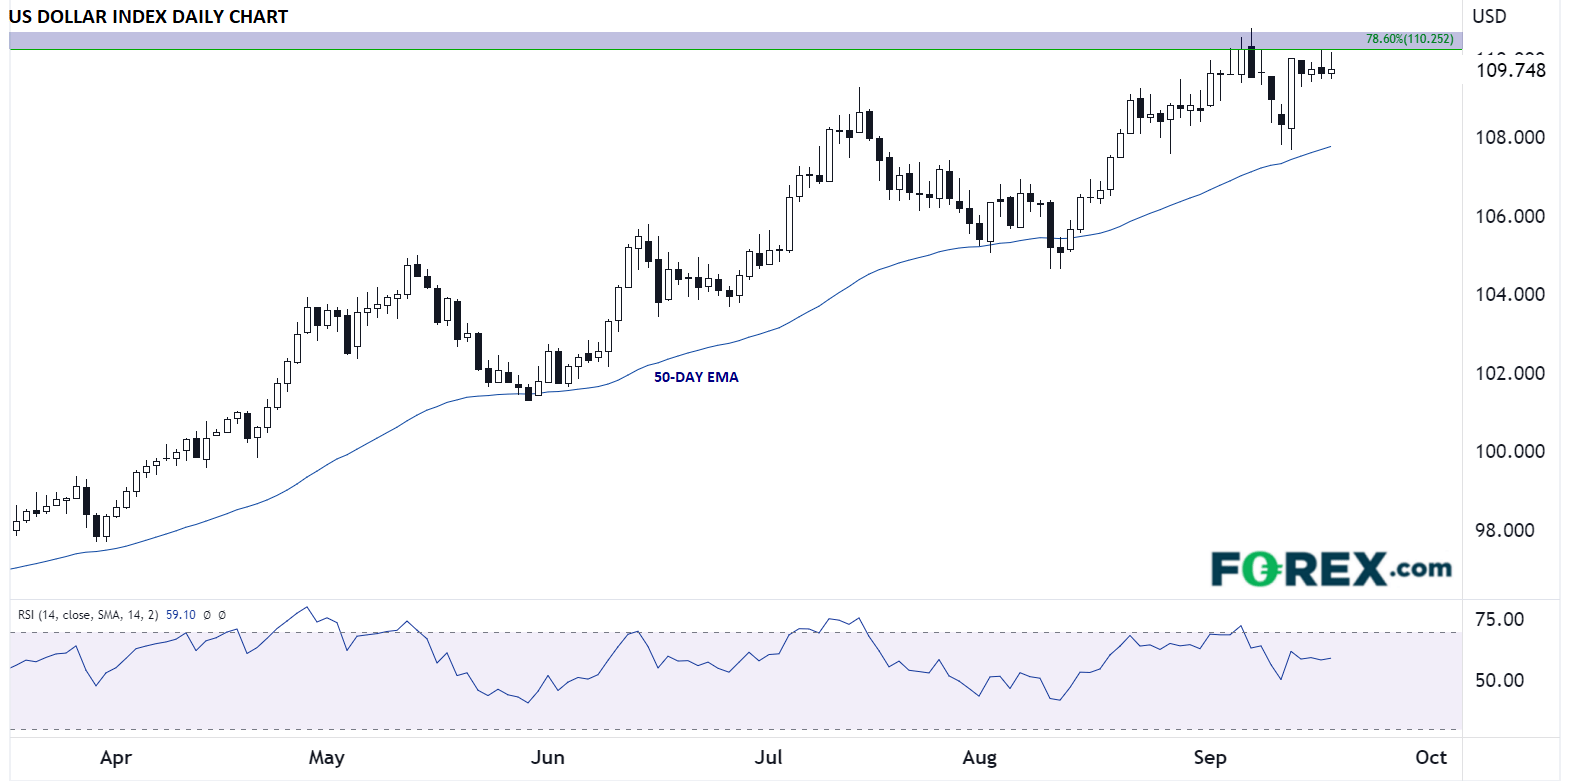
Going long the US dollar remains the most obvious trade in the FX market (though that doesn’t necessarily means it will work out!). Not surprisingly, the US dollar index continues to find support at its rising 50-day EMA, keeping the bias in favor of the bulls. As of writing, the index is testing the 78.6% Fibonacci retracement of its big 2001-2008 fall near 110.25, but if the Fed comes off as more hawkish than anticipated, a break and close above that area could target 112.00 or higher heading into October:
Source: TradingView, StoneX
When is the FOMC monetary policy meeting?
The FOMC’s September monetary policy meeting will conclude at 14:00 ET on Wednesday, September 21. Fed Chairman Jerome Powell’s accompanying press conference will begin at 14:30 ET.
What are traders expecting from the Fed meeting?
According to the CME’s FedWatch tool, traders and economists are pricing in about 84% chance of a 75bps (0.75%) interest rate increase to the 3.00-3.25% range, with an outside shot (~16%) of a full 100bps (1.00%) rate hike.
Source: CME FedWatch
FOMC meeting preview
It seems like a lifetime ago, but at this time last month, traders were thinking the Fed was more likely to raise interest rates by just 50bps (0.50%) in its September monetary policy meeting. However, after a hawkish address from Fed Chairman Powell at Jackson Hole, another solid NFP report, and a much hotter-than-expected CPI report, the market has completely thrown out any possibility of a mere 50bps rate hike and even started to price in an outside chance of a full 100bps (1.00%) rise.
In our view, the possibility of a 100bps rate hike is overblown. Lost amongst traders’ handwringing over the Fed’s clear focus on defeating inflation and the hotter-than-anticipated CPI reading is the fact that inflation is still declining relatively sharply. After all, the year-over-year CPI inflation rate has fallen from 9.1% to 8.5% to 8.3% over the last two months.
While the Fed would certainly have preferred to see a rate closer to 8.0% last month, other measures of inflation are clearly falling rapidly, suggesting that the hotter-than-expected CPI reading may be a one-off outlier. For example, the recently-released New York Fed survey showed that 1-year inflation expectations fell to 5.7% (from 6.2%) previously, and the survey’s average 3-year expectation for inflation fell from 3.2% to 2.8%, within shouting distance of the Fed’s long-term target near 2%. In other words, there is no evidence that we are entering a self-fulfilling cycle of rising prices; if anything, the evidence suggests that consumers and businesses expect price pressures to keep dropping in the coming quarters.
Instead of pointing to a 100bps rate hike this month, the stubborn inflation readings of late suggest that the central bank may be forced to raise interest rates for longer, perhaps into the first half of 2023, rather than pausing the current tightening cycle at the end of this year. A month ago, traders were pricing the peak interest rate for this cycle around 4.00% in January; now the market expects rates to peak closer to 4.50-4.75% in Q2 2023.
Notably, this meeting will provide an updated Summary of Economic Projections (SEP), including the infamous “dot plot” of Fed members’ interest rate expectations. Traders will be keen to see when and where Federal Reserve policymakers see this tightening cycle coming to an end. Finally, the central bank is still ramping up its Quantitative Tightening (QT) program to wind down its balance sheet, so any comments around how Jerome Powell and Company see that developing could move markets as well.
Technical view: US dollar index
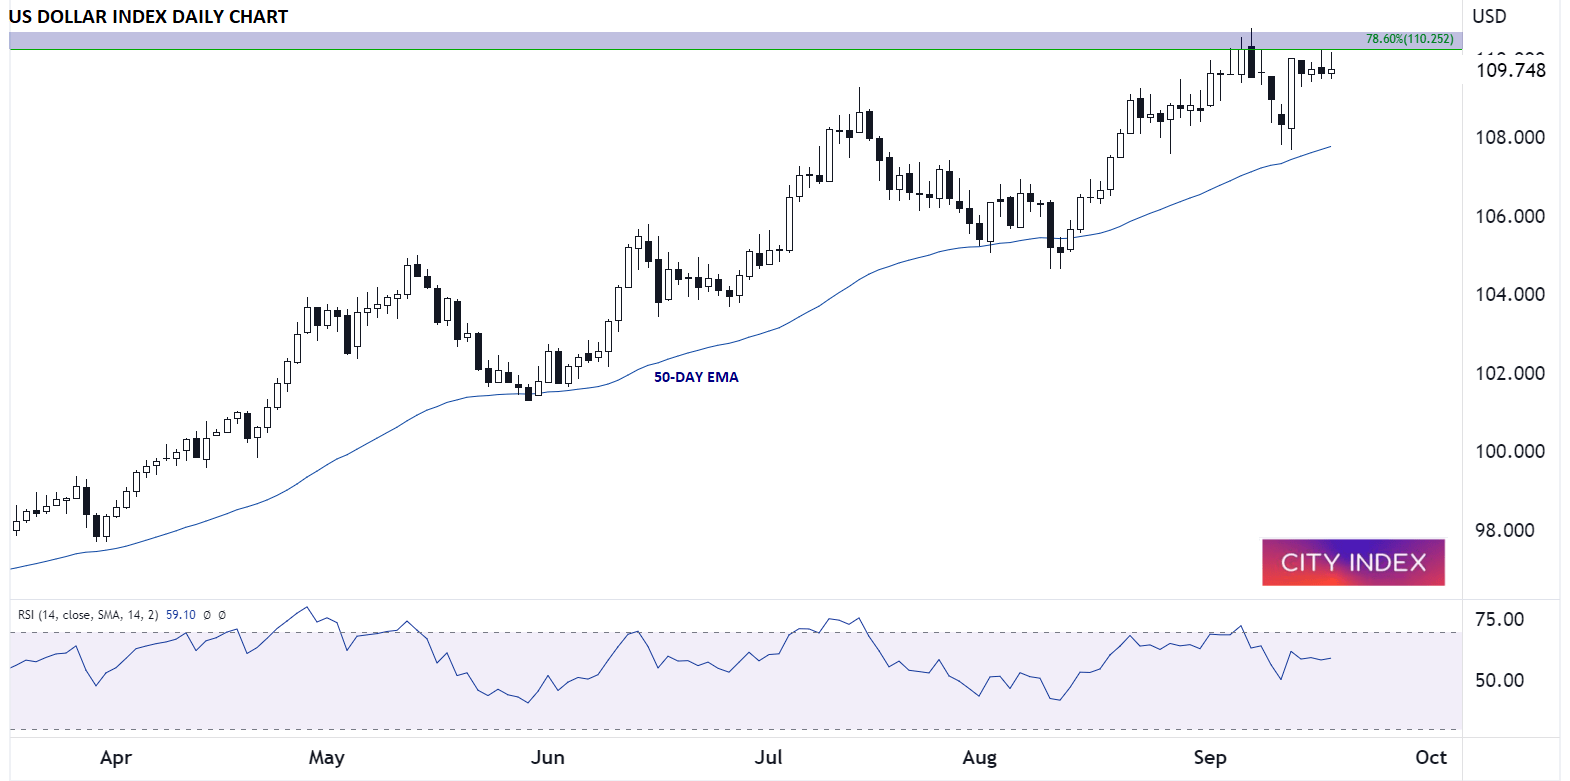
Going long the US dollar remains the most obvious trade in the FX market (though that doesn’t necessarily means it will work out!). Not surprisingly, the US dollar index continues to find support at its rising 50-day EMA, keeping the bias in favor of the bulls. As of writing, the index is testing the 78.6% Fibonacci retracement of its big 2001-2008 fall near 110.25, but if the Fed comes off as more hawkish than anticipated, a break and close above that area could target 112.00 or higher heading into October:
Source: TradingView, StoneX
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Have Markets Found a Turning Point Ahead of the Elections?
Fed rate-hike bets topping 70% have pressured markets, including precious metals and U.S. indices, toward key support levels. Could these levels signal a turning point ahead of the U.S. midterm elections?
EUR/USD Analysis: Euro Confidence Remains Limited After the ECB
The trading week is approaching its end and, for now, a neutral tone continues to dominate the euro's short-term price action. EUR/USD has recorded a move of only around -0.15% during the week, highlighting the pair's inability to establish a clear direction in favor of either the euro or the U.S. dollar.


USD/CAD Analysis: Canadian Dollar Strength Returns After Fed and BoC Decisions
With just one trading session left before the week comes to an end, the strength that has recently emerged around the Canadian dollar has once again become relevant. This can be observed in the recent performance of USD/CAD, which has declined nearly 0.3% over the last two trading sessions.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.