



GBP/USD forecast: Currency Pair of the Week | August 17, 2026
There will be some key data from the UK to watch this week, which could set the tone for the pound, while the macro calendar in the US is a lot quieter. Once again, much of the market’s direction may therefore come down to crude oil. The greenback has been weighed down in recent weeks by a softer run of data which has reduced expectations of a Federal Reserve rate hike in September.
Share this:
There will be some key data from the UK to watch this week, which could set the tone for the pound, while the macro calendar in the US is a lot quieter. Once again, much of the market’s direction may therefore come down to crude oil. The greenback has been weighed down in recent weeks by a softer run of data which has reduced expectations of a Federal Reserve rate hike in September. This has allowed currencies such as the pound to climb somewhat more noticeably during this period, owing to a higher yield advantage in the UK than currencies where interest rates are low or zero, such as the Swiss franc. However, looking ahead, the GBP/USD forecast is still far from bullish given the risks oil prices pose to inflation and growth.
Oil holds gains as US-Iran standoff persists
Oil prices are consolidating last week’s sharp gains as the deadlock over the Strait of Hormuz continues. President Donald Trump has warned Americans to prepare for higher fuel prices, underscoring the potential economic fallout from the disruption. While there were some reports that there may be some extension to the ceasefire agreement, this is not the first time we have heard such headlines before they were subsequently denied by Iran.
The standoff around the Strait of Hormuz has caused traffic through the key shipping route to fall sharply. The disruption has been compounded by attacks on tankers operated by Abu Dhabi and on a Saudi Aramco refinery, highlighting concerns over the security of both shipping and oil infrastructure across the region.
For now, oil markets remain firmly in wait-and-see mode. Any fresh escalation around the Strait of Hormuz, could easily send prices sharply higher. Conversely, signs of a return to negotiations could ease supply concerns and leave room for some of last week’s gains to unwind.
Dollar under pressure but dovish Fed pricing factored in
Friday’s softer-than-expected US retail sales data for July has strengthened the argument against a September rate hike. On top of this, we have also had some in-line inflation data last week and a poor jobs report in recent weeks. Markets have not only reduced their tightening expectations for the September meeting, but their expectations for cumulative tightening through next year have fallen to around 35 basis points.
The US data calendar this week offers relatively little that is likely to alter that picture. The main event is Wednesday evening’s release of the minutes from the 29 July FOMC meeting.
That meeting produced a 9-3 vote to leave rates unchanged and was followed by a particularly confusing press conference. Since then, US activity data have softened somewhat. Even if the minutes contain references suggesting that the decision was closer than the headline vote implied, it may be difficult for markets to revert to a firmly hawkish interpretation of the Fed without good support from oil prices. That said, it is also worth pointing out that most of the dovish dollar pricing is already factored into the markets. For the dollar to fall sharply from here, the macro backdrop will have to deteriorate significantly.
Pound supported by yield advantage
The prospect of the Fed keeping rates unchanged for longer has provided further support for global risk assets. Investors appear comfortable maintaining long positions in carry and commodities, funded in part by lower-yielding currencies such as the Swiss franc. This has allowed currencies where interest rates are comparatively higher to outperform. The UK base rate is currently similar to the US at 3.75% and is one of the highest among G10 currencies, with only Australia having a higher base rate of 4.35% at the moment. As a result, the GBP/USD has found decent support in this environment.
UK CPI among key data highlights
The markets are currently pricing in around 55bp of Bank of England tightening. With the UK economic calendar becoming more interesting after several relatively quiet weeks, those expectations are subject to change. Labour-market and wage data are due on Tuesday, followed by July’s CPI figures on Wednesday. After back-to-back falls in the previous couple of months, CPI is expected to have climbed back to 2.9% year over year in July compared to 2.6% y/y in June. With GDP overshooting last week, any upside surprises could further support the resurgent GBP, while any dovish surprises could see the GBP/USD give back some of its recent gains.
GBP/USD forecast: technical analysis and levels to watch
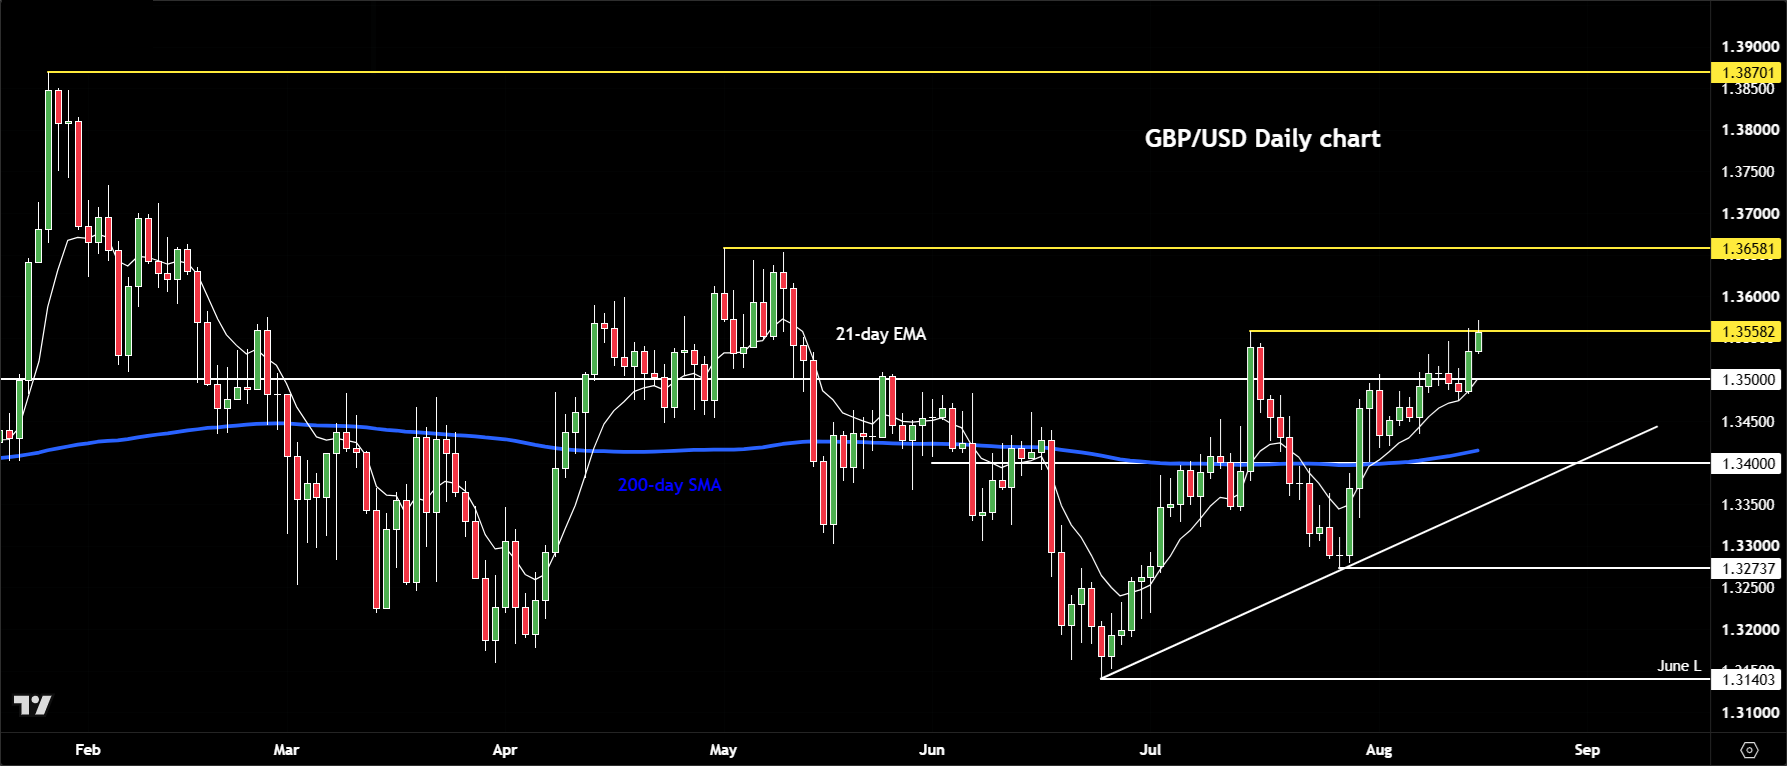
At the time of writing, the GBP/USD was testing its highest levels since mid-May. While that may sound impressive, it is also worth noting that the cable is basically stuck inside a long-term consolidation phase. The near-term momentum has still been more on the bullish side with the pair now back above the 21-day exponential average having spent only a few days below the 200-day average in the last weeks of July. With former resistance levels such as 1.3400 and 1.3500 reclaimed, these will now be the key levels of support to watch on any near-term dips. The early May high of 1.3658 is the most important reference point to keep an eye on should the bullish momentum build here. Above that, the January high is at 1.3870.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.

USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.


Canadian Dollar Analysis: USD/CAD Returns to July Highs Ahead of NFP
The Canadian dollar continues to face one of its most challenging environments in recent months when it comes to maintaining strength against the U.S. dollar. The weakness of the Canadian currency is clearly reflected in USD/CAD, which has now recorded nine consecutive bullish sessions and gained more than 1.7% during that period.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.