

GBP/USD forecast: US Mid-terms, NFP and BoE put cable in sharp focus
The US dollar has been a standout loser in the FX space today. A Democrat-controlled Congress is widely seen as being at least mildly negative for the dollar, partly because of the potential implications for the AI investment story and partly because of the risk of another prolonged government funding standoff, potentially from next summer. This has allowed the likes of the GBP/USD to rally alongside gold and silver.
Share this:
The US dollar has been a standout loser in the FX space today. A Democrat-controlled Congress is widely seen as being at least mildly negative for the dollar, partly because of the potential implications for the AI investment story and partly because of the risk of another prolonged government funding standoff, potentially from next summer. This has allowed the likes of the GBP/USD to rally alongside gold and silver. The GBP/USD forecast faces more event risk, with Thursday's Bank of England rate decision and Friday's non-farm payrolls report to come.
- The US midterm elections, Thursday's Bank of England decision and Friday's payrolls put cable in sharp focus
- Sterling has traded relatively well, but the pair is retesting resistance as the dollar decides whether to falls further ahead of NFP
- If 1.35 resistance holds, the bears will still need to create a reversal pattern to tip the balance back in their favour
Dollar falls as oil drops and following big victory for the Democrats
With oil prices falling another 3.5% or so, this has removed one of the dollar’s supporting factors, while also boosting currencies of economies that rely on oil imports.
The US dollar also came under pressure following the mid-term elections. A Democrat-controlled Congress is seen as mildly negative for the dollar, partly because of the potential implications for the AI investment story and partly because of the risk of another prolonged government funding standoff, potentially from next summer.
Can the dollar find support from data?
Unless oil prices spike higher again, support for the dollar is now only likely to come from the US economy. Last week, third-quarter growth was a strong 3.4% annualised, inflation remains above target and the Federal Reserve is preparing to tighten policy again. This week, ISM manufacturing PMI, JOLTS Job Openings, Factory orders and ADP Non-Farm Employment (86K vs. 67K) have all come in stronger.
The ISM services PMI and October jobs report will be watched closely on Thursday and Friday, respectively.
The labour market is expected to show a modest improvement (+65K estimate) after September's weak reading, but unless Friday's report is particularly poor, it is unlikely to materially change the Fed tightening narrative.
Sterling finds support from an improving UK backdrop
Sterling continues to trade relatively well into Thursday's Bank of England rate decision, and the broader backdrop is becoming more supportive. UK economic surprises have improved, fiscal policy appears to be heading in the right direction and warmer relations with the European Union are helping sentiment, while oil prices have falling noticeably in recent days. Positioning provides another potential source of support, as speculative short positions in sterling remain relatively large, leaving room for further short covering.
Technical GBP/USD forecast and key levels to watch
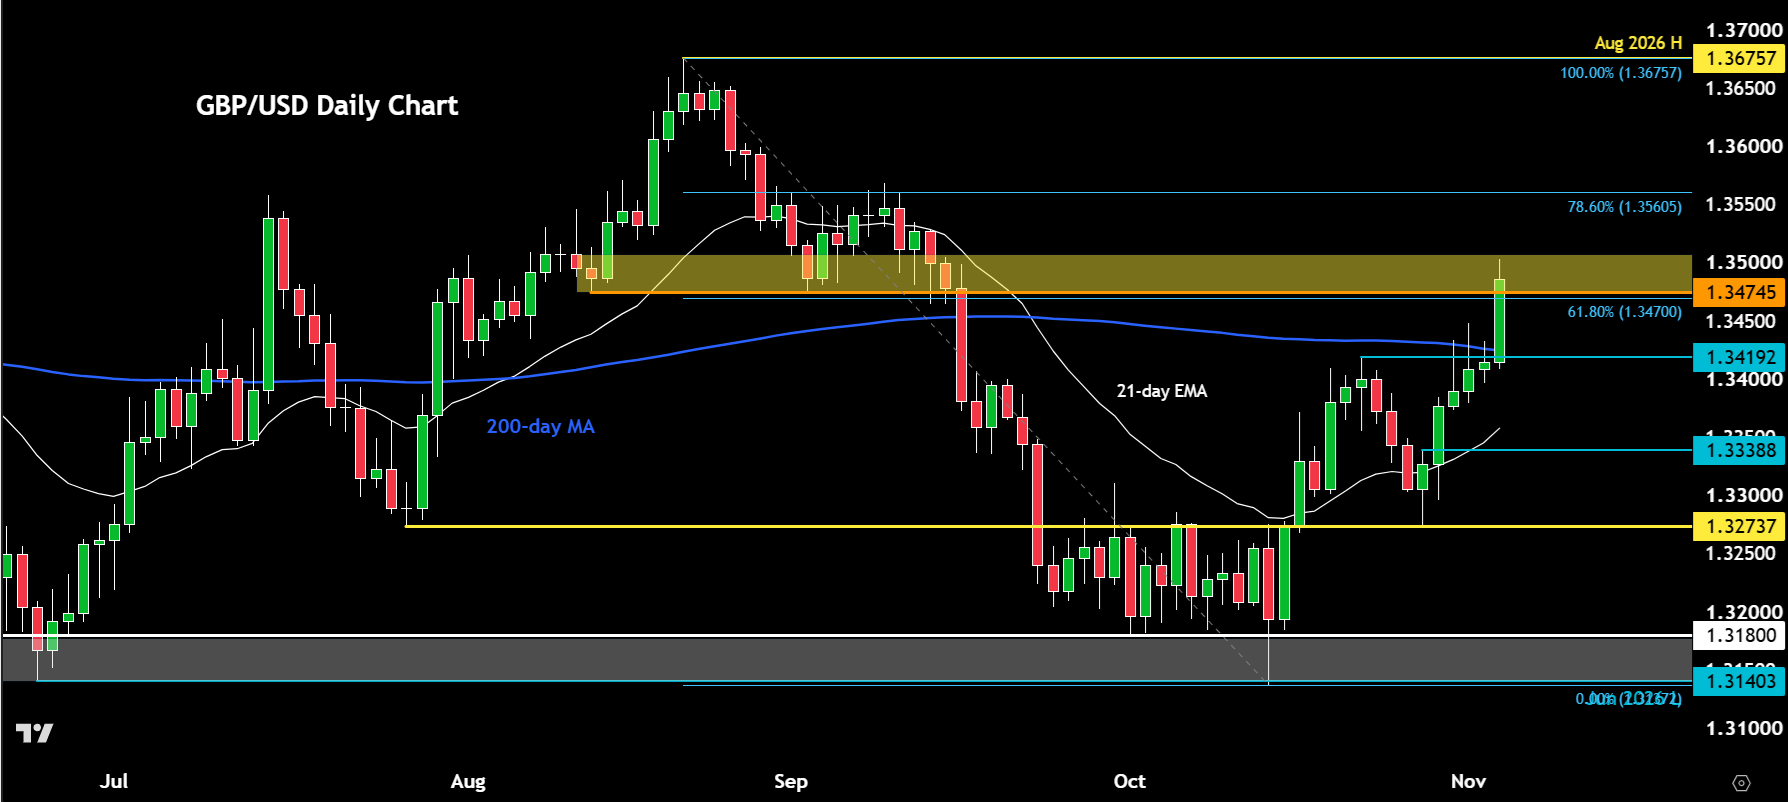
From a technical analysis point of view, cable was testing the 1.35 handle, having broken a key area of resistance between 1.3435 to around 1.3475, where the 200-day moving average, the 61.8% Fibonacci retracement of the last downswing and the resistance trend of a rising wedge pattern all converged. This area is now likely to be a potential support zone to watch. A break below here could lead to a drop towards 1.330, or even lower in the coming days.
Frequently Asked Questions
Is a Bank of England rate hike already priced into sterling?
Yes. A 25bp increase to 4.00% on Thursday is effectively fully priced, with expectations that the Bank of England has little choice but to raise rates.
What could support the dollar this week?
The potential for oil to rebound, or if we see significant improvement in US employment data on Friday.
What could further weaken the dollar's firm footing this week?
One source could be renewed technology sell-off. Another could be a collapse in oil prices.
-- Written by Fawad Razaqzada, Market Analyst | Follow Fawad on Twitter @Trader_F_R
Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD forecast: US Mid-terms, NFP and BoE put cable in sharp focus
The US dollar has been a standout loser in the FX space today. A Democrat-controlled Congress is widely seen as being at least mildly negative for the dollar, partly because of the potential implications for the AI investment story and partly because of the risk of another prolonged government funding standoff, potentially from next summer. This has allowed the likes of the GBP/USD to rally alongside gold and silver.
S&P 500 forecast: Democrats’ midterm victory rattled markets before dip buyers stepped in
Markets had a wild overnight session, with futures initially plunging before staging a sharp reversal and turning decisively higher. Global equity markets also bounced back, alongside gold and silver, while the US dollar has weakened. Oil prices fell on hopes of a deal between the US and Iran, providing another boost to market sentiment. The key question is why have markets rebounded so strongly and, more importantly, whether the recovery can last, given the prior assumption that a blue sweep would have been net negative for stocks?
Blue wave adds to Nikkei’s AI troubles
The Nikkei 225 has taken another beating as a Democratic sweep adds to concerns about AI investment returns. But after the scale of the earlier declines, how much bad news is already priced in?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.