

Gold forecast: Metal unable to shake off macro concerns
The near-term risks remain tilted to the downside for our gold forecast. That said, continued central bank buying, haven demand and inflation hedging all mean that the longer-term outlook is still quite compelling.
Share this:
Gold rose modestly during Asia trade but it was coming off highs when Europe got underway. The metal had closed slightly lower on Friday, giving back some of the gains made from Thursday. The multi-week bearish trend may have lost some momentum, but there is no compelling evidence that the metal has bottomed out yet. Thus, the near-term risks remain tilted to the downside for our gold forecast. That said, continued central bank buying, haven demand and inflation hedging all mean that the longer-term outlook is still quite compelling.
Gold stuck between competing macro forces
Indeed, gold has been caught between a rock and a hard place. Renewed inflation concerns from both hard and soft data, as well as rising oil prices, have raised concerns that central banks will have to tighten their policies further in the coming months. This has kept global yields near recent highs despite a bit of moderation in recent days. With the US 10-year yield still holding above the key 5.00%-5.05% area, and given the renewed surge in oil prices, those concerns are unlikely go away. Investors have shown some preference to bonds due to their relatively higher yields compared to equities and zero-yielding gold and silver.
That said, it is not all doom and gloom. Providing support for gold has been continued buying by central banks, including from the People’s Bank of China. This has cushioned the downside risks to some degree. But will this be enough to prevent gold from going for at least a temporary breakdown below the $4K level? I am not so sure.
Oil rally revives the risk premium
The sharp move higher in oil towards the end of Friday’s session highlights inflation risks. Concerns over a potential US attack on Iran has been swirling. With crude supplies already impacted due to the situation at the Strait of Hormuz, the geopolitical risk premium is increasing in oil prices.
While the risk of military escalation remains, so does the political incentive to avoid a direct confrontation ahead of mid-terms. Iran, meanwhile, could also have an incentive to keep tensions elevated. Higher oil prices put additional pressure on global consumers and complicate the inflation outlook, potentially giving Tehran some leverage, albeit at a significant economic cost.
Stronger Chinese data has had limited impact
China provided some encouraging data overnight. The world’s second-largest economy grew 4.5% year on year in the third quarter, above expectations of 4.4% and second-quarter growth of 4.3%. Industrial production (5.5% y/y), retail sales (1.1% y/y) and employment data also beat expectations.
But Chinese demand is only one part of the equation. Continued purchases by the People’s Bank of China and other central banks remain an important structural source of support, with little evidence so far that official-sector demand is about to disappear as we head into the final months of the year.
If those purchases remain strong, investors may look to position ahead of that underlying demand through ETFs, spot and futures markets. That could cushion gold even if the short-term technical picture remains fragile.
A though on gold’s bearish momentum
Indeed, gold fell 0.67% last week, thus resuming its multi-week slide. Over the past eight weeks, the metal has only managed two weekly gains. It therefore remains vulnerable to another leg lower. When the prevailing momentum is bearish, you have to be extra careful not to pre-empt any reversals, even if the metal is still holding a major support area around $4100. We need a confirmed bullish signal in this macro environment for the bulls to trade more confidently.
Technical gold forecast and levels to watch
Gold staged a decent recovery from the $4,075-$4,100 area in mid last week. This area marks the base of the rally that began in early August. Friday’s small reversal lower, however, suggests that the bounce may have run its course. The bearish trend line has held firm for now.
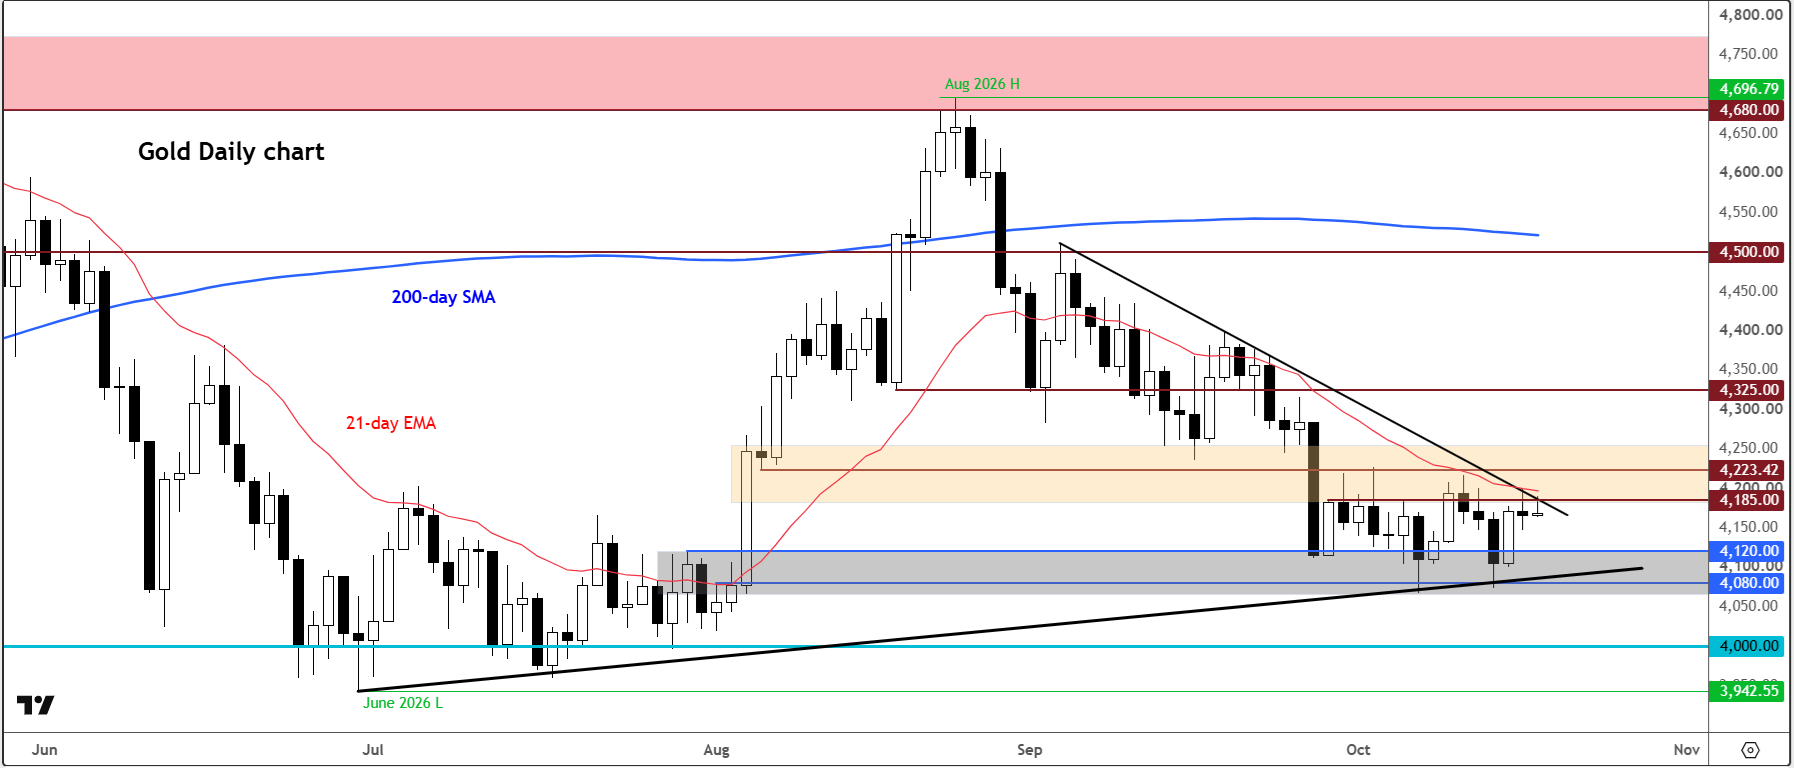
Gold needs to break this trend line before the technical picture starts to improve. Even then, resistance around $4,223-$4,260 would need to be cleared before there is enough evidence to confirm that a more meaningful bottom is in place.
Until then, another bout of selling remains possible for the gold price this week, particularly if oil stays elevated and yields resume their climb. In the longer-run, though, the gold forecast is still bullish.

Related tags:
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Update: XAU/USD Remains Directionless Despite Falling Yields
As the trading week continues to unfold, the lack of direction dominating gold price action remains a relevant theme in the short term. In fact, the average move over the last three trading sessions has resulted in a decline of barely 1.0%, highlighting that neither buyers nor sellers have been able to take control in a consistent manner.
EUR/USD forecast remains tilted lower towards 1.10 handle
The EUR/USD forecast remains tilted to the downside, and a visit of 1.1000 is still on the cards, despite today’s small recovery.
AUD/USD, NZD/USD Outlook: Corrective Recoveries Face Growing Headwinds
A weaker US dollar, falling Treasury yields and renewed demand for cyclical assets have supported the Aussie and Kiwi. But with some of those moves reversing on Monday, both currencies face an early test of whether their recent strength can continue.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.