



Hot CPI Reinforces RBA Hike Bets, Though Cracks Remain in the Economy
Australia's hot Q3 CPI strengthens RBA November hike expectations, but weaker employment and sentiment complicate the outlook for 2027.
Share this:
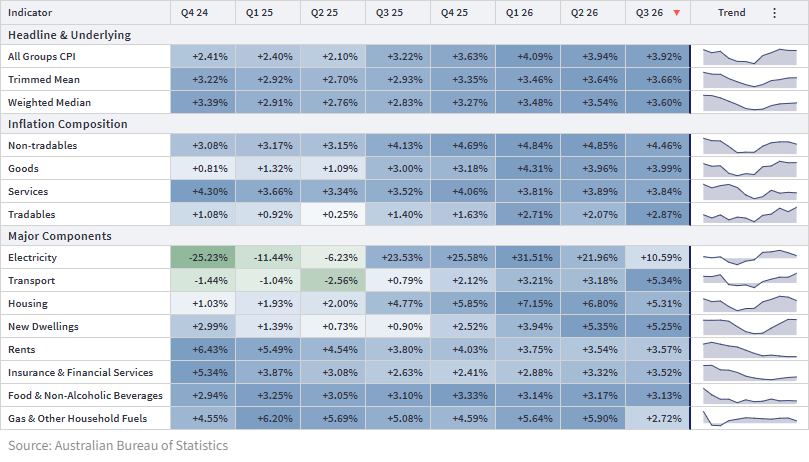
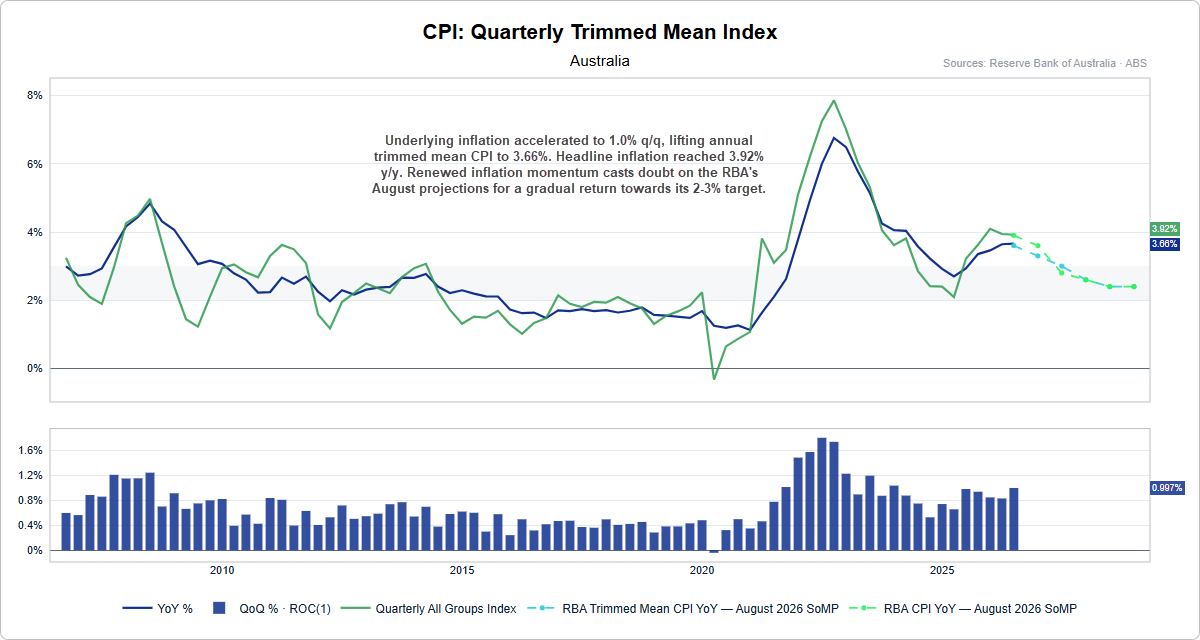
Australian Q3 inflation figures have effectively cemented expectations for another RBA interest rate hike on 3 November. Quarterly trimmed mean inflation accelerated to 1.0% from 0.8% in Q2, lifting the annual rate to 3.7%. That marks the fourth consecutive quarter above the RBA's 2–3% target band, while headline inflation remained elevated at 3.9% y/y.
View related analysis:
Australian Q3 Inflation Fuels RBA Hike Expectations Despite Economic Weakness
Australian Inflation Pressures Extend Beyond Energy
While rising energy prices have contributed to headline inflation, the problem extends beyond fuel. Non-tradables inflation remained elevated at 4.5% y/y, alongside services inflation at 3.8%. Housing inflation also remained relatively high at 5.3%, while new dwelling prices rose 5.3%.
However, inflation is not accelerating across the board. Services, non-tradables and housing inflation have moderated, while tradables inflation accelerated to 2.9% from 2.1%.
This suggests that while domestic inflation pressures remain persistent, the latest acceleration is uneven, with external price pressures playing an increasingly important role.
Persistent Q3 Inflation Strengthens the Case for an RBA Hike
The RBA's Sarah Hunter had already signalled concerns over inflation when her interview aired on 60 Minutes on Sunday. Governor Michele Bullock reinforced the Bank's concerns during Wednesday's parliamentary hearing, warning that inflation remained far too high.
The RBA has also acknowledged that inflation is likely to exceed its August projections, with persistent domestic capacity pressures being compounded by higher global energy costs.
The acceleration in quarterly trimmed mean inflation is particularly concerning. At 1.0% q/q, underlying inflation is running at a pace inconsistent with a sustained return to the RBA's 2–3% target. And with inflation already tracking above earlier expectations, the Bank looks set to revise its inflation projections higher next week.
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of FOREX.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
RBA Cash Rate Outlook: November Hike Looks Increasingly Likely
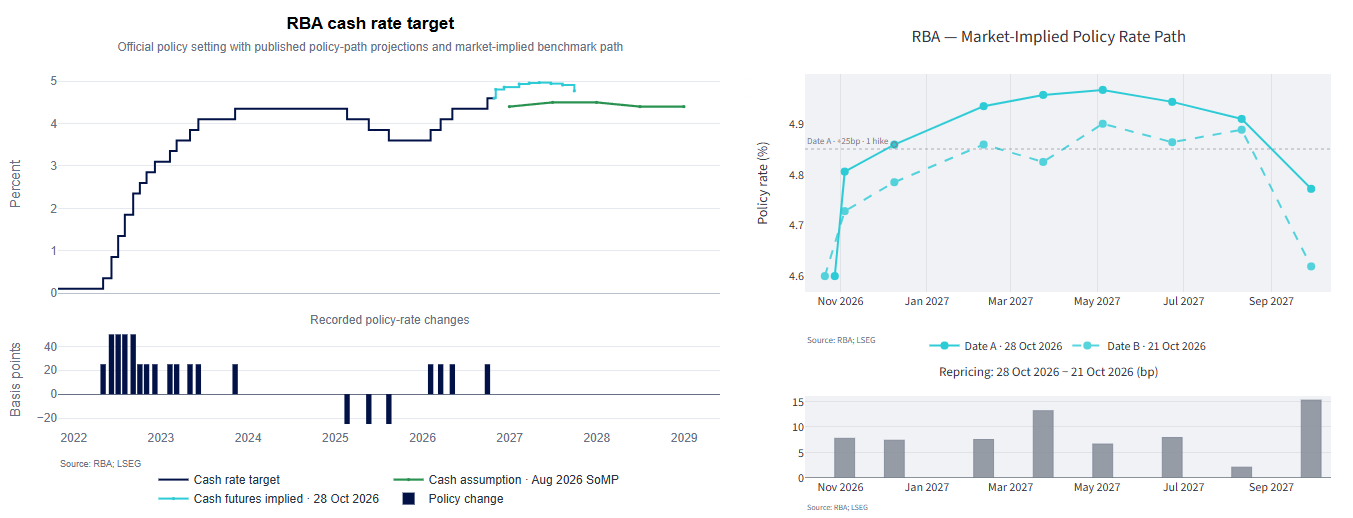
Markets are now pricing over an 80% probability of a November RBA rate hike, with the Q3 inflation figures reinforcing expectations of further monetary tightening.
The market-implied cash rate path also shifted around 6–8 basis points higher across much of 2027 following the CPI release, pointing to a peak near 5% around the middle of next year.
I doubt the RBA will follow up with another hike in December. However, next week's updated Statement on Monetary Policy should provide greater insight into its appetite for further tightening in 2027.
My base case is that the RBA retains a hawkish bias, potentially leaving room for one further hike in H1 2027.
Weakening Economic Conditions Could Limit Further RBA Tightening
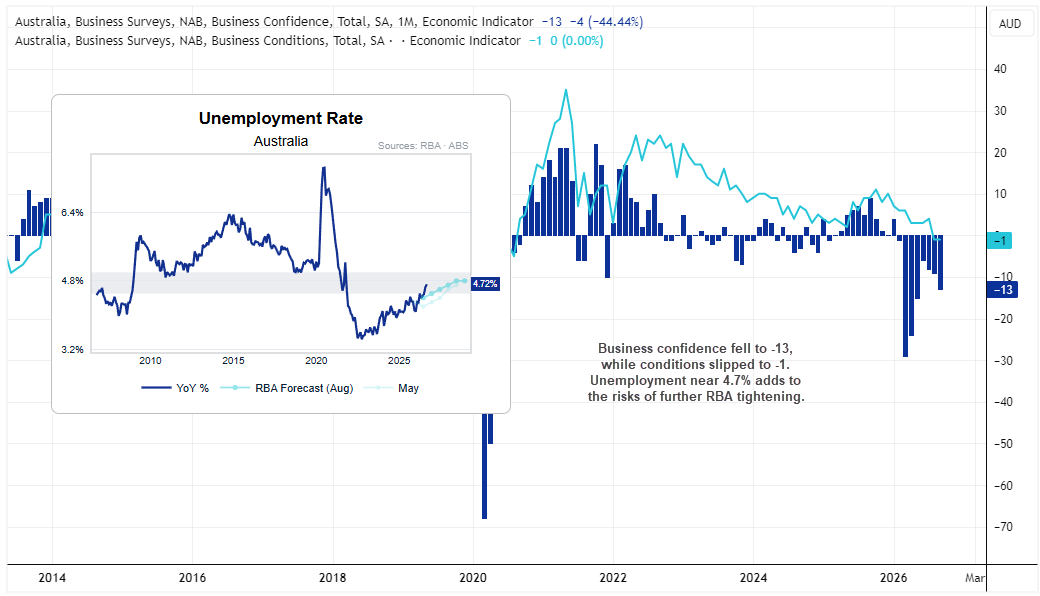
While persistent inflation makes a November hike difficult to avoid, the broader Australian economy gives the RBA reason to remain cautious about further tightening.
Employment has weakened, unemployment has risen to 4.7%, and consumer and business sentiment remain subdued. NAB business confidence fell to -13 in September, while business conditions slipped into negative territory.
The November decision itself may be relatively straightforward. The greater challenge for the RBA will be bringing inflation back under control without placing unnecessary strain on an already weakening economy.
And that could ultimately determine how much further the Bank is prepared to tighten in 2027.

Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Analysis: Australian Dollar Holds Steady Ahead of Inflation Data and the Fed
As the trading week progresses, a cautious tone is becoming increasingly evident around the Australian dollar. This can be observed in the recent performance of AUD/USD, where price action has remained largely unchanged over the last three trading sessions, recording a move of barely 0.1%. This behavior highlights a clear lack of direction within the market.

Silver Analysis: XAG/USD Falls Back to Annual Lows
Recent sessions have been particularly challenging for silver prices in the short term. Selling pressure has intensified considerably, resulting in three consecutive losing sessions and pushing the metal to a decline of nearly 8.5% over this period.
EUR/USD Analysis: Euro Loses Ground After a Stronger-Than-Expected U.S. CPI Report
The trading week continues to unfold and weakness around the euro has once again become increasingly evident in the short term. This can be seen in the recent performance of EUR/USD, which has declined roughly 0.3% over the last three trading sessions, highlighting renewed strength in the U.S. dollar.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.