



Indices weekly outlook: DAX forecast
The week ahead is set to be a busy one for the earnings calendar, while the macro calendar is again set to be quieter with the ongoing US government shutdown delaying the release of data there. Elsewhere, UK CPI on Wednesday and Global PMIs on Friday should bring about a bit of volatility for European markets. Among the indices to watch is the German DAX index this week, with the release of a few major company results to set the tone, including SAP in mid-week.
Share this:
The week ahead is set to be a busy one for the earnings calendar, while the macro calendar is again set to be quieter with the ongoing US government shutdown delaying the release of data there. Elsewhere, UK CPI on Wednesday and Global PMIs on Friday should bring about a bit of volatility for European markets. Among the indices to watch is the German DAX index this week, with the release of a few major company results to set the tone, including SAP in mid-week. With the impact of the huge fiscal push that could reshape sentiment in Europe to come, we maintain a bullish DAX forecast following the recent volatility.
The DAX took a hit last week, along with global markets, although finished the week off its worst levels on Friday. Between renewed US-China trade tension, credit risk in US regional banks, and stretched equity valuations, there was plenty to worry about last week. Yet, as we’ve seen time and again in 2025, all it takes is one optimistic headline — or even a single Trump post — to turn sentiment on its head. And that is what markets got on Friday when a Trump interview led investors to believe a deal with China to at least extend the trade war truce is forthcoming.
DAX forecast: EU equities still have reasons to stay upbeat
Despite weak data out of Germany, European stock market investors aren’t without hope. France’s recent political stability has helped calm nerves, sending the CAD sharply higher last week. What’s more, falling oil prices are easing inflation pressures. Add to that the growing conviction that the Fed could deliver two rate cuts before year-end, and the downside for equities looks limited.
But perhaps the biggest stimulus is Germany’s fiscal plans. Berlin’s €500 billion infrastructure package — alongside another €500 billion for defence and green initiatives — could provide a long-term lift to the Eurozone economy. That kind of spending backdrop doesn’t come around often, and it’s tough to stay bearish when policymakers are clearly shifting towards growth. Granted, the tangible economic benefits may not fully materialize until 2026, but the psychological impact is already being felt. That’s supportive for the DAX forecast, even if traders remain hesitant until they see results in hard data. For now, soft German industrial output and fading consumer sentiment have kept the European Central Bank’s dovish camp in control, hinting at the possibility of one more rate cut next year.
The week ahead: UK CPI, global PMIs and company earnings
- UK CPI
Wednesday, October 22
There’s been some concern over the UK government’s upcoming budget that could lose investor confidence, specifically Chancellor Reeve’s reliance on tax rises over spending cuts to meet her fiscal rules is what worries investors. UK data has also been mixed recently and the pound has eased back. With budget uncertainty at the forefront, the FTSE could drop sharply if CPI raises stagflation worries in the UK, although the UK 100 did form a bullish hammer candle on Friday to suggest the low might be in after the recent dip.
- Global PMIs
Friday, October 24
We have seen a number of weaker hard data from the Eurozone’s largest economy Germany of late, and this has held back the euro. Meanwhile political crisis in France has weighed on business and consumer sentiment there. Will Eurozone PMIs surprise to the downside? If they do, this will only underscore the need for more fiscal stimulus from Germany.
- Possible release of US data
US government data releases have been impacted by the ongoing government shutdown. The non-farm payrolls were among a number of government reports that were due for release, but never arrived. If the government re-opens, we could see a raft of US data releases in the week ahead. But there are no certainties, and are subject to delay, revision, or cancellation. Media reports suggest CPI could be released on Friday, October 24.
German company earnings
The week ahead features a handful of Frankfurt-listed corporate earnings, with SAP set to kick things off on Wednesday. Here’s what’s coming up in the week ahead, which has the potential to impact the DAX forecast:
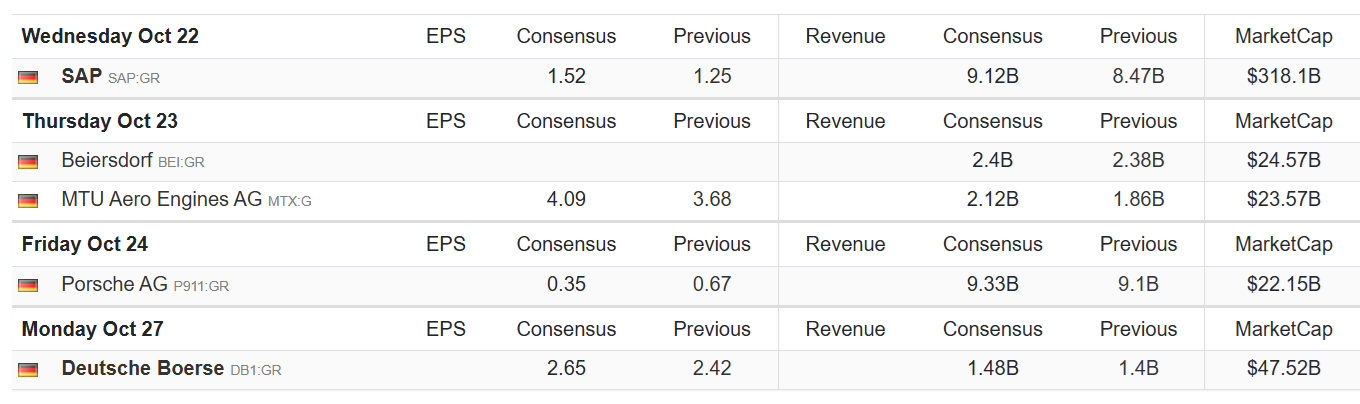
Source: tradingeconomics.com
Technical analysis: DAX outlook positive – for now
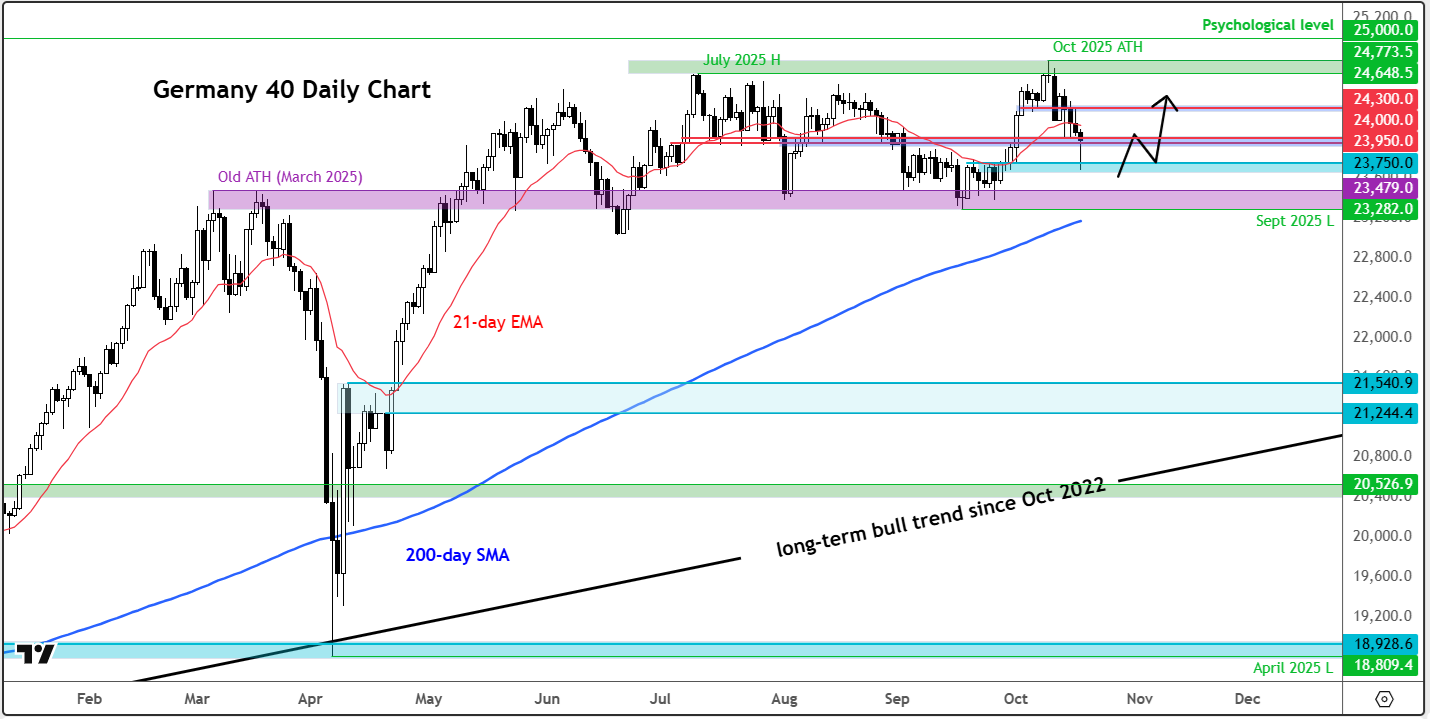
From a technical perspective, the DAX’s slide last week came as a surprise — especially after breaking to fresh highs just a week earlier. Still, the bulls deserve the benefit of the doubt. The index has held the first retest of a key inflection zone near 23,700–23,750, an area that served as the breakout level not long ago. If buyers defend this region, we could see another leg higher. Should that fail, the next major support lies around 23,280–23,480, marking a massif area of prior support and resistance.
Meanwhile resistance sits at 23,950 and 24,000, where the index closed Friday’s session at. A clean break above this area could open the door to the next resistance near 24,300. Above that? Fresh record highs and potentially the 25,000 handle.


-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.
EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.

USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.