Marketbrief: Markets continue Slide as Iran Conflict Deepens and Oil surges higher
The Iran conflict intensified with expanded US-Israeli strikes, tanker threats and near-halted Hormuz traffic, keeping oil elevated and global markets on edge. APAC stabilized slightly, Europe weakened, and the DAX remained under bearish pressure. US equities fell as crude swung and safe‑haven flows eased late. FX and rates reflected energy-driven inflation risks while gold and commodities regained strength.
Share this:

Market Brief: 6 March 2026
1. Macro & Geopolitical Backdrop
Iran Conflict Escalation (Key Market Driver)
- The US and Israel intensified airstrikes on Iran, including on Tehran, Urmia, Isfahan and Karaj, with CENTCOM confirming ~2,000 targets hit and the destruction of 17 Iranian ships.
- President Trump said the US has “just begun to fight” and intends to significantly increase firepower; also stated Iran’s missile attacks have fallen 90%.
- Trump publicly supports a Kurdish armed uprising in Iran and claims a role in shaping Iran’s next leadership.
- Iran maintains it is “ready for a ground invasion”, refuses negotiations, and targeted Microsoft data centres in drone attacks.
- Shipping through the Strait of Hormuz is near‑halted; air‑raid sirens and drone strikes were reported across Kuwait, Bahrain, Qatar and Saudi Arabia.
- UAE is considering freezing Iranian assets;
- NATO has raised ballistic‑defence posture and willingness to expand.
Strategic view: The conflict is now a multi‑theatre event with systemic risks to energy supply, shipping, and global risk sentiment.
2. Global Markets
APAC
- APAC equities were mixed, stabilising slightly after recent heavy selling but still driven by geopolitical tension.
- ASX pressured by miners amid higher energy‑driven inflation concerns; Hang Seng and mainland indices modestly higher on tech earnings.
- Japan’s Nikkei swung indecisively, with no new domestic catalysts.
Europe
- Euro Stoxx 50 opened weaker with -1% after Thursday’s −1.5% session.
DAX Technical Analysis 4 Hour chart
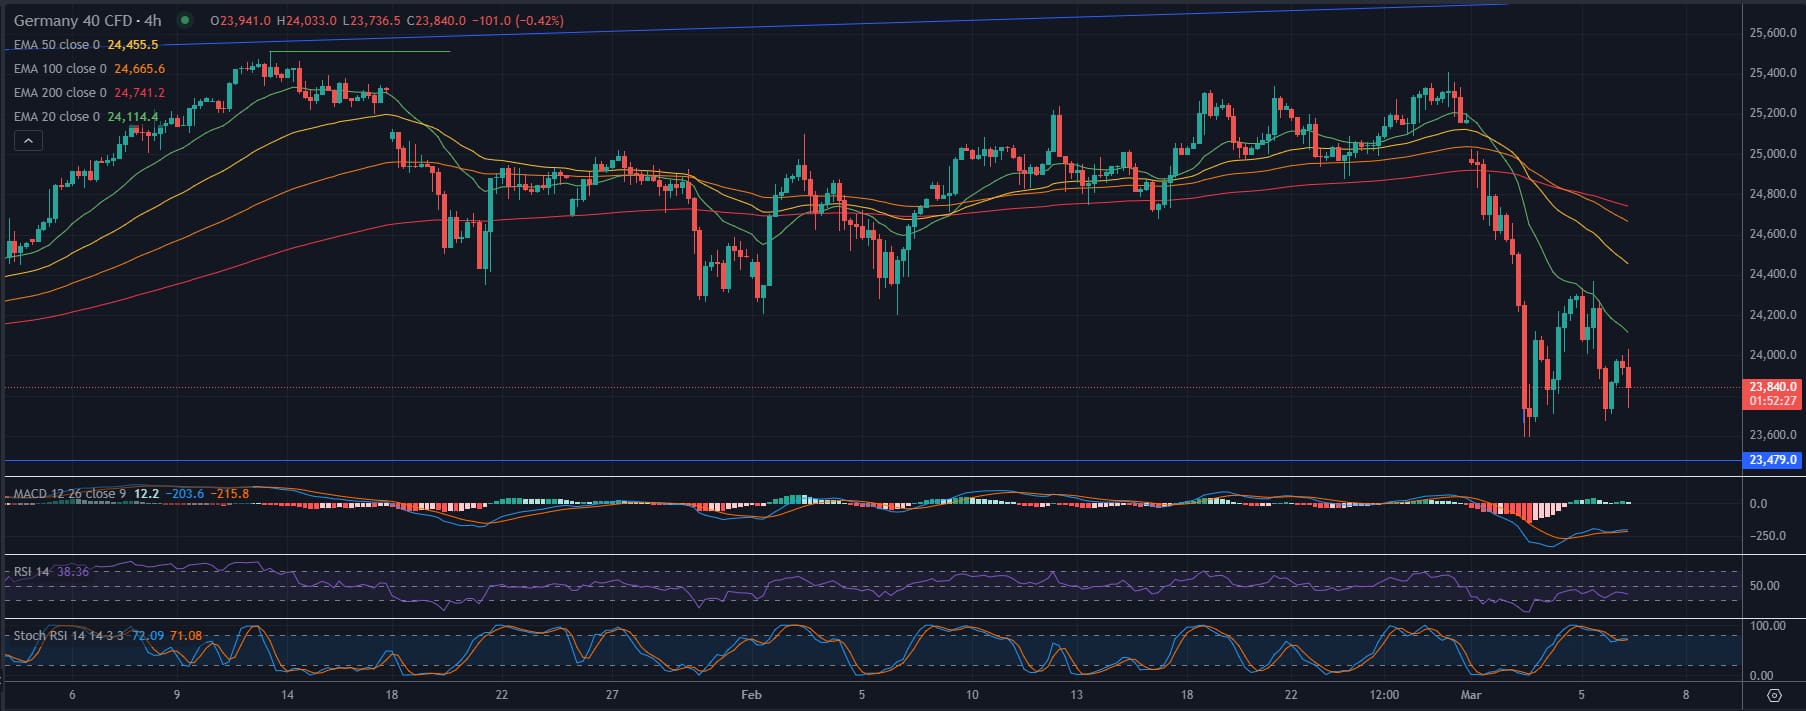
The Germany 40 continues to trade in a bearish short‑term structure after failing to reclaim the 20‑EMA and 50‑EMA, both of which are now firmly sloping downward. Price remains below all major EMAs, confirming sustained downside momentum. The sharp rejection near 24,950 and the inability to create a higher high reinforce the bearish bias. The index is now hovering just above the key horizontal support at 25,040, a level that acted repeatedly as a springboard throughout February. A clean break below this level would likely accelerate downside pressure, exposing the next support around 24,700, followed by 24,500 if selling intensifies.
Momentum indicators remain aligned with continued weakness. The MACD histogram, while slightly improving, is still negative and below its signal line, showing bearish dominance despite a mild slowdown. RSI sits near 36, indicating bearish momentum but not yet deeply oversold, leaving room for additional downside. Stochastics has begun to turn up from oversold territory, suggesting a short‑term bounce is possible—but only if the 25,040 support holds. Overall, the market remains under pressure, with any recovery attempt needing a break above 25,000–25,050 to neutralize the decline. Until that happens, risk remains skewed to the downside.
US Markets
- US equities fell but remained off the worst levels: SPX −0.56%, NDX −0.29%, DJI −1.61%, RUT −1.91%.
- Risk‑off mood dominated as the Iran conflict showed no signs of easing; crude rallied then pared gains after news China is negotiating safe passage through Hormuz with Iran.
- Treasuries, gold and USD eased off safe‑haven highs late in the session.
3. Commodities
Energy
- Oil stayed elevated, supported by war escalation and reduced Hormuz traffic, though some gains reversed after China–Iran talks on shipping safety.
- US issued a 30‑day waiver allowing stranded Russian oil to be sold to India.
- QatarEnergy warned it cannot fulfil five LNG cargoes in early April; Saudi Arabia sharply raised OSPs for Asia and Europe.
Metals & Gold
- Gold rebuilt strength, reclaiming USD 5,100/oz on haven demand.
- CME cut gold and silver margins, increasing liquidity.
- Copper rebounded alongside APAC equities and a strong private China PMI.
4. FX & Rates
FX
- DXY stabilised after a strong safe‑haven bid the prior day.
- EUR/USD at ~1.1600, capped by energy stress and geopolitical spillover.
- JPY steady, with Japan lacking new macro inputs.
- AUD outperformed mildly on higher metals and stronger RBA rate‑hike speculation.
Rates
- USTs languished near lows as energy‑driven inflation concerns persist.
- Bunds attempted to recover but remain pressured ahead of EU GDP and German factory orders.
- JGBs traded choppily without clear direction.
5. Trade Policy & Regulation
- Twelve US states are preparing to sue the administration to block new global tariffs.
- Bessent considers asking China to cut oil purchases from US adversaries ahead of the Trump–Xi summit.
- The US is drafting rules requiring licenses for AI‑chip exports globally, affecting all Nvidia and AMD shipments.
- Canada & EU signed a deal to modernize their trade agreement.
6. Key Data & Central Banks
- Focus turns to:
- US NFP, Retail Sales
- EZ Q4 GDP (3rd estimate)
- ECB speakers including Lagarde
- Fed’s Daly, Collins, Hammack
- ECB minutes show openness to keeping rates at current levels for an extended period if the baseline holds.
- RBA’s Hauser, PBoC adviser highlight limited scope for aggressive stimulus in China.
- Fed’s Bowman: Too early to judge war’s economic impact; uncertainty around tariffs rising.
7. Investment Implications
1. Energy & Commodities – Stay Overweight
- Hormuz disruption risk is systemic; even partial reopening relies on China–Iran talks.
- LNG supply risks rising sharply after QatarEnergy force majeure‑type signals.
2. Equities – Elevated Volatility, Prefer Quality & Low‑Beta
- US and APAC volatility remains tied to each Iran headline.
- Defensive sectors (utilities, staples, healthcare) likely to outperform.
- Avoid high‑beta EM with heavy energy‑import dependence.
3. FX – Strong USD Bias
- Geopolitics + energy inflation support USD.
- EUR and GBP face structural drag from proximity to energy shocks.
4. Fixed Income – Neutral Duration, Tactical Long in Safe Havens
- USTs attractive on spikes in geopolitical fear but vulnerable to energy‑driven inflation rebounds.
5. Alternatives – Gold & Digital Assets
- Gold supported by sustained haven flows and margin reductions.
- Bitcoin remains volatile but saw structural upside around crisis moments.
-Philip Papageorgiou – Markt Analyst
--X ex Twitter: PhilipForexCom
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Short-term Outlook: USD Four-Week Rally Stalls Below Key Resistance 10 8 2026
DXY is holding in a tight range beneath major resistance as traders await the next catalyst from inflation expectations and Fed repricing.
Canadian Dollar Technical Outlook: USD/CAD Five-Week Rally Sets Up Major Breakout Test 10 8 2026
USD/CAD is holding near fresh yearly highs, with a tight October range keeping the focus on a potential breakout through major resistance.
Dow Jones forecast: Stocks extend drop amid surging oil and elevated yields
The global equity markets remain under pressure and with oil surging higher again this week, we have even more reason to remain cautious. Already, the S&P and Nasdaq were running support from only a handful of hyperscalers and AI stocks. But even these indices have started to take notice of the deteriorating market breadth and global indices. Still, for me, the ongoing weakness is becoming more evident in the Dow and the small-cap Russell 2000 indices, and as such I will continuing watching these markets closely to provide a more accurate signal about the health of the stock markets.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.