S&P 500 Pulls Back From Another Fresh ATH As Yields Soften
Both the S&P and Nasdaq set fresh ATHs on Wednesday, and despite relief in yields, stocks are pulling back again today.
Share this:
S&P 500 Talking Points:
- Stocks have continued to rally even as Treasury yields have continued to jump.
- Higher yields aren’t necessarily a deal-breaker for stocks, as higher levels of growth come with higher levels of inflation, and that erodes the rationale for holding debt. What is a bigger issue, however, is when yields are falling especially if that comes along with recessionary fears. A bull market in bonds can easily zap equity markets as capital flows from stocks to bonds.
- The bigger question is whether this is a ‘right now’ thing or a 2027/2028 theme.
To be sure, higher rates aren’t necessarily a stimulus for corporates. The more unfriendly backdrop does create greater competition for capital, which, in-turn, both erodes profitability and limits expansion potential.
The opposite is easier to digest as low rates make for a far more friendly backdrop, helping companies to borrow capital more cheaply which they can then use to build their businesses. Another effect of that is that lower rate environments make bonds a less attractive medium, and investors are then more incentivized to take on greater risk in an equity investment as opposed to buying a bond that might barely yield above inflation rates.
While these relationships are clear and obvious and even logical, the more confounding part is the in-between periods, because like many other aspects of market dynamics the regime change isn’t always perfect. And, often, there’s an awkward period where one side or the other is going against the grain.
And, realistically, higher yields aren’t necessarily a death-knell for stocks. If we’re in a higher growth backdrop, that will probably come along with higher levels of inflation. And while the common relationship there is higher levels of inflation bringing rate hikes, more reasonably, it’s what actual markets are doing rather than central banks as holding long-term debt makes less sense in a higher inflation backdrop. That leads to greater supply at current rates, and greater supply and lower prices then means higher yields.
It’s easy to look back at this historically and assume the Fed’s function is the big connection point but the reality is it is probably more of a byproduct than anything. And, like we saw in the year 2000, it can fast become problematic. But this is yet another factor that has an inconsistent impact on market behaviors as it just depends on a litany of other factors.
We’re at one of those awkward periods right now as bond yields have continued to jump and, at this point, stocks seem to not care all too much. We have fresh multi-decade highs across the long end of the Treasury curve and both the Nasdaq and S&P 500 set fresh all-time-highs just two days ago. This seems to confound many headline writers as the less friendly corporate backdrop seemingly should make for a less friendly equity market. But, the reality is they’re two entirely different things.
In the Q4 forecasts I looked at a melt up scenario for both indices and I think that holds as we go into the end of the year. To be sure, as I’ve been writing for years now, I do think there is an AI bubble. The parallels to the dot com bubble are quite glaring, even if the sample size is just one. But, like the tech bubble, knowledge of there being a bubble doesn’t necessarily mean that you can perfectly time its popping. And that is where we are at today.
Q4 Forecast for Equities
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of Forex.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
S&P 500 The Road Ahead
The rally on Wednesday fell just short of the 7900 level and when a psychological level of that nature almost comes into play, it paints a picture that the market was overweight with longs and buyer trepidation took over before a test of the big figure. It also paints a picture that’s more of a pullback rather than a reversal, but it’s how the week finishes that will matter as an extended upper wick on a closed weekly bar does not bode well for near-term bullish continuation.
But, at this point, there’s a big level of prior resistance in play at 7782.50, and the 8k level overhead is probably the bigger item as we trade deeper into Q4.
S&P 500 Daily Price Chart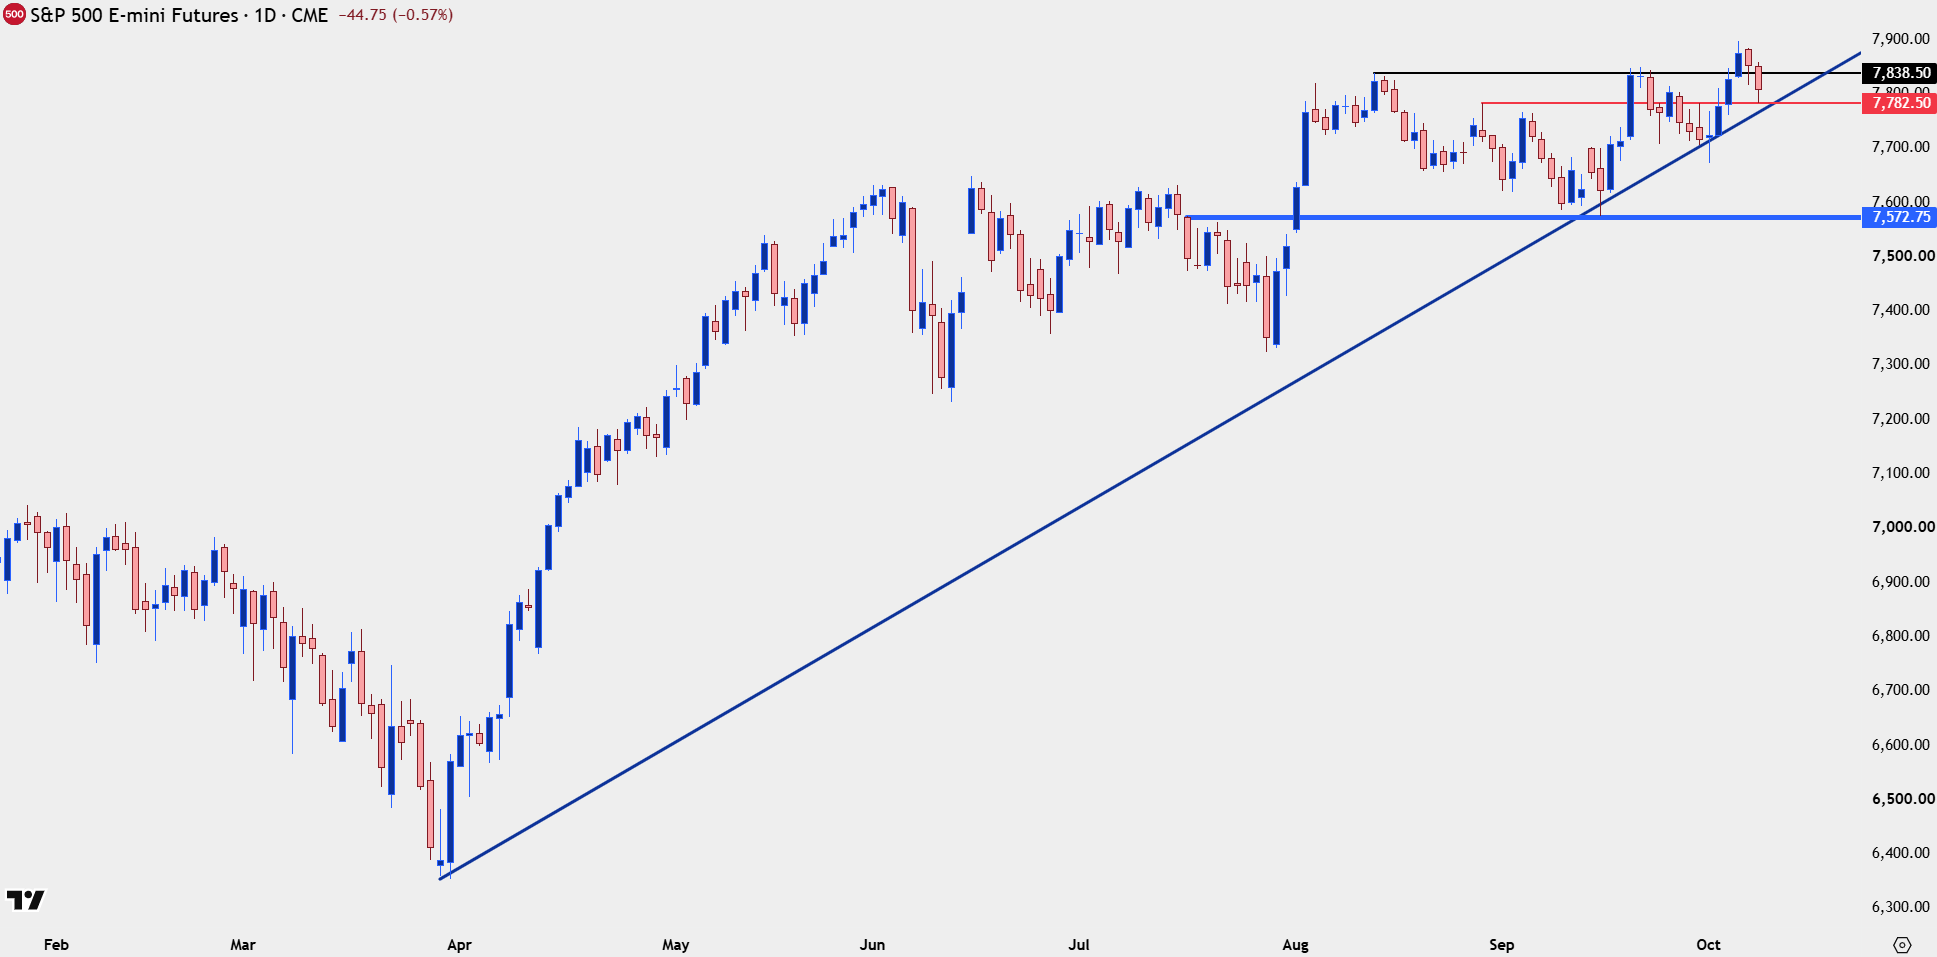
Chart prepared by James Stanley; data derived from Tradingview
S&P 500 Shorter-Term
From the shorter-term look there’s a similar structure in place given the drawdown from the Wednesday highs, and that takes on the form of a bull flag. There was another of those set up into last Friday, which led into the breakout that eventually drove to a fresh ATH this week.
Regarding levels from this structure: Key resistance is the 7838-7848 zone which was resistance in September and then again last week. Bulls still haven’t gained acceptance above this zone so it remains a significant spot on the chart. A closed body break of that zone also illustrates bull flag breakouts and bullish continuation scenarios.
As of this writing, price is testing another key zone spanning from 7798-7808, as this was prior resistance and currently is being tested as support. Below that, it’s the 7782 level that stands out, followed by the zone from 7761-7766. A break of that opens the door for a re-test of 7716-7724.
S&P 500 30-Minute Chart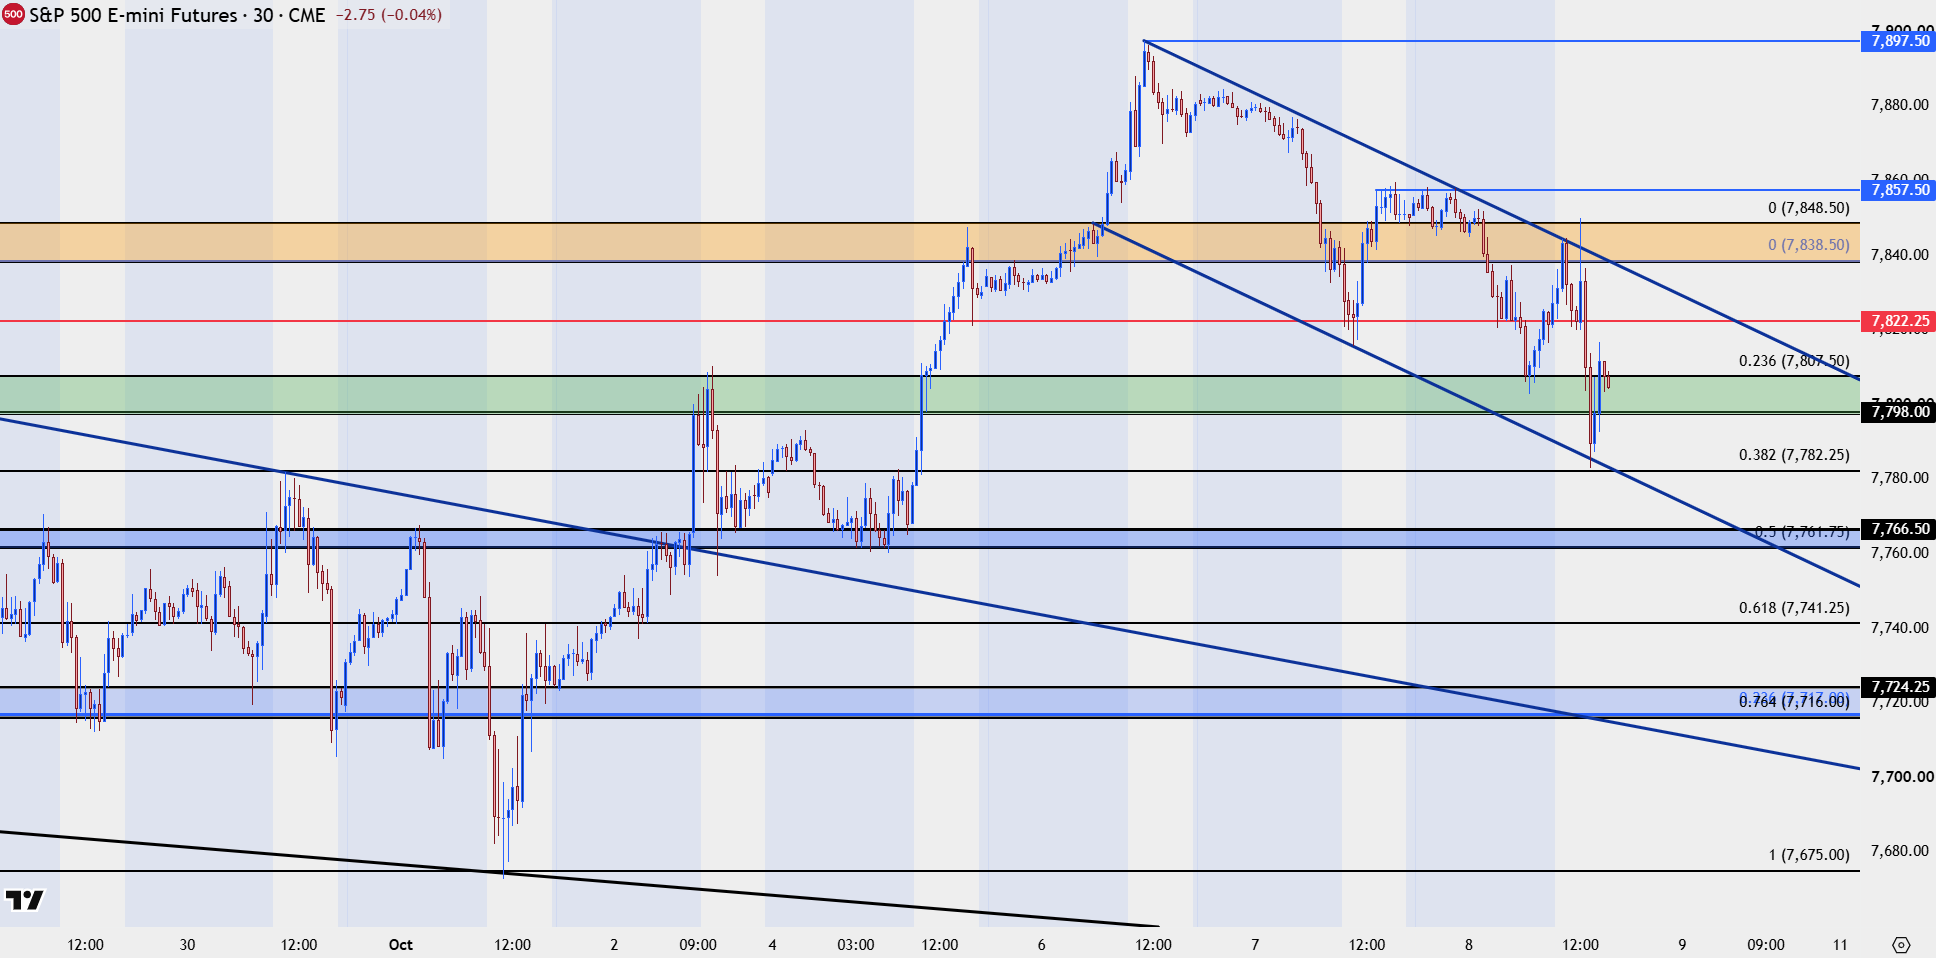
Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Market Analyst, Global Macro
Related tags:
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Pulls Back From Another Fresh ATH As Yields Soften
Both the S&P and Nasdaq set fresh ATHs on Wednesday, and despite relief in yields, stocks are pulling back again today.
Gold Bounces From Lows But Are Brighter Days Ahead?
Gold put in a sizable underside wick on the daily chart yesterday and this speaks to the possibility of near-term bottoming in the metal following a strong sell-off over the past six weeks.
Bitcoin Back to a Familiar Support Level: BTC/USD Levels
Bitcoin has retained strength through the jump in yields even as gold has melted down, but now BTC/USD faces an important test as price has reverted to a significant support level.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.