



Market Brief BoJos Brexit Setback Hits Sterling
See a summary of the top market themes and trends from today's US trading session!
Share this:

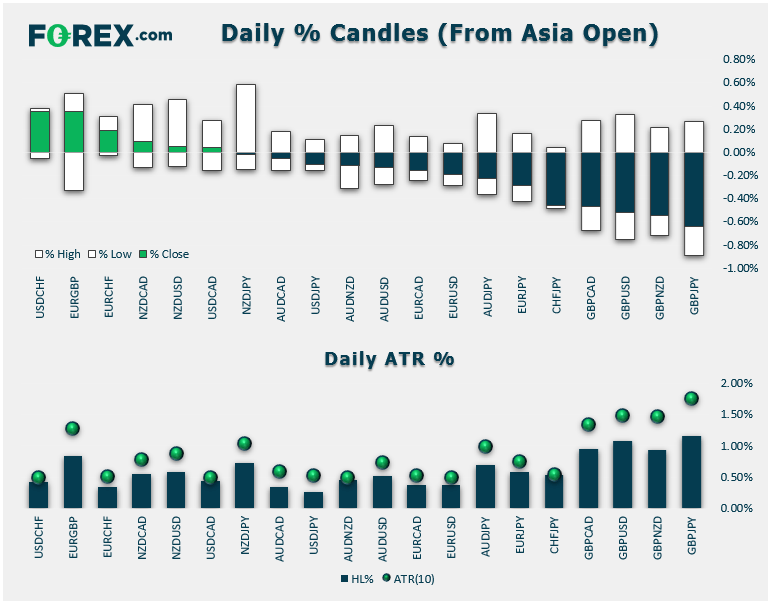
View our guide on how to interpret the FX Dashboard.
- Parliament voted down Boris Johnson’s Brexit “programme motion timetable” 322-308, meaning that the PM must request an extension, which the EU is likely to grant. Johnson has been outspoken that he still intends to have the UK leave the EU by the end of the month, though he may accept a “technical” extension to work out any sticking points.
- FX: The yen was the day’s strongest major currency after a late shift to risk-off trading. The pound was the day’s weakest major currency.
- The Canadian dollar initially ticked lower as traders digested the result of last night’s election, but the currency ultimately finished in the middle of the major currency pack, helped along by rising oil prices.
- US Data: Second-tier reports were mixed, with the Richmond Fed survey beating expectations but existing home sales coming in a bit soft.
- Commodities: Oil gained nearly 2% on the day on a report that OPEC was considering deeper production cuts at its December meeting due to weaker global demand forecasts. Gold was essentially flat.

- US indices closed marginally lower on the day, with the tech-heavy Nasdaq leading the late afternoon selloff.
- Energy stocks (XLE) were the strongest major sector again today, while Technology (XLK) brought up the rear.
- Stocks on the move:
- Biogen (BIIB) exploded 26% higher after the company found data to help revive a potential blockbuster Alzheimer drug.
- McDonalds (MCD) shed -5% after missing earnings estimates for the first time in two years before the bell today.
- Facebook (FB) fell -4% on the day as more states joined an antitrust probe against the company. Now, 45 states, Guam, and the District of Columbia are working with the New York-led investigation. The company reports earnings next week.
- Procter & Gamble (PG) gained 3% after the company reported solid earnings and raised its guidance for 2020.
- Toy maker Hasbro (HAS) shed -17% after reporting disappointing earnings on the back of US-China trade tensions.
- Under Armour (UA) rose 7% on news that the company’s long-time CEO Kevin Plank was stepping down.
- Snapchat (SNAP) reported a loss after the bell today. The stock is trading -4% lower in volatile after hours trade as of writing.
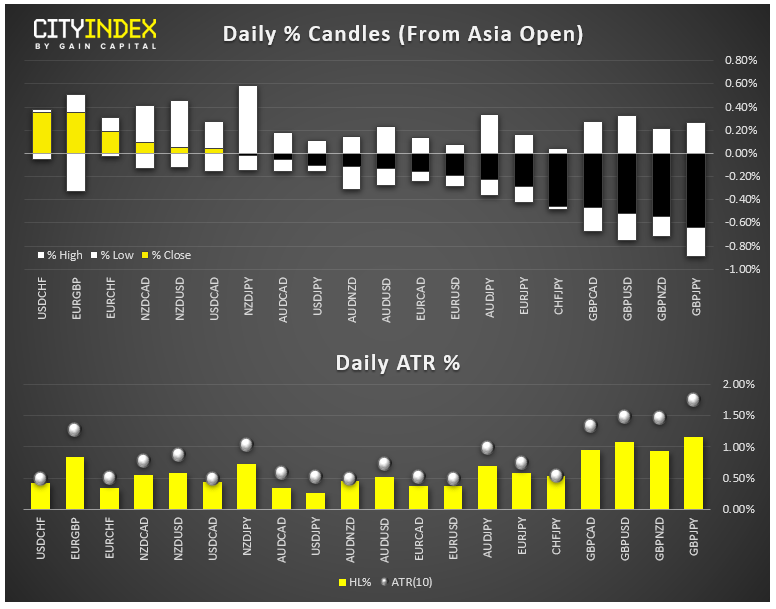
View our guide on how to interpret the FX Dashboard.
- Parliament voted down Boris Johnson’s Brexit “programme motion timetable” 322-308, meaning that the PM must request an extension, which the EU is likely to grant. Johnson has been outspoken that he still intends to have the UK leave the EU by the end of the month, though he may accept a “technical” extension to work out any sticking points.
- FX: The yen was the day’s strongest major currency after a late shift to risk-off trading. The pound was the day’s weakest major currency.
- The Canadian dollar initially ticked lower as traders digested the result of last night’s election, but the currency ultimately finished in the middle of the major currency pack, helped along by rising oil prices.
- US Data: Second-tier reports were mixed, with the Richmond Fed survey beating expectations but existing home sales coming in a bit soft.
- Commodities: Oil gained nearly 2% on the day on a report that OPEC was considering deeper production cuts at its December meeting due to weaker global demand forecasts. Gold was essentially flat.

- US indices closed marginally lower on the day, with the tech-heavy Nasdaq leading the late afternoon selloff.
- Energy stocks (XLE) were the strongest major sector again today, while Technology (XLK) brought up the rear.
- Stocks on the move:
- Biogen (BIIB) exploded 26% higher after the company found data to help revive a potential blockbuster Alzheimer drug.
- McDonalds (MCD) shed -5% after missing earnings estimates for the first time in two years before the bell today.
- Facebook (FB) fell -4% on the day as more states joined an antitrust probe against the company. Now, 45 states, Guam, and the District of Columbia are working with the New York-led investigation. The company reports earnings next week.
- Procter & Gamble (PG) gained 3% after the company reported solid earnings and raised its guidance for 2020.
- Toy maker Hasbro (HAS) shed -17% after reporting disappointing earnings on the back of US-China trade tensions.
- Under Armour (UA) rose 7% on news that the company’s long-time CEO Kevin Plank was stepping down.
- Snapchat (SNAP) reported a loss after the bell today. The stock is trading -4% lower in volatile after hours trade as of writing.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Canadian Dollar Analysis: USD/CAD Returns to July Highs Ahead of NFP
The Canadian dollar continues to face one of its most challenging environments in recent months when it comes to maintaining strength against the U.S. dollar. The weakness of the Canadian currency is clearly reflected in USD/CAD, which has now recorded nine consecutive bullish sessions and gained more than 1.7% during that period.
US Dollar Technical Outlook: DXY Bulls Meet Resistance at Yearly Highs 10 1 2026
The U.S. Dollar has held firm despite fading Fed hike bets, but Friday’s payrolls could test the rally’s staying power.


Dow Jones forecast: Stock markets under pressure from multiple sources
When looking at the major tech-heavy US indices like the S&P 500 or the Nasdaq 100, you wouldn’t think that the stock market is particularly weak. Yet, beneath the surface, the market is far from healthy right now. Investors are evidently just piling into the big tech and AI names, and as a result, market breadth is deteriorating. Other indices like the small cap Russell 2000 and the Dow Jones are starting to reflect that weakness.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.