



Market Brief Bulls on Parade Following Phase One USChina Trade Deal
See a summary of the top market themes and trends from today's US trading session!
Share this:

- Risk assets exploded higher today as the US and China signed a “Phase One” trade deal, with President Trump stating that the deal covers intellectual property, financial services, and agricultural purchases. Technology transfers are reportedly up for discussion in Phase Two when US official visit China next month. As of writing, there’s no clarity on whether scheduled tariffs on Chinese goods will be enacted as scheduled.
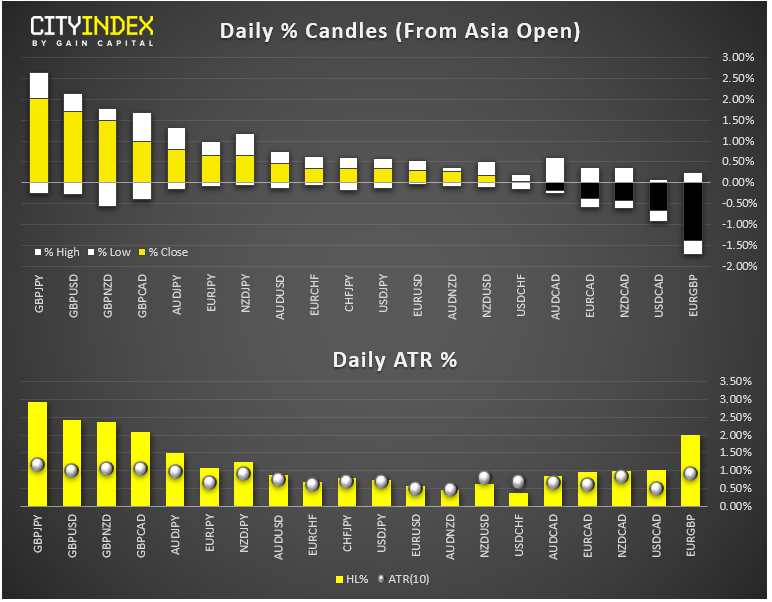
- FX: The British pound surged against all of its major rivals for the second straight day as the EU and UK agreed to “intensify discussions over the coming days” ahead of next week’s highly-anticipated EU Summit. The safe haven Japanese yen was the weakest major currency in generally optimistic trade, taking USD/JPY to its highest level since August 1.
- The loonie was the day’s second-strongest major currency after a much stronger-than-expected jobs report, which showed 53.7k new jobs created and the unemployment rate dropping to 5.5%, within a tick of the multi-decade low set earlier this year. Traders will no doubt pare back their expectations for a BOC interest rate cut later this month after such a strong report.
- US data: The UofM Consumer Sentiment index recovered to 96.0 (vs. 92.0 eyed), though longer-term inflation expectations nonetheless fell to a record low. Separately, the Federal Reserve announced $60B in monthly purchases of short-term Treasury bills.
- Commodities: Oil gained more than 2% on the day (see the key events and themes we’ll be watching next week), while gold shed roughly -1%.
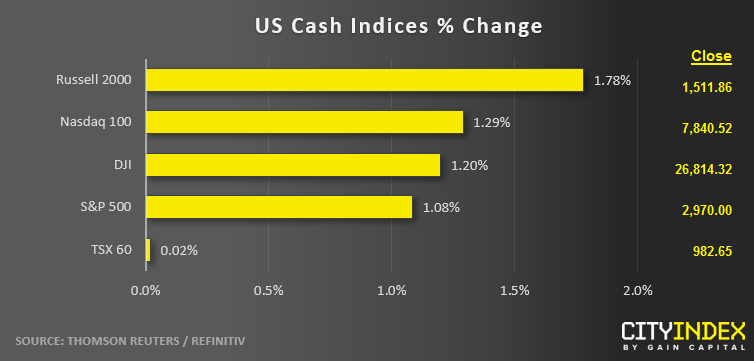
- US indices closed sharply higher on trade deal optimism (growing odds of a Brexit deal didn’t hurt), with all major bourses rising roughly 1.5% on the day.
- All eleven sectors rose on the day led by Industrials (XLI) and Materials (XLB). Utilities (XLU) rose the least.
- Stocks on the move:
- Apple (AAPL) rose 3% on the day to hit a fresh record high as analysts at Wedbush raised their price target for the stock to $265.
- Bed Bath and Beyond (BBBY) tacked on another 8% today after appointing a former Target executive as its new CEO.
- Check out the major macroeconomic events and trends we’ll be watching in the week to come!
*No major economic data is scheduled for release during Monday’s Asian session (though traders should keep an eye out for Chinese trade balance figures (no set release schedule) *
- Risk assets exploded higher today as the US and China signed a “Phase One” trade deal, with President Trump stating that the deal covers intellectual property, financial services, and agricultural purchases. Technology transfers are reportedly up for discussion in Phase Two when US official visit China next month. As of writing, there’s no clarity on whether scheduled tariffs on Chinese goods will be enacted as scheduled.
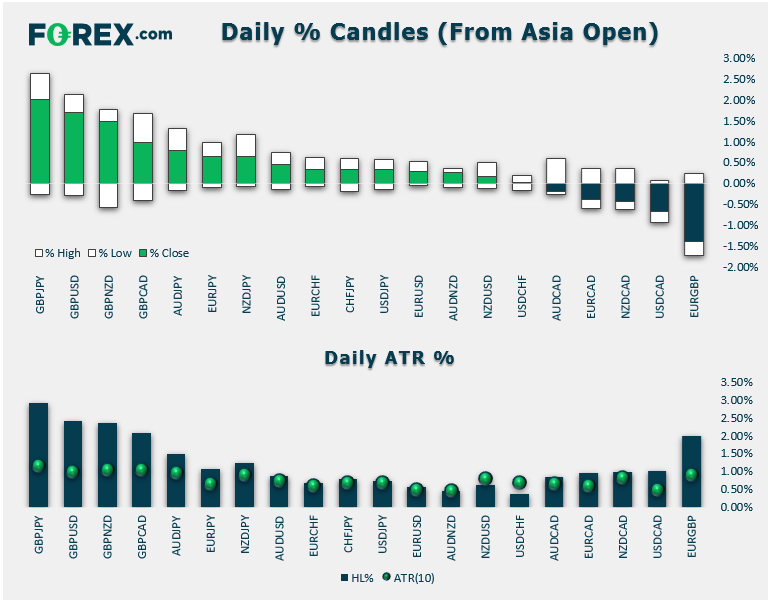
- FX: The British pound surged against all of its major rivals for the second straight day as the EU and UK agreed to “intensify discussions over the coming days” ahead of next week’s highly-anticipated EU Summit. The safe haven Japanese yen was the weakest major currency in generally optimistic trade, taking USD/JPY to its highest level since August 1.
- The loonie was the day’s second-strongest major currency after a much stronger-than-expected jobs report, which showed 53.7k new jobs created and the unemployment rate dropping to 5.5%, within a tick of the multi-decade low set earlier this year. Traders will no doubt pare back their expectations for a BOC interest rate cut later this month after such a strong report.
- US data: The UofM Consumer Sentiment index recovered to 96.0 (vs. 92.0 eyed), though longer-term inflation expectations nonetheless fell to a record low. Separately, the Federal Reserve announced $60B in monthly purchases of short-term Treasury bills.
- Commodities: Oil gained more than 2% on the day (see the key events and themes we’ll be watching next week), while gold shed roughly -1%.
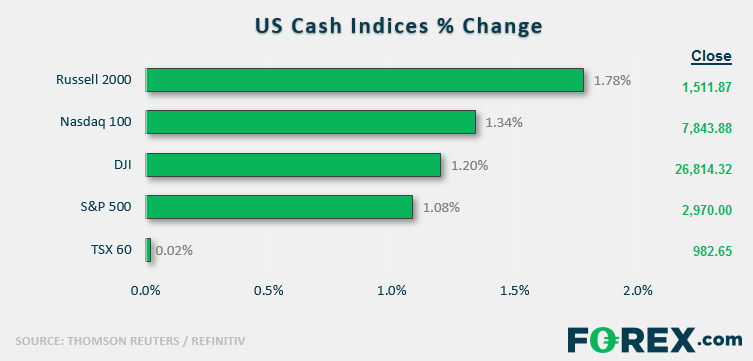
- US indices closed sharply higher on trade deal optimism (growing odds of a Brexit deal didn’t hurt), with all major bourses rising roughly 1.5% on the day.
- All eleven sectors rose on the day led by Industrials (XLI) and Materials (XLB). Utilities (XLU) rose the least.
- Stocks on the move:
- Apple (AAPL) rose 3% on the day to hit a fresh record high as analysts at Wedbush raised their price target for the stock to $265.
- Bed Bath and Beyond (BBBY) tacked on another 8% today after appointing a former Target executive as its new CEO.
- Check out the major macroeconomic events and trends we’ll be watching in the week to come!
*No major economic data is scheduled for release during Monday’s Asian session (though traders should keep an eye out for Chinese trade balance figures (no set release schedule) *


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.


USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.


Canadian Dollar Analysis: USD/CAD Returns to July Highs Ahead of NFP
The Canadian dollar continues to face one of its most challenging environments in recent months when it comes to maintaining strength against the U.S. dollar. The weakness of the Canadian currency is clearly reflected in USD/CAD, which has now recorded nine consecutive bullish sessions and gained more than 1.7% during that period.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.