


Nasdaq 100 Forecast: The index pulls back from all-time highs ahead of the FOMC
The start of the week has been challenging for Nasdaq 100 price action in the short term, mainly due to a mild pullback from all-time highs. Over the past two trading sessions, the index has posted a decline of around 1.00%, reflecting a loss of bullish momentum.
Share this:
The start of the week has been challenging for Nasdaq 100 price action in the short term, mainly due to a mild pullback from all-time highs. Over the past two trading sessions, the index has posted a decline of around 1.00%, reflecting a loss of bullish momentum.
For now, this selling pressure appears to be driven by market expectations ahead of the Federal Reserve’s upcoming decision, as well as the start of earnings season for major technology companies. Both factors could shift market sentiment and lead to a more pronounced phase of indecision in the short term.


What to expect from the central bank?
On April 29, the Federal Reserve will announce its interest rate decision. According to CME Group data, there is a near 100% probability that the central bank will keep rates unchanged within the 3.50% - 3.75% range, meaning no major surprises are expected from the decision itself.
However, market focus will be on the post-decision commentary, which could confirm expectations of prolonged rate stability throughout 2026.
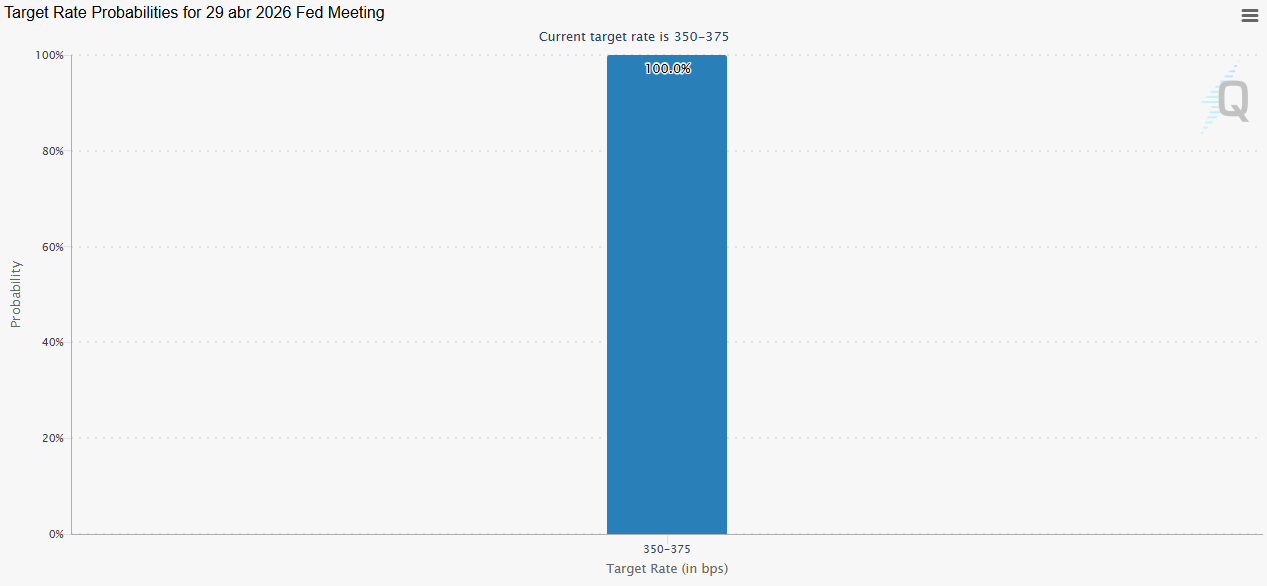
Source: CMEGROUP
This environment is already being reflected in the US Treasury market, which is often seen as a substitute for equity indices. In particular, the 10-year yield has resumed an upward trend, moving back above the 4.3% level, indicating that the market is already pricing in stable rates.
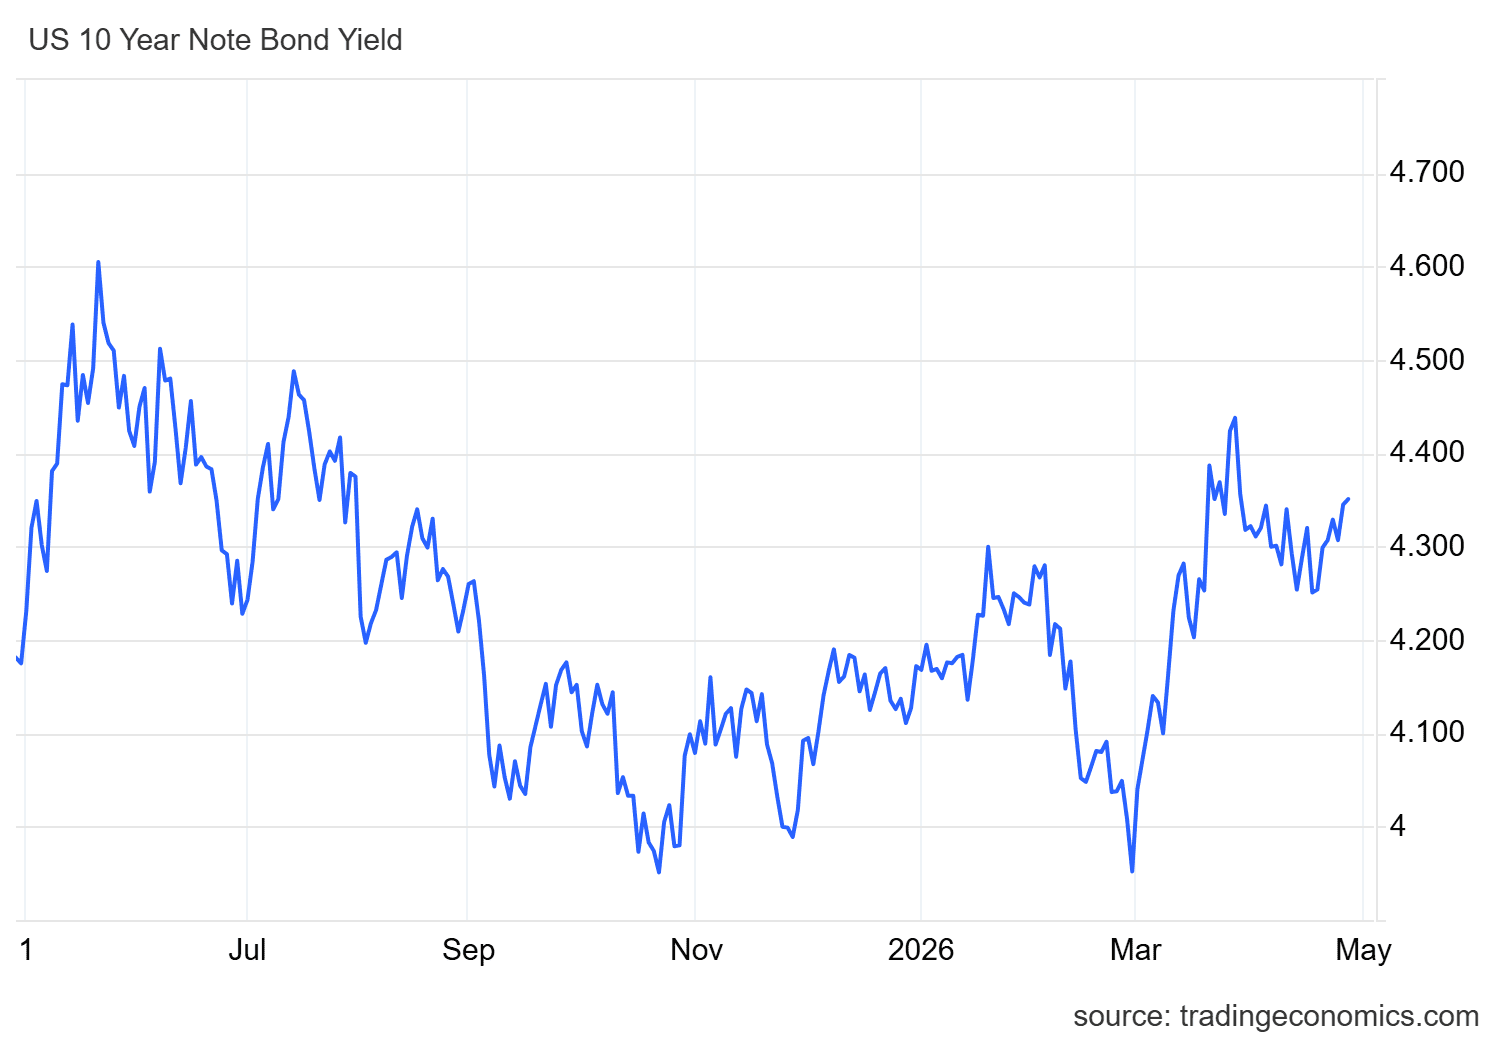
Source: TradingEconomics
This dynamic is important because higher bond yields tend to reduce the attractiveness of risk assets such as equities. Bonds offer relatively stable returns, while stocks depend on economic growth and earnings expectations.
Additionally, a higher-for-longer rate environment can weigh on consumption and financing conditions, which may eventually impact the growth outlook for technology companies.
In this context, part of the Nasdaq’s current neutrality may be tied to monetary policy expectations. If the market continues to price in stable rates for longer, and bond yields keep rising, this could continue to limit buying strength in the index in the coming sessions.
What to expect from earnings?
This week is also key due to earnings releases from four of the largest companies within the Nasdaq 100, which could be decisive for short-term market confidence.
Microsoft, Amazon, and Alphabet will report on April 29 after market close, while Apple will release results on April 30. Expectations are as follows:
- Microsoft: EPS of $4.07 vs $3.46 in the same period last year.
- Amazon: EPS of $1.60 vs $1.59 in the same period last year.
- Alphabet: EPS of $2.64 vs $2.81 in the same period last year.
- Apple: EPS of $1.92 vs $1.65 in the same period last year.
The key takeaway is that, in most cases, the market expects solid earnings growth compared to the previous year, keeping optimism alive within the tech sector.
However, market reaction will depend not only on whether expectations are met, but on whether companies are able to exceed them. Strong results could reignite buying confidence and support further upside in Nasdaq. On the other hand, mixed or disappointing results could reinforce the current indecision or even trigger a deeper short-term correction.
Technical outlook for the Nasdaq 100
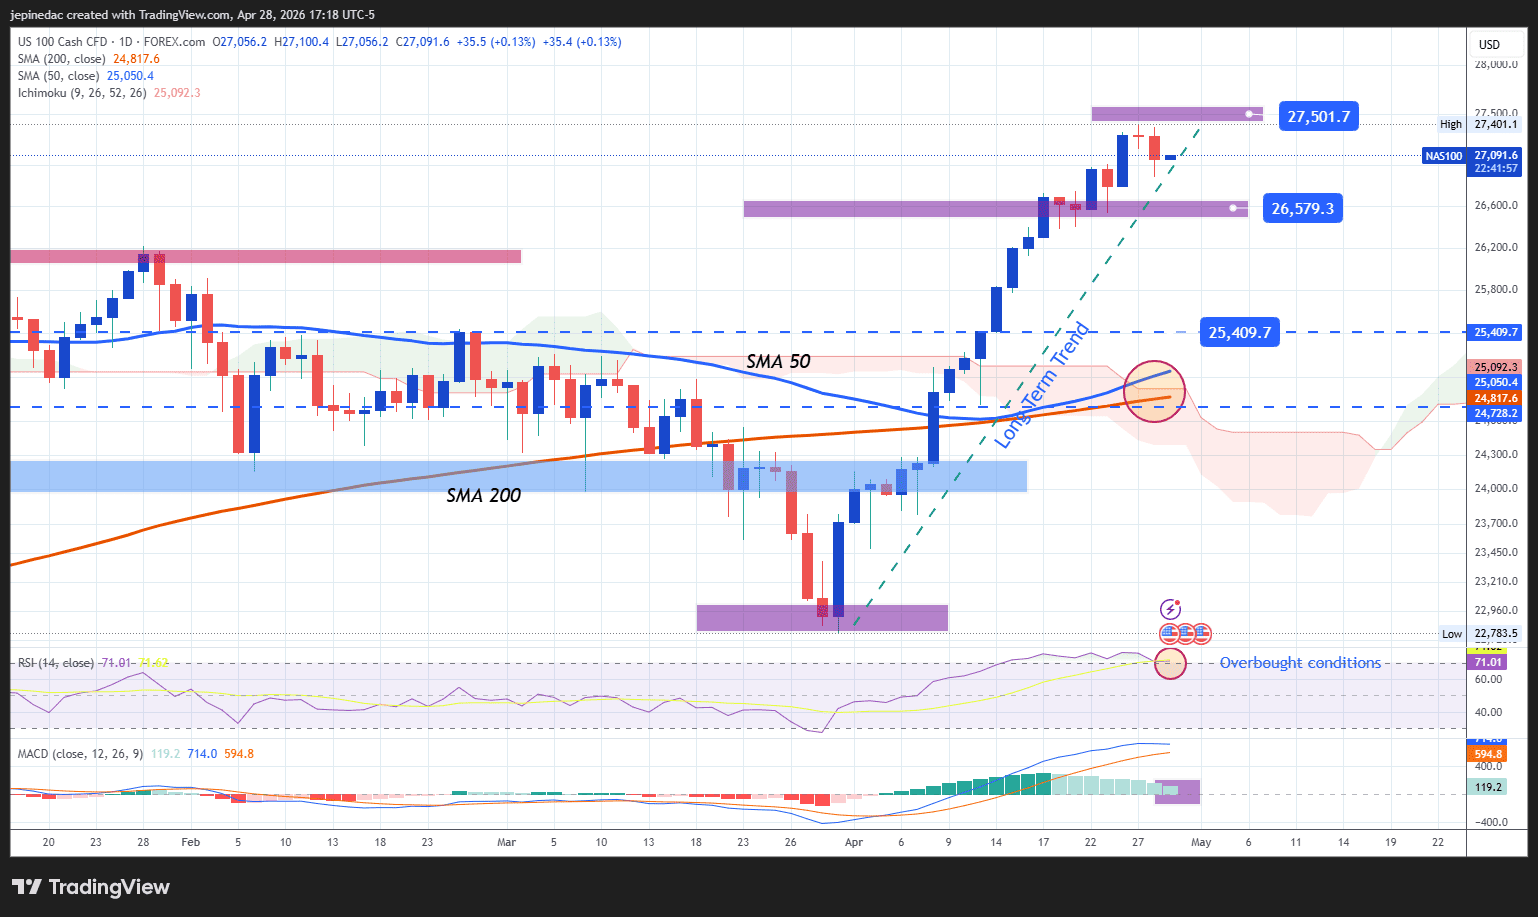
Source: StoneX, Tradingview
- Short-term trendline under pressure: The recovery seen in recent weeks allowed for the formation of a short-term upward trendline. However, recent pullbacks from all-time highs have started to question the strength of this structure. If buying pressure fails to regain control, a break below this trendline could lead to a broader correction phase or a more defined sideways environment in the short term.
- MACD: The MACD histogram is once again approaching the zero line, reflecting a loss of bullish momentum. This suggests that the recent rally is beginning to fade and that indecision may become more dominant in the coming sessions.
- RSI: The RSI is flattening near overbought levels (around 70), indicating that bullish momentum has been strong, but also highlighting an increasing risk of correction due to overstretched price action.
Key levels:
- 27,500 points – Key resistance: With no historical references above current levels, this stands as the main psychological barrier. A sustained break above this level could reactivate the dominant bullish bias and support further upside.
- 26,579 points – Near-term barrier: A level of recent lows acting as immediate support. Price action around this zone could determine whether the current correction remains limited or deepens further.
- 25,400 points – Key support: A zone of previous weekly lows. A move toward this level could invalidate the recent bullish structure and open the door to a more structured correction phase or a more prolonged period of indecision in the coming weeks.
Written by Julian Pineda, CFA, CMT – Market Analyst
Follow him on: @julianpineda25
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100 forecast: Tech stocks rebound but AI concerns linger
The Nasdaq 100 rebound has run into former support as fears over AI regulation and spending linger. Fawad Razaqzada explains why he maintains a cautious forecast and where the key levels sit.

Nasdaq Sell-Off Exposes the Hidden Gap in AI Profits
The Nasdaq sell-off deepened as doubts over AI spending, weak chip earnings and the threat of tighter AI regulation hit U.S. tech stocks.
Nikkei 225 bear market deepens as volatility surges
The Nikkei has entered a technical bear market following a historic plunge. RSI and ATR stretch readings suggest a bounce may be coming, but history carries a warning for dip buyers.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.