



NZD/USD Forecast: A Good Rise in Unemployment
Rising unemployment in New Zealand masks firmer labour market conditions, keeping the RBNZ sidelined and NZD/USD consolidating.
Share this:
- New Zealand unemployment lifts for good reason
- Employment growth beats forecasts
- Wage pressure remains weak, capping RBNZ rate hike risk
- NZD/USD holds above 0.6000
Summary
New Zealand’s labour market is improving beneath the surface, with stronger employment and rising participation driving a “good” rise in unemployment. Slack remains elevated and wage pressures muted, keeping RBNZ pricing relative unchanged, leaving the kiwi more sensitive to shifts in risk appetite and US economic data.
“Good” unemployment rise, slack lingers
New Zealand’s unemployment rate rose to 5.4% in the December quarter, up from 5.3% previously, but the increase largely reflected improving labour market dynamics rather than renewed deterioration. Employment grew by 0.5%, well above the RBNZ’s November forecast of a 0.2% gain, marking the first quarterly increase since mid-2024. The employment rate edged higher to 66.7%, while labour force participation rose to 70.5%, also exceeding the Bank’s expectations.
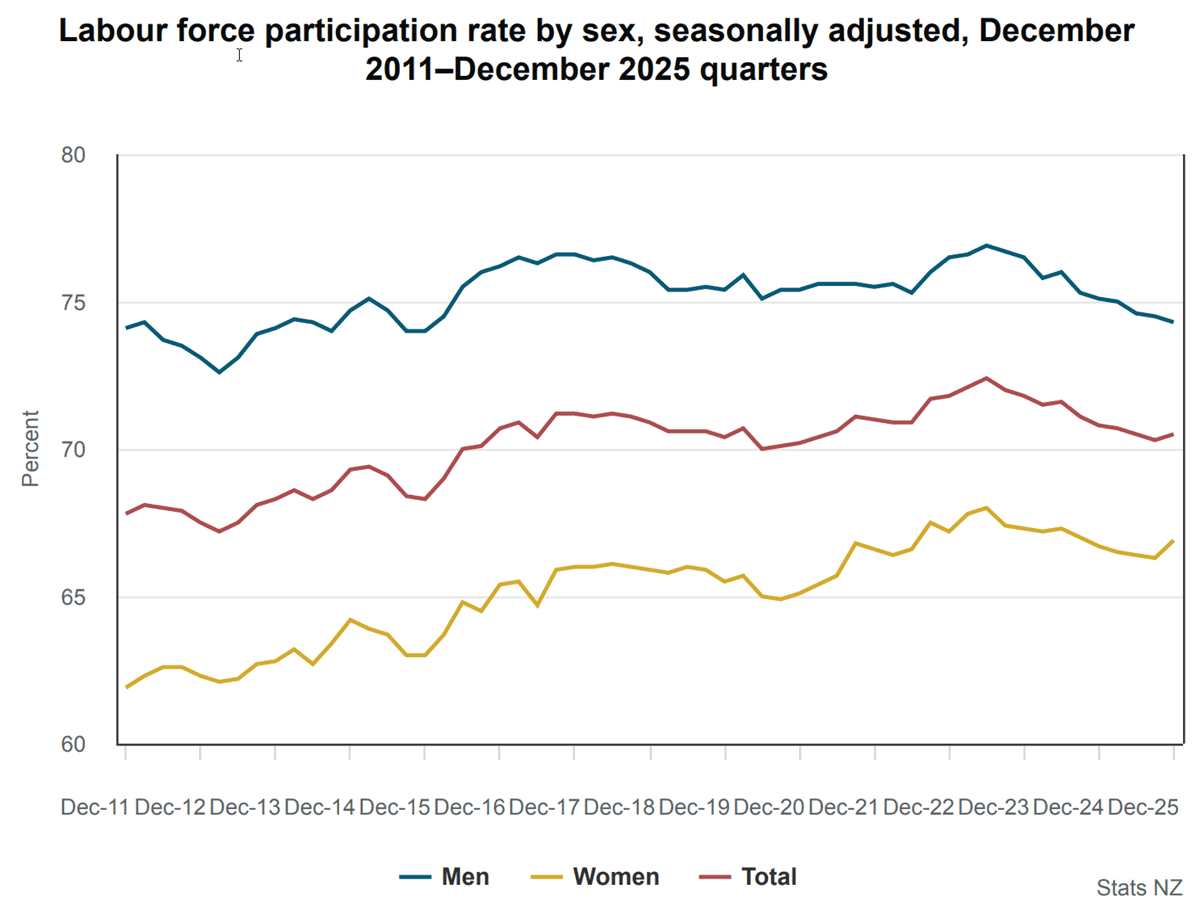
Source: StatsNZ
Despite the stronger hiring backdrop, the rise in participation meant labour supply again outpaced demand. As a result, the number of unemployed increased to 165,000, even as underlying conditions improved. Broader slack measures were stable, with the underutilisation rate unchanged at 13.0%, while youth labour market conditions showed modest improvement, with the NEET rate falling to 13.2% from 13.7%.
Importantly, wage pressures remained subdued. Private sector labour cost growth rose 0.5% quarter-on-quarter, exactly in line with RBNZ forecasts, leaving annual wage inflation at 2%, consistent with lingering excess capacity.
The broader message is that while the New Zealand labour market is showing early signs of stabilisation, the accumulated slack built up over recent years remains substantial. Labour supply is still not being absorbed quickly enough to prevent a modest rise in unemployment, keeping wage pressures contained, domestic inflation risks muted, and limiting, for now, the risk of near-term rate hikes from the RBNZ.
Hiring up, hikes on hold
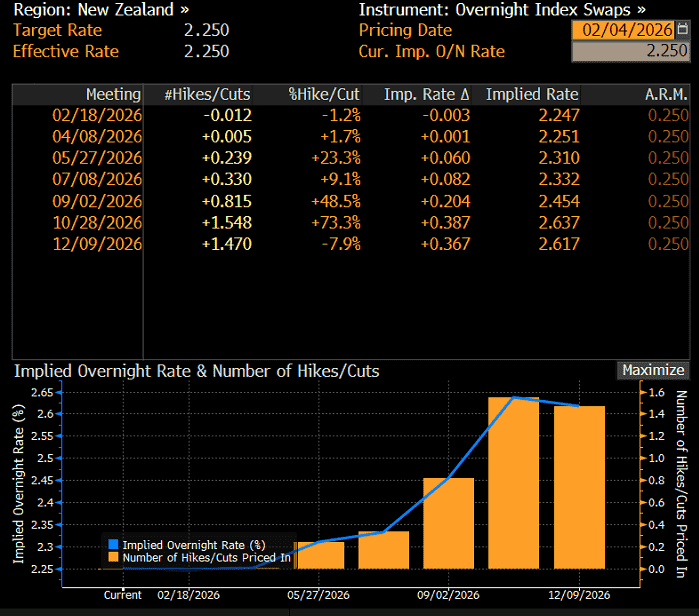
Source: Bloomberg
That backdrop helps explain why markets remain in no rush to price a policy response from the RBNZ. As things stand, swaps are not fully priced for the first 25bp hike of the cycle until October, with the risk of a second move by that meeting seen as little more than a coin flip. By the RBNZ’s July meeting, the implied probability of a hike sits at just 33%.
Given emerging signs of a pickup in inflationary pressures in New Zealand, which remains the RBNZ’s sole mandate, that degree of caution looks questionable. The risk of a move as early as July still looks underpriced, particularly with a large share of fixed-rate mortgages set to roll off into a materially lower interest rate environment following 225 basis points of easing from the RBNZ, lifting household disposable incomes and potentially adding to demand.
NZD/USD steadies above 0.6000
Source: TradingView
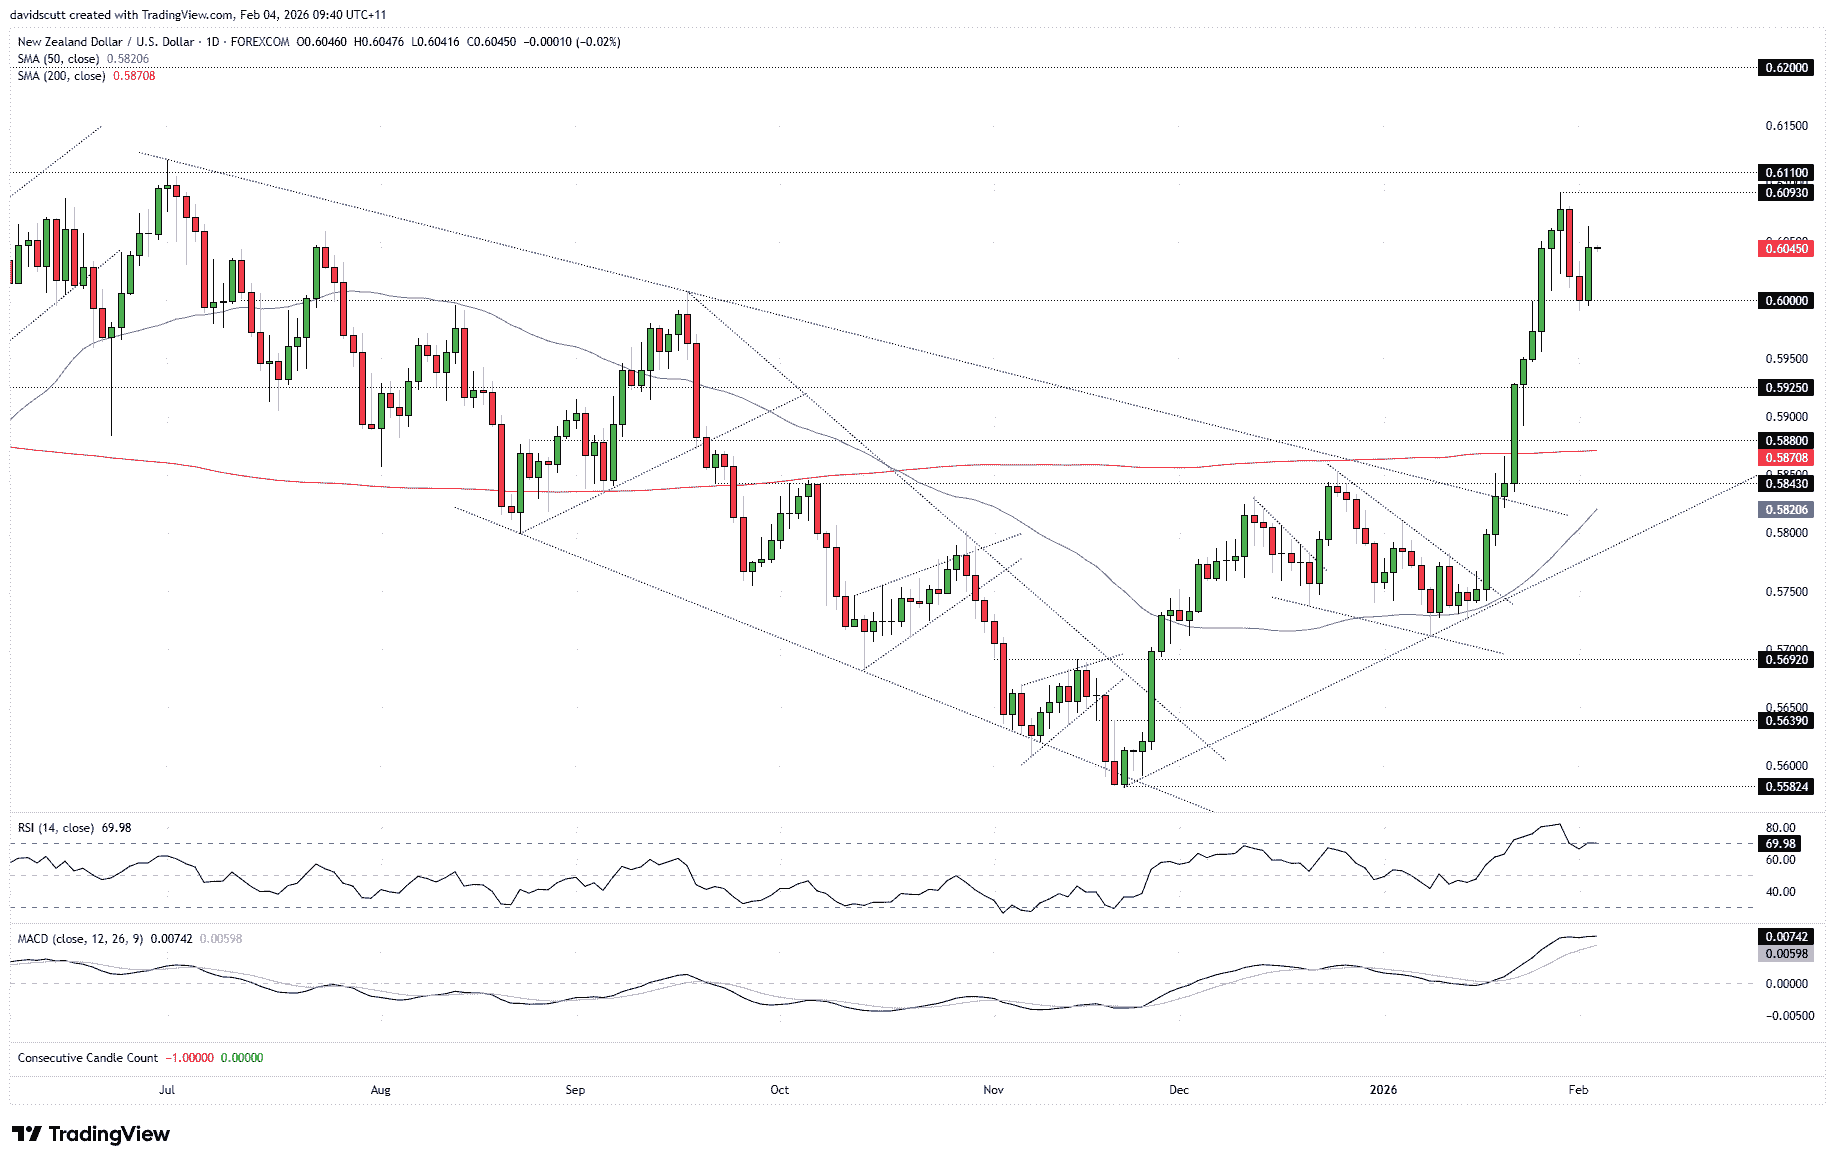
Against that backdrop, NZD/USD looks to be in the process of carving out a new sideways range following the bullish breakout seen in January. Support has held around 0.6000, with last week’s high at 0.6093 the near-term focus on the topside, ahead of layered resistance just above 0.6110.
After a brief moderation in upside pressure following a push into overbought territory, momentum is showing signs of turning higher again, favouring a similar directional bias when it comes to setup selection. A clear break and close above 0.6110 would open the door to a potential move towards 0.6200, with the September 2024 high at 0.6379 the next notable topside reference beyond that.
On the downside, a clean break beneath 0.6000 support would shift focus back towards 0.5925 and 0.5880, with the 200-day moving average also coming into view.
Beyond the technicals, risk appetite has been an important driver for the kiwi in recent sessions, at times showing very strong correlations with markets such as gold and silver. As such, broader risk conditions remain important when considering trade setups. US economic data also matters, particularly given the reasonably strong relationship seen recently between short-dated US–New Zealand yield differentials and NZD/USD.

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.

Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.


EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.