


S&P 500 forecast: Investors weigh hawkish Fed against weak oil prices
Following the sharp post-Federal Reserve sell-off, global equity markets staged a recovery overnight. US futures moved higher alongside stronger European indices, before coming off their highs. Continued dollar strength maintained pressure on precious metals and several major currencies.
Share this:
Following the sharp post-Federal Reserve sell-off, global equity markets staged a recovery overnight. US futures moved higher alongside stronger European indices, before coming off their highs. Continued dollar strength maintained pressure on precious metals and several major currencies. Our S&P 500 forecast has turned a little more cautious now. Investors are weighing enthusiasm around artificial intelligence-led growth and falling energy prices against a Federal Reserve that has clearly adopted a firmer policy stance. While policymakers remain divided over the need for further tightening this year, the latest meeting represented a notable departure from the more accommodative tone seen previously.
S&P 500 forecast: Crude oil weakness limit downside but correction risks increase
The recent collapse in oil prices offers an important offset. Should lower energy costs continue to filter through to inflation data, policymakers may ultimately find sufficient justification to keep rates unchanged for an extended period rather than resume tightening. Had it not been for the sharply lower oil prices, yesterday’s FOMC announcement would have triggered a much bigger slide in equity markets.
What is almost certain to happen now is that markets will become increasingly data-dependent once again. For now, equity bulls maintain some control. However, with valuations still elevated and a lack of obvious near-term catalysts, the prospect of profit-taking or a modest correction has become more plausible following the Fed’s hawkish pivot.
Warsh triggers hawkish repricing of US rates
Federal Reserve Chair Kevin Warsh’s first meeting at the helm delivered a message that markets interpreted as distinctly hawkish. The immediate consequence was a stronger US dollar and a period of weakness across risk assets before sentiment stabilised overnight.
The key driver of the reaction was the Fed’s renewed emphasis on inflation risks, reinforced by a more hawkish set of rate projections. Nine of the eighteen policymakers now expect at least one additional rate increase before year-end. The Fed is basically signalling a readiness to respond should inflationary pressures re-emerge.
With both the policy statement and subsequent press conference offering limited forward guidance, incoming economic releases are likely to carry greater weight in shaping market expectations over the months ahead.
My view remains that inflation should moderate gradually over the coming months, and this might allow the Fed to maintain current policy settings rather than implement fresh tightening.
Markets are currently pricing approximately 30 to 35 basis points of tightening this year, compared with less than 20 basis points prior to the latest FOMC meeting. Whether those expectations prove justified will depend heavily on forthcoming inflation data.
Europe holds steady
Meanwhile, European markets had a slightly more constructive session, even if gains have moderated from their intraday highs. Several major indices remain close to record territory, supported by a combination of softer energy prices, reasonably resilient economic data and growing confidence that central banks are approaching the end of their recent inflation-driven tightening bias.
While concerns over global growth have not disappeared entirely, investors appear increasingly willing to re-engage with risk assets. Continental European markets, in particular, continue to benefit from relatively attractive valuations compared with some international peers.
Provided energy prices remain contained and economic conditions avoid a meaningful deterioration, the region’s equity markets should continue to attract investor interest.
Falling crude keeps risk appetite intact
One of the most significant drivers behind the recent improvement in market sentiment has been the sharp decline in oil prices. Crude futures extended their losses for a sixth consecutive session, helping to reinforce expectations that inflationary pressures may continue to ease in the months ahead.
For investors, cheaper energy offers a double benefit. Lower input costs support corporate profitability, while reduced inflation risks lessen the likelihood of additional monetary tightening from major central banks. As a result, declining oil prices have become an increasingly important pillar supporting the broader equity rally.
Technical S&P 500 forecast
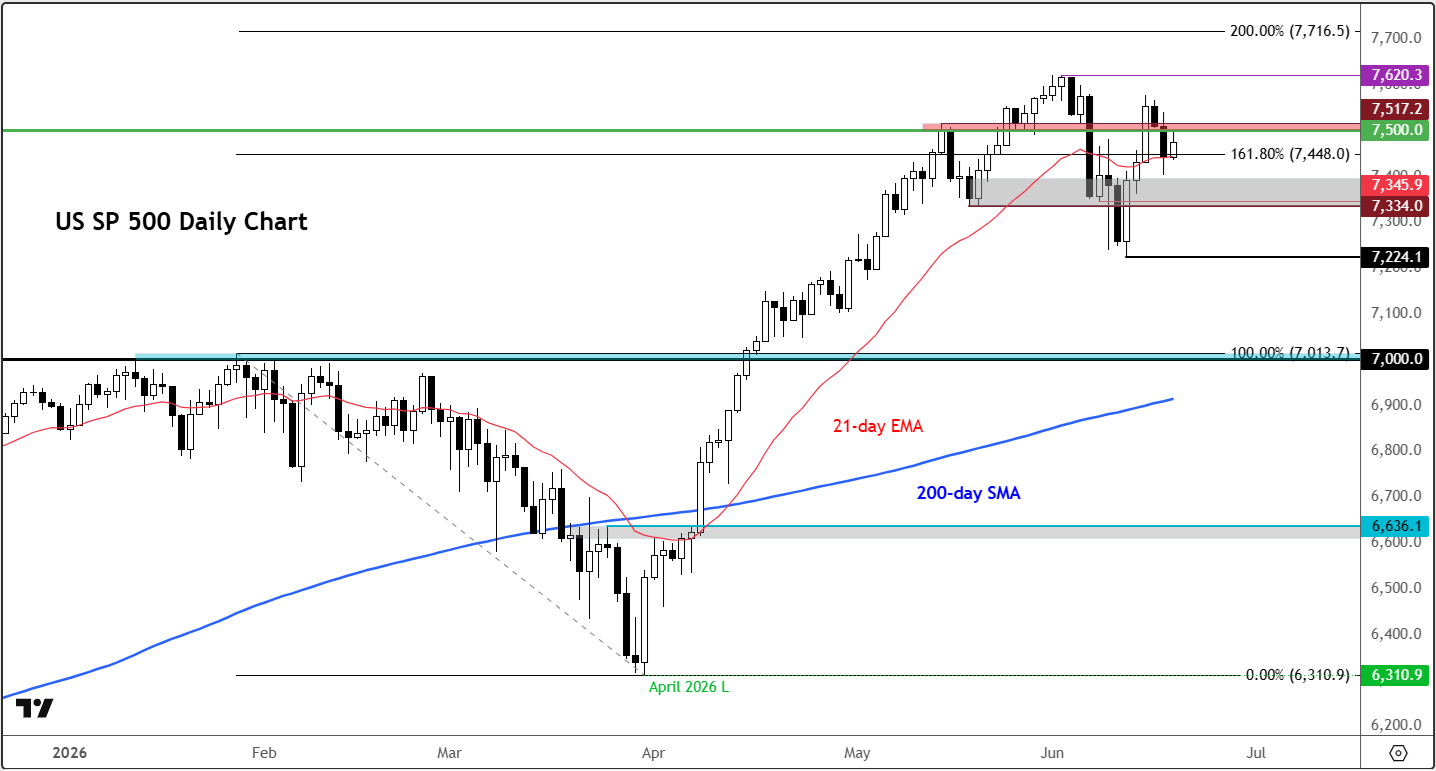
The rebound following the FOMC decision is encouraging for bulls, although our SPX500 chart, which tracks the underlying S&P 500 futures, now faces an important technical hurdle between 7,500 and 7,517. This zone previously acted as support and may now serve as resistance following the bearish reversal seen after the Fed meeting.
At present, the uptrend remains intact. However, confirmation of renewed weakness would require a decisive move back below yesterday’s low at least. Such a break could encourage a deeper pullback and shift short-term S&P 500 forecast in favour of sellers, in particular if 7334 also breaks.
A break beneath this area would materially weaken the technical outlook and expose the market to a move towards liquidity resting below last week’s low near 7,224. Should selling pressure intensify further, the longer-term support zone around 7,000 cannot be dismissed as a potential downside destination.
On the upside, a sustained break above the 7,500-7,517 resistance band would likely open the door for a retest of recent highs circa 7620.
Beyond that, the next major upside target is the 200 per cent extension of the January-to-March decline, which comes in around 7,716 and remains the key bullish objective should momentum reaccelerate.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Have Markets Found a Turning Point Ahead of the Elections?
Fed rate-hike bets topping 70% have pressured markets, including precious metals and U.S. indices, toward key support levels. Could these levels signal a turning point ahead of the U.S. midterm elections?
Nasdaq 100 warning signs mount after brutal October
The Nasdaq 100 has printed a bearish monthly key reversal after a brutal October, with weak market breadth and heavy losses among AI beneficiaries raising the risk of further downside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.