



S&P500 Forecast: SPX falls amid inflation worries and chip losses
US stock futures fell on Tuesday, pressured by weakness in chipmakers and persistent concerns over inflation and elevated bond yields.
Share this:


US futures
Dow futures -0.46%, S&P futures -0.62% & Nasdaq futures -0.94%
In Europe
FTSE 0.51% & DAX 1.08%
- U.S stocks fall amid fragile risk sentiment
- Treasury yields ease but remain elevated
- Chip stocks sell off after recent rally
- Oil falls on the latest US-Iran headlines
US stocks fall as elevated yields and chip Selloff weigh on risk appetite
US stock futures fell on Tuesday, pressured by weakness in chipmakers and persistent concerns over inflation and elevated bond yields.
Risk sentiment remained fragile as investors assessed the latest developments in the Middle East after President Trump canceled a planned strike on Iran at the request of Gulf allies and signaled that a nuclear deal may still be possible. Markets, however, remain skeptical over the prospects for a near-term resolution given the lack of tangible progress towards ending the conflict.
Oil prices edged lower and Treasury yields paused their recent climb, although financial conditions remain tight. The US 10-year Treasury yield held above 4.6%, continuing to weigh on equities and other risk-sensitive assets. Higher yields have been particularly challenging for technology and growth stocks, whose valuations are more sensitive to future earnings expectations.
Inflation concerns and fears that major central banks may need to maintain tighter policy for longer are also beginning to challenge the AI-driven rally that has supported equities in recent months. Attention is now turning to minutes from the Federal Reserve’s latest meeting, due on Wednesday, for clues on whether policymakers are becoming less committed to an easing bias.
Corporate movers
Home Depot rose modestly after reporting earnings and revenue ahead of expectations. The retailer posted earnings per share of $3.43 on revenue of $41.77 billion, both slightly above forecasts.
Blackstone and Alphabet advanced after Blackstone said it would invest $5 billion into a new AI infrastructure venture alongside Google.
Chip stocks remained under pressure, with memory-related names extending recent losses. Micron Technology fell 1.7%, while Seagate Technology dropped 3%. NVIDIA slipped 1% ahead of earnings later this week.
S&P 500 – Technical analysis
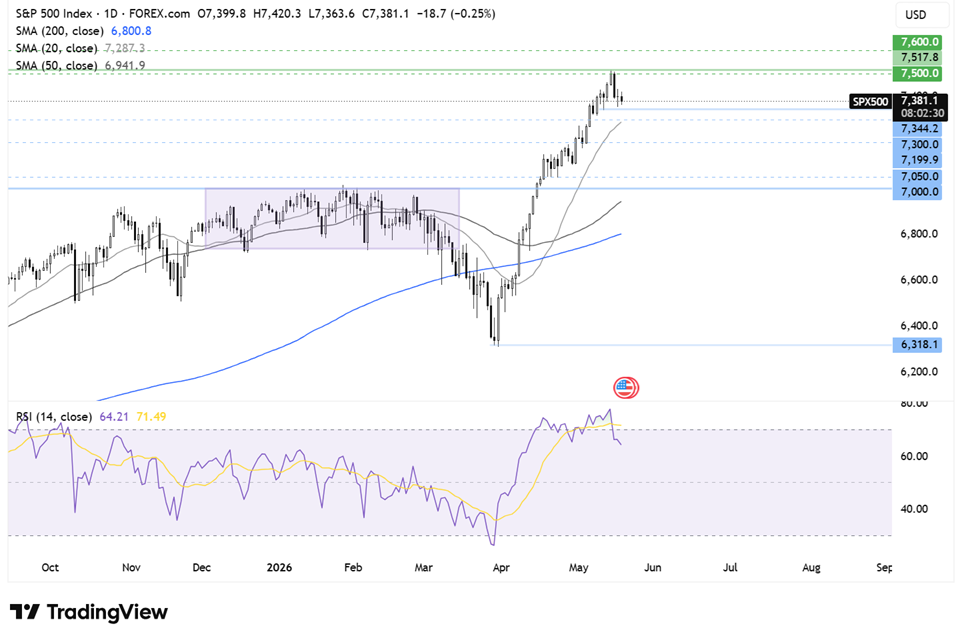
The S&P 500 extended its recovery from the 6,310 low to the 7,515 record high before easing back at eased back to 7380 bringing the RSI out of overbought territory. However, the broader uptrend remains intact while the index holds above key moving averages.
With blue skies above, buyers will look for a break above 7,515 to bring 7,600 into focus.
Support is seen around 7,340, last week's low, and the 20-day moving average near 7,270. A move below 7,000 would be needed to threaten the longer-term bullish structure.
FX markets – USD rises, GBP/USD falls
The US dollar strengthened as elevated Treasury yields and ongoing geopolitical uncertainty continued to support demand for the greenback. The 10-year Treasury yield remained around 4.6%, underpinning the dollar despite the pause in oil’s rally.
EUR/USD remained under pressure amid concerns over the stagflationary impact of elevated oil prices on the eurozone economy. With crude still trading above $100 a barrel and significantly above pre-war levels, investors remain concerned over the inflationary implications for the region.
GBP/USD weakened after UK labour market data pointed to a sharper-than-expected slowdown. Unemployment rose to 5% in the three months to March from 4.9%, while payroll employment fell by 100,000, far worse than forecasts for a 10,000 decline. The data adds to pressure on Prime Minister Keir Starmer amid growing unrest within the Labour Party. Markets have also scaled back expectations for further Bank of England tightening ahead of UK inflation data due Wednesday.
Oil slips as markets await Iran developments
Oil prices fell on Tuesday after President Trump paused a planned attack on Iran to allow more time for negotiations. Brent crude fell around 1%, while WTI dropped more than 3%, as traders reacted to shifting headlines without clear signs of a lasting resolution or a reopening of the Strait of Hormuz.
Supply concerns nevertheless remain elevated. In the US, strategic petroleum reserves fell by a record 9.9 million barrels last week, leaving stockpiles at 374 million barrels, the lowest level since July 2024.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX rebounds as oil prices fall and ahead of Apple earnings
U.S. stock indices are moving higher on Monday as tech and AI-related stocks steady following a shocking October. The mood remains cautious following the AI wobble, with more tech earnings due this week, U.S. midterm elections and a full U.S. economic data calendar.
S&P 500 Forecast: SPX flat ahead of FOMC rate decision and tech earnings
U.S. stocks are rising cautiously ahead of the Federal Reserve interest rate decision later today, as well as key tech earnings after the close.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.