



Ueda’s hawkish shift weighs on USD/JPY
Ueda’s speech stopped short of endorsing a December hike, but the tone suggests the bar for action is much lower than before.
Share this:
- BOJ Governor Ueda says tariff risks fading
- FX moves cited as more influential for inflation expectations
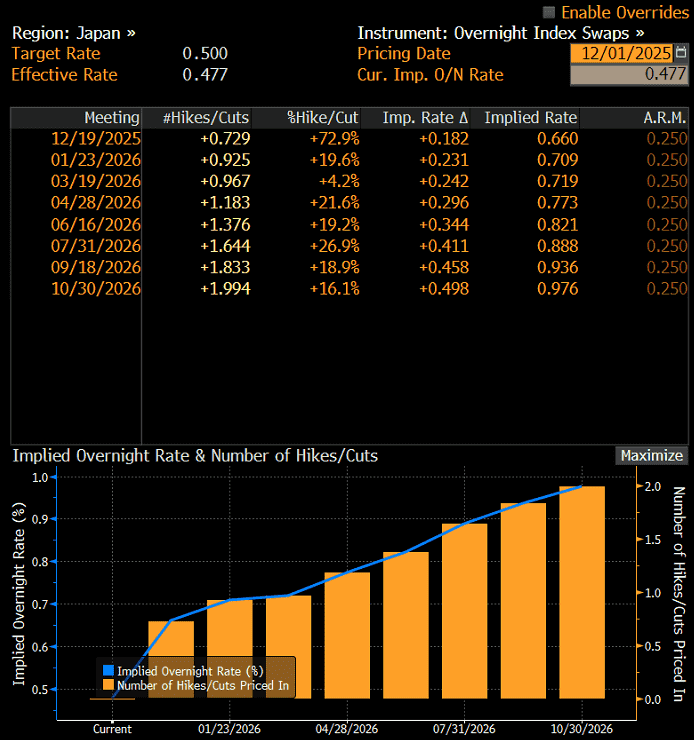
- Swaps price 73% chance of December hike, two hikes by October 2026
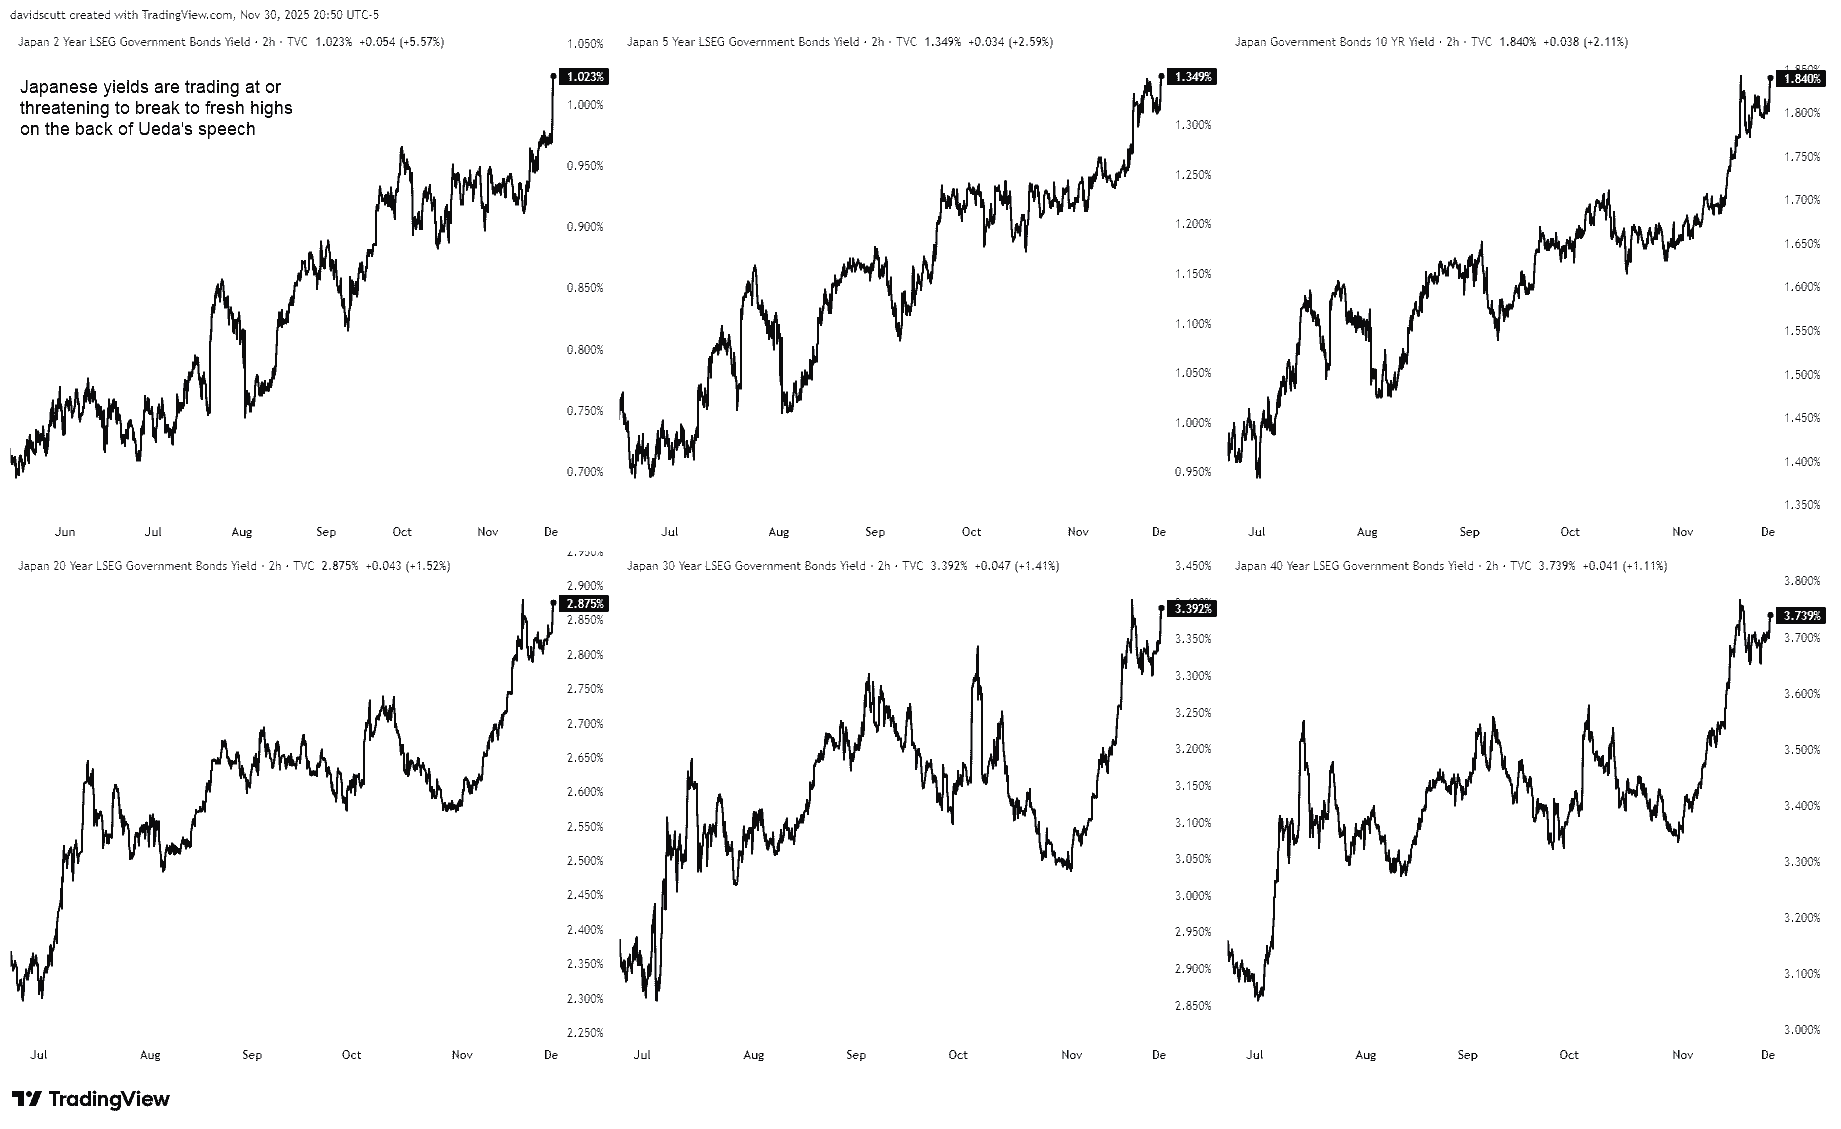
- JGB curve bear-flattens as short-dated yields surge
Summary
Speaking in Nagoya, BOJ Governor Kazuo Ueda struck a hawkish tone, citing fading tariff risks, rising wages and FX sensitivity as reasons policy normalisation is warranted. Markets reacted sharply: swaps now price a 73% chance of a December hike, JGB yields bear-flattened and USD/JPY slid to multi-week lows, breaking its October uptrend. Technical signals point to weakening bullish momentum, making selling into strength and downside breaks more appealing.
Ueda Hawks Up (By His Standards)
Ueda’s latest remarks carry a distinctly hawkish undertone, marking a shift from the caution that dominated earlier this year. One of the clearest signals is his acknowledgment that tariff-related risks, which were a major reason the BOJ paused its tightening cycle, are now receding. He noted that the feared impact of U.S. tariffs on global growth and corporate profits has not materialised, reducing a key external headwind that previously justified patience.
Equally important is the emphasis on wages and their pass-through to prices. Ueda highlighted that the minimum wage rose more than 5% year-on-year for fiscal 2025, a development he believes will encourage broader wage hikes. This matters because the BOJ now sees wage-driven inflation filtering through to goods and services, reinforcing the case for normalisation. His comment that another rate hike would still leave policy “accommodative” underscores that the central bank views tightening as a gradual process, not a brake on growth.
Perhaps most telling is the shift in how the BOJ frames exchange rate dynamics. Ueda warned that FX fluctuations are now more likely to affect prices than in the past, given the emerging cycle between wages and inflation. This linkage, combined with his reference to inflation expectations and continued increases in food prices, suggests the BOJ is increasingly sensitive to imported inflation risks. In short, the rhetoric points to a central bank that is preparing markets for further hikes while signalling that the era of ultra-dovish policy is fading.
Yet, despite laying out a raft of reasons why another move may be warranted, Ueda stopped short of explicitly endorsing a hike at the December meeting. Instead, he said the BOJ will examine economic activity, prices and market developments, and weigh the pros and cons of raising rates. That caveat leaves room for flexibility, but the overall tone suggests the bar for action is lower than it was just a few months ago.


December BOJ Hike Gains Momentum
Markets have responded decisively to Ueda’s remarks. Based on swaps pricing, traders now assign a 73% probability of a 25 basis point hike at the 19 December meeting, up from 57% late last week. By October next year, two hikes are priced in, with overnight rates expected to top 1%.
Source: Bloomberg
That shift in expectations has driven a bear flattening of the JGB curve, with shorter-dated yields rising faster than longer tenors as higher policy rates dim the outlook for nominal growth further out. Two and five-year yields, in particular, have seen sizeable moves today.
Source: TradingView
The adjustment in rate expectations has helped strengthen the yen, adding to the shifting directional risks outlined in my week-ahead analysis released over the weekend. With the BOJ now openly weighing the pros and cons of another hike and markets leaning heavily towards action, the balance of risks for USD/JPY continues to tilt lower, especially if U.S. yields fail to keep pace.
While Ueda stopped short of explicitly endorsing a December hike, the question is why paint such a clear picture that policy normalisation is warranted. His speech came only days after another upside surprise in Tokyo’s November inflation report and followed comments from Japan’s finance minister again over the weekend that yen movements should reflect fundamentals. Against that backdrop, the tone suggests market pricing may still be a little light for a December move, even after today’s repricing.
USD/JPY Downside Risks Build
Source: TradingView
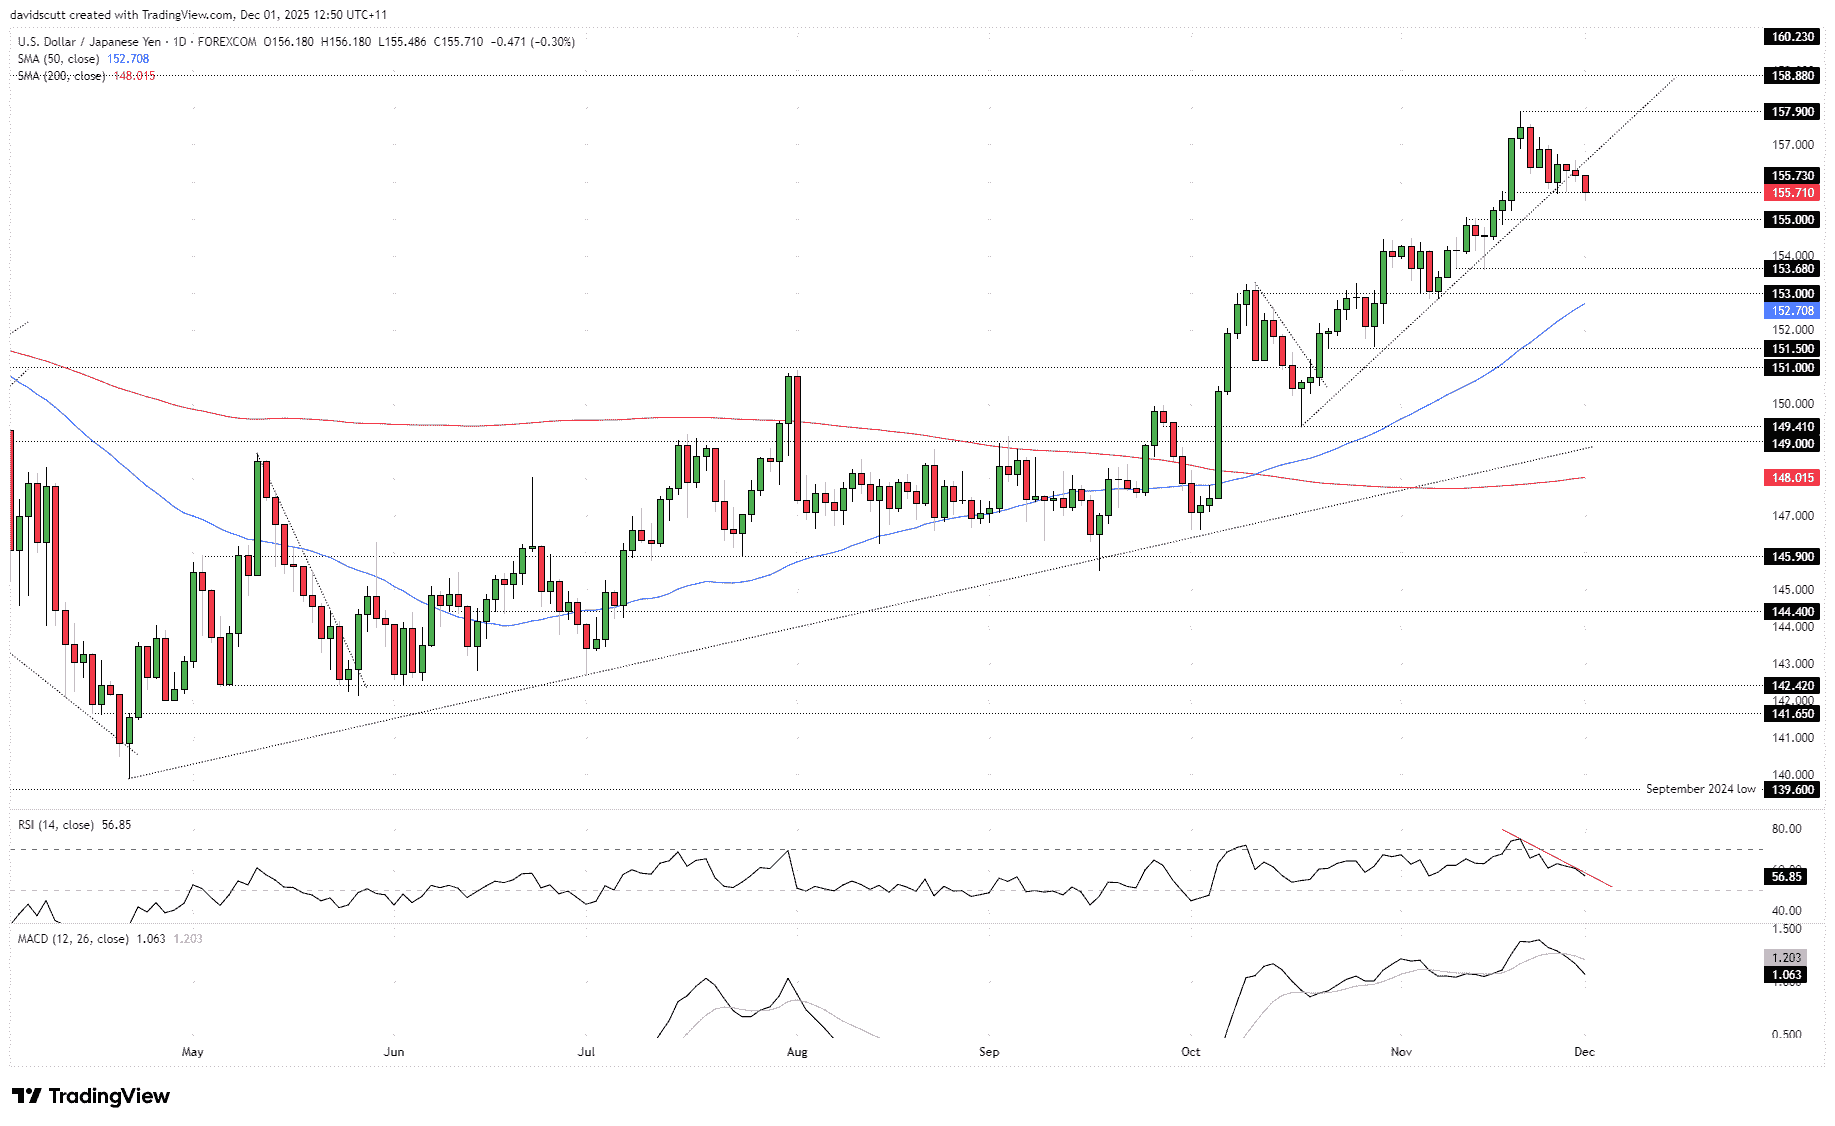
The hawkish tone of the speech saw USD/JPY trade at fresh multi-week lows before finding buying support beneath 155.73. Still, having broken the October uptrend and with RSI (14) and MACD delivering signals that point to rapidly diminishing bullish strength, directional risks now appear skewed to the downside.
Beneath 155.73, minor support is located at 155.00 and 153.68 before more meaningful support arrives at 153.00. Should the bearish unwind abruptly reverse, some residual resistance may be encountered at 157.00, with the November swing high of 157.90 the next notable level after that.
Selling into strength and on downside breaks looks more appealing given the current backdrop.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

GBP/USD, DJIA Outlook: Support Levels Meet Oversold Risks
GBP/USD and the Dow test key support levels as rising Treasury yields, Fed rate-hike expectations and oversold momentum increase reversal risks.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.