



US open: Positive tone on Wall Street ahead of a busy week
Market participants are feeling optimistic at the start of the week, with major indices in Europe rising and US stocks poised to open moderately higher and near record high territory
Share this:
US index futures
- Dow futures +0.0% at 35,891
- S&P futures +0.2% at 4713
- Nasdaq 100 futures +0.4% at 16,389
European indices
- FTSE -0.1% at 7,282
- DAX +0.9% at 15,771
- EURO STOXX +0.7% at 4227
Global risk appetite firms up heading into central bank bonanza
Market participants are feeling optimistic at the start of the week, with major indices in Europe rising and US stocks poised to open moderately higher and near record high territory, essentially erasing the turn-of-the-month drop on fears over a more aggressive Fed taper and the Omicron variant. Even news that the first UK patient died with the Omicron variant and that the country was preparing for a “tidal wave” of cases could not derail bulls’ sentiment. Yields on US Treasury bonds are also ticking lower, confirming the early strength in equity markets.
Looking ahead, this week’s market highlights will come from central bank pronouncements, with the most-watched gatherings taking place through the middle of the week, including monetary policy meetings from the Fed on Wednesday, as well as the BOE and ECB on Thursday.
See my colleague Joe Perry’s Week Ahead preview report for an overview of this week’s key events!
Where next for the S&P 500?
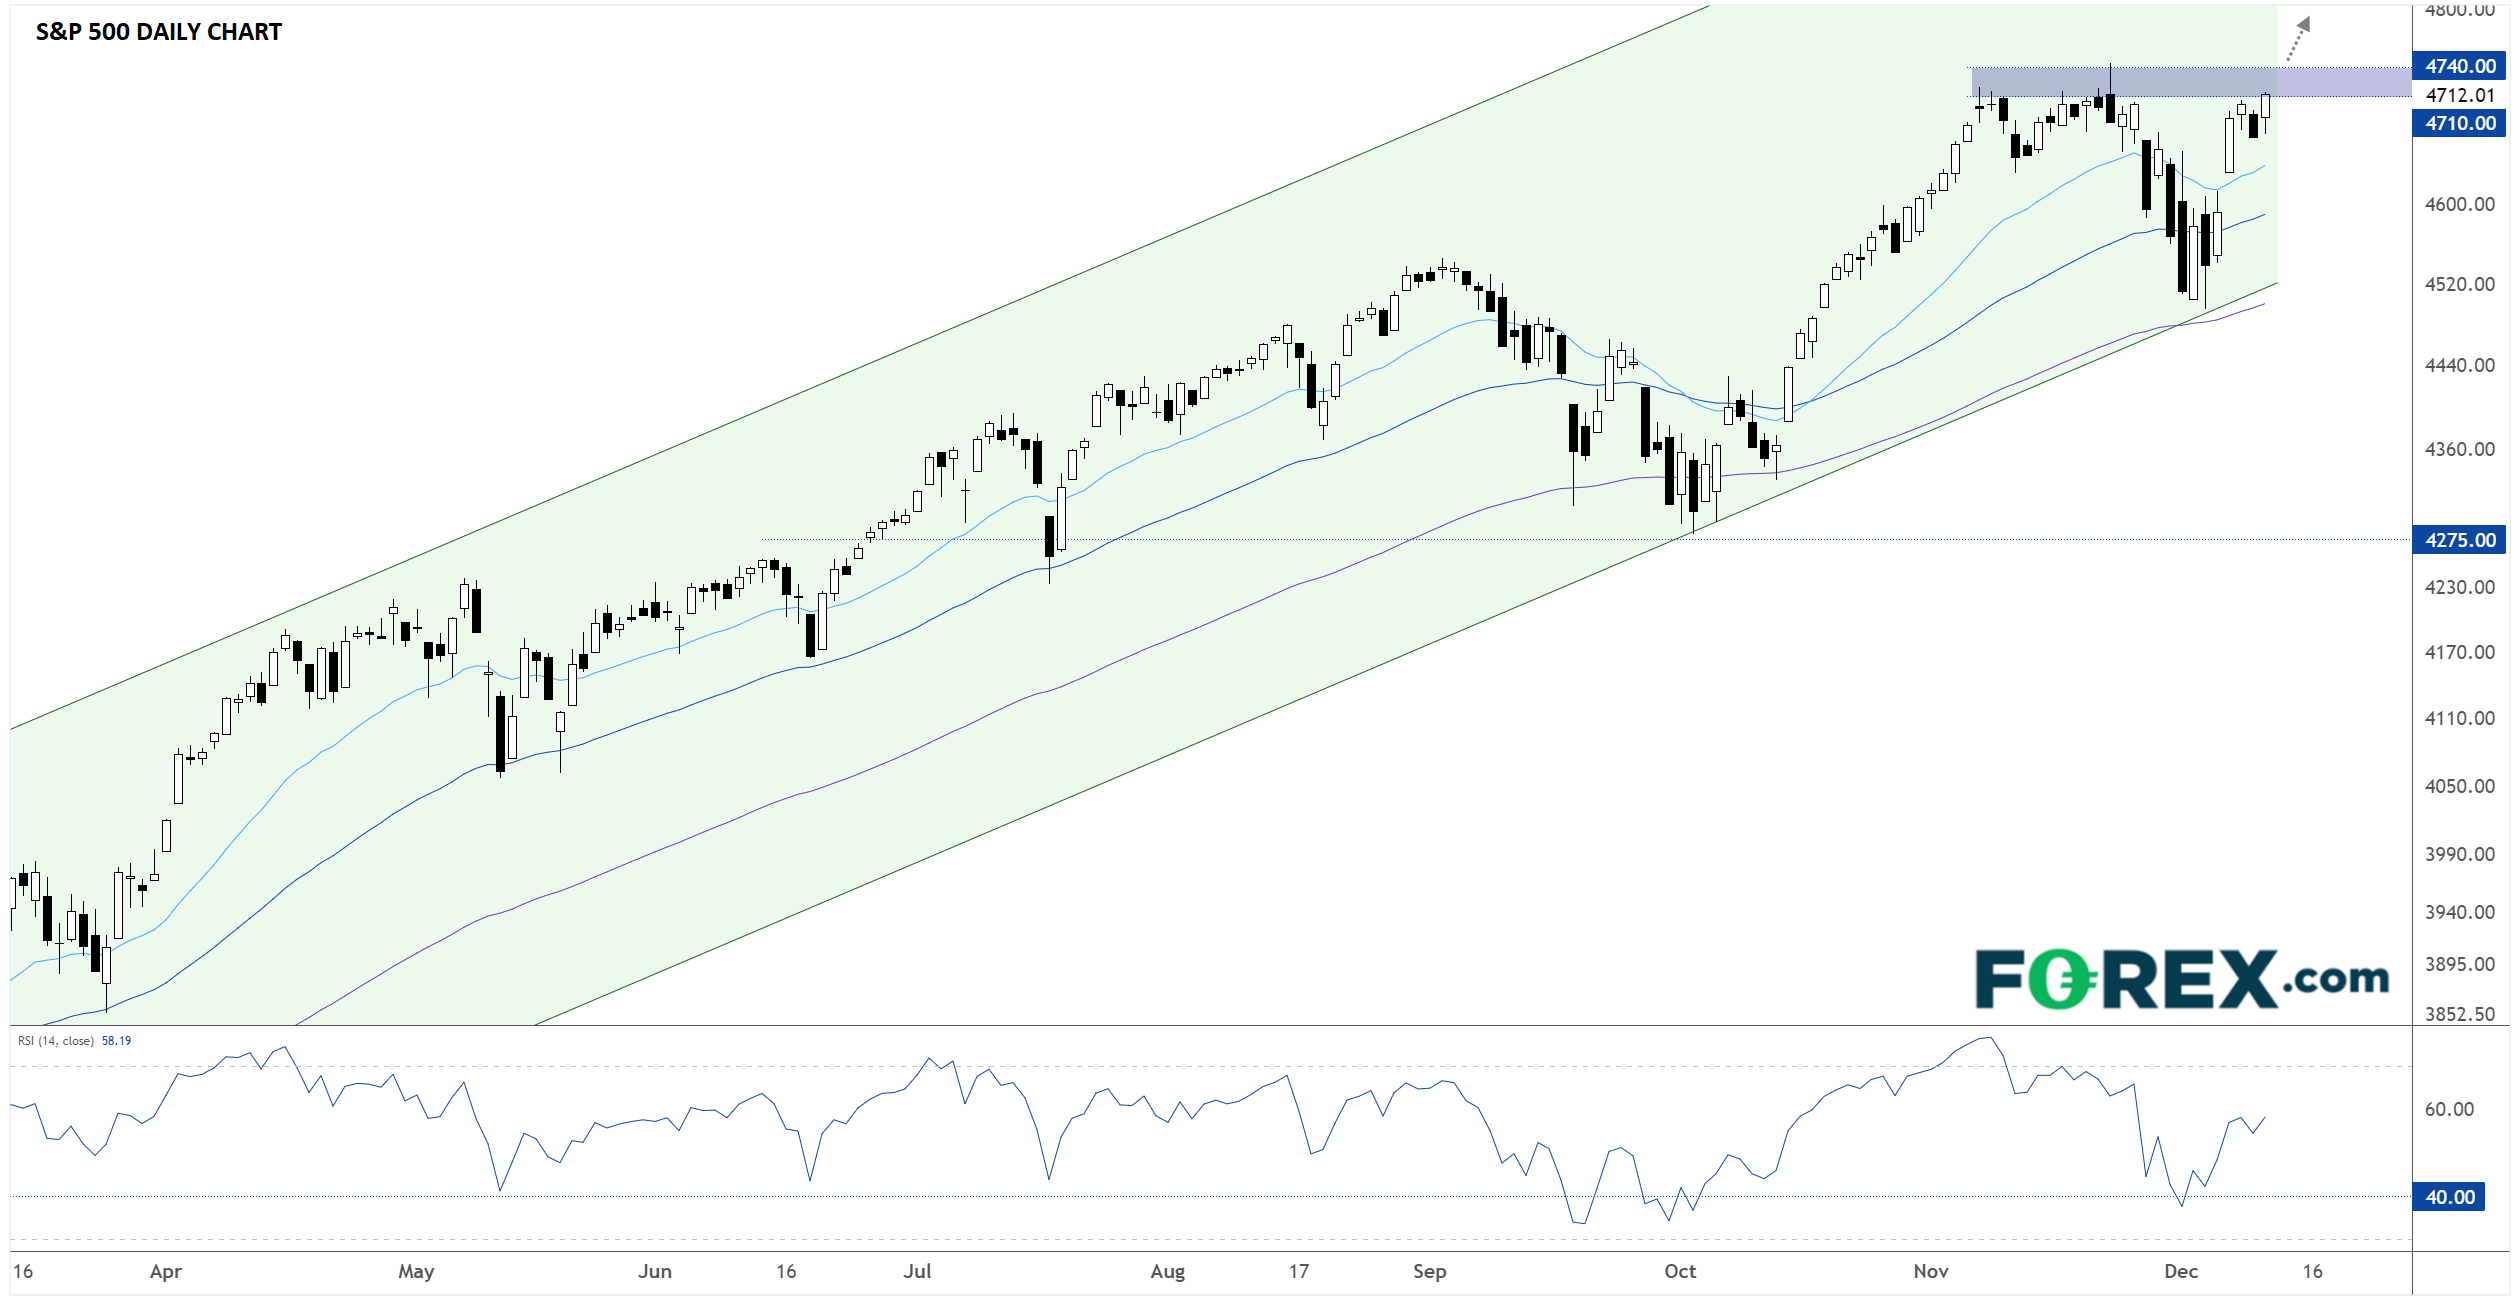
The widely-followed broad US index is set to open near record territory above 4,700, following a short-lived 4% pullback to end November. As any experienced trader will tell you, the trend is your friend when you’re trading using technical analysis, and in that vein, the path of least resistance remains to the topside for the S&P 500. If the index can confirm a close above 4,710 and ideally 4,740 this week, it would increase the odds of a year-end close above 4,800:
Source: TradingView, StoneX
FX: USD rises in otherwise quiet trade
The world’s reserve currency is the strongest of the majors heading into a US session with a barren economic calendar. After Friday’s relatively hot CPI report, most traders expect the Fed to accelerate its taper program later this week, a key step on the path to raising interest rates in the first half of next year. This, in turn, could underscore the widening monetary policy divergence between the US and Eurozone if the ECB hints at extending its asset purchases on Thursday.
- EUR/USD -0.25% at 1.1287
- GBP/USD -0.06% at 1.3259
Oil edges lower to start the week
Oil prices are ticking down nearly -1% to start the week after seeing its largest weekly gain since August last week on declining Omicron fears. Like most other major markets, oil is likely to take its cue from this week’s parade of central bank meetings before settling down as many traders leave their desks for the final two weeks of the year.
- WTI crude trades -0.8% at $71.35
- Brent trades -0.7% at $74.87
Looking ahead
- 17:30 GMT: BOE Governor Bailey speaks about the UK’s Financial Stability Report in London
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
US index futures
- Dow futures +0.0% at 35,891
- S&P futures +0.2% at 4713
- Nasdaq 100 futures +0.4% at 16,389
European indices
- FTSE -0.1% at 7,282
- DAX +0.9% at 15,771
- EURO STOXX +0.7% at 4227
Global risk appetite firms up heading into central bank bonanza
Market participants are feeling optimistic at the start of the week, with major indices in Europe rising and US stocks poised to open moderately higher and near record high territory, essentially erasing the turn-of-the-month drop on fears over a more aggressive Fed taper and the Omicron variant. Even news that the first UK patient died with the Omicron variant and that the country was preparing for a “tidal wave” of cases could not derail bulls’ sentiment. Yields on US Treasury bonds are also ticking lower, confirming the early strength in equity markets.
Looking ahead, this week’s market highlights will come from central bank pronouncements, with the most-watched gatherings taking place through the middle of the week, including monetary policy meetings from the Fed on Wednesday, as well as the BOE and ECB on Thursday.
See my colleague Joe Perry’s Week Ahead preview report for an overview of this week’s key events!
Where next for the S&P 500?
The widely-followed broad US index is set to open near record territory above 4,700, following a short-lived 4% pullback to end November. As any experienced trader will tell you, the trend is your friend when you’re trading using technical analysis, and in that vein, the path of least resistance remains to the topside for the S&P 500. If the index can confirm a close above 4,710 and ideally 4,740 this week, it would increase the odds of a year-end close above 4,800:

Source: TradingView, StoneX
FX: USD rises in otherwise quiet trade
The world’s reserve currency is the strongest of the majors heading into a US session with a barren economic calendar. After Friday’s relatively hot CPI report, most traders expect the Fed to accelerate its taper program later this week, a key step on the path to raising interest rates in the first half of next year. This, in turn, could underscore the widening monetary policy divergence between the US and Eurozone if the ECB hints at extending its asset purchases on Thursday.
- EUR/USD -0.25% at 1.1287
- GBP/USD -0.06% at 1.3259
Oil edges lower to start the week
Oil prices are ticking down nearly -1% to start the week after seeing its largest weekly gain since August last week on declining Omicron fears. Like most other major markets, oil is likely to take its cue from this week’s parade of central bank meetings before settling down as many traders leave their desks for the final two weeks of the year.
- WTI crude trades -0.8% at $71.35
- Brent trades -0.7% at $74.87
Looking ahead
- 17:30 GMT: BOE Governor Bailey speaks about the UK’s Financial Stability Report in London
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

US Midterm Fallout: What Does the “Blue Tsunami” Mean for the S&P 500?
Democrats made sweeping gains in the US midterm elections, winning control of both the House and Senate - what does it mean for the S&P 500 and the AI trade?
USD/CAD Forecast: Canadian Dollar Gains Ground After U.S. Midterm Elections
The trading week continues to unfold and the recovery in the Canadian dollar has once again become a relevant theme in the short term. This can be clearly seen in the recent performance of USD/CAD, which is down nearly 0.4% during the session, reflecting a consistent recovery in the CAD against the U.S. dollar.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.