




US open Wall Street mixed USD pushes higher bond yields in focus
Stocks point to a mixed start following yesterday's steep selloff. US treasury yields ease but USD remains strong.
Share this:

US futures
Dow futures -0.01% at 31315
S&P futures +0.3% at 3840
Nasdaq futures +0.5% at 12915
In Europe
FTSE -1.6% at 6540
Dax -0.4% at 13815
Euro Stoxx -0.9% at 3650
Learn more about trading indices
Risk rally halts
Risk assets are broadly out of favour again today after a steep selloff in the previous session. Investors continue to price in a solid economic recovery, rising inflation and earlier intervention from the Fed despite soothing words of support from Fed Chair earlier in the week.
The yield on the 10-year treasury yield surged to 1.6% a pre-pandemic high overnight although has eased back to 1.5% today.
The strong greenback is hitting commodity prices across the board.
Stimulus vote
The House of Representatives will vote on President Biden’s relief package later in the session.
The Democrats plans to implement a national minimum wage of $15 as part of the $1.9 trillion stimulus proposal have been stopped in their tracks. A Senate official ruled that it can’t be passed under the Budget reconciliation provisions.
Stock to open mixed, after steep selloff
US stocks are pointing to a mixed start in cautious trading after sharp declines on Thursday as investors adjusted positions for rising inflation expectations.
The Dow Jones close -1.8% lower, the S&P 500 shed -2.5% and the Nasdaq slumped -3.5% in its biggest one-day selloff since October 28th.
This selloff marked a notable turnaround for stocks which have rallied hard across January and February.
However, with bond yields rising the markets are pricing in earlier intervention from the Fed. The potential of rising borrowing costs is taking the shine off stocks, particularly high growth stocks which have stretched valuations.
Airbnb
Airbnb dived over 9% in the previous session hit by the broad tech stock selloff. However, it trades +1.5% pre-market after forecasting a strong rebound in bookings this year.
Beyond Meat
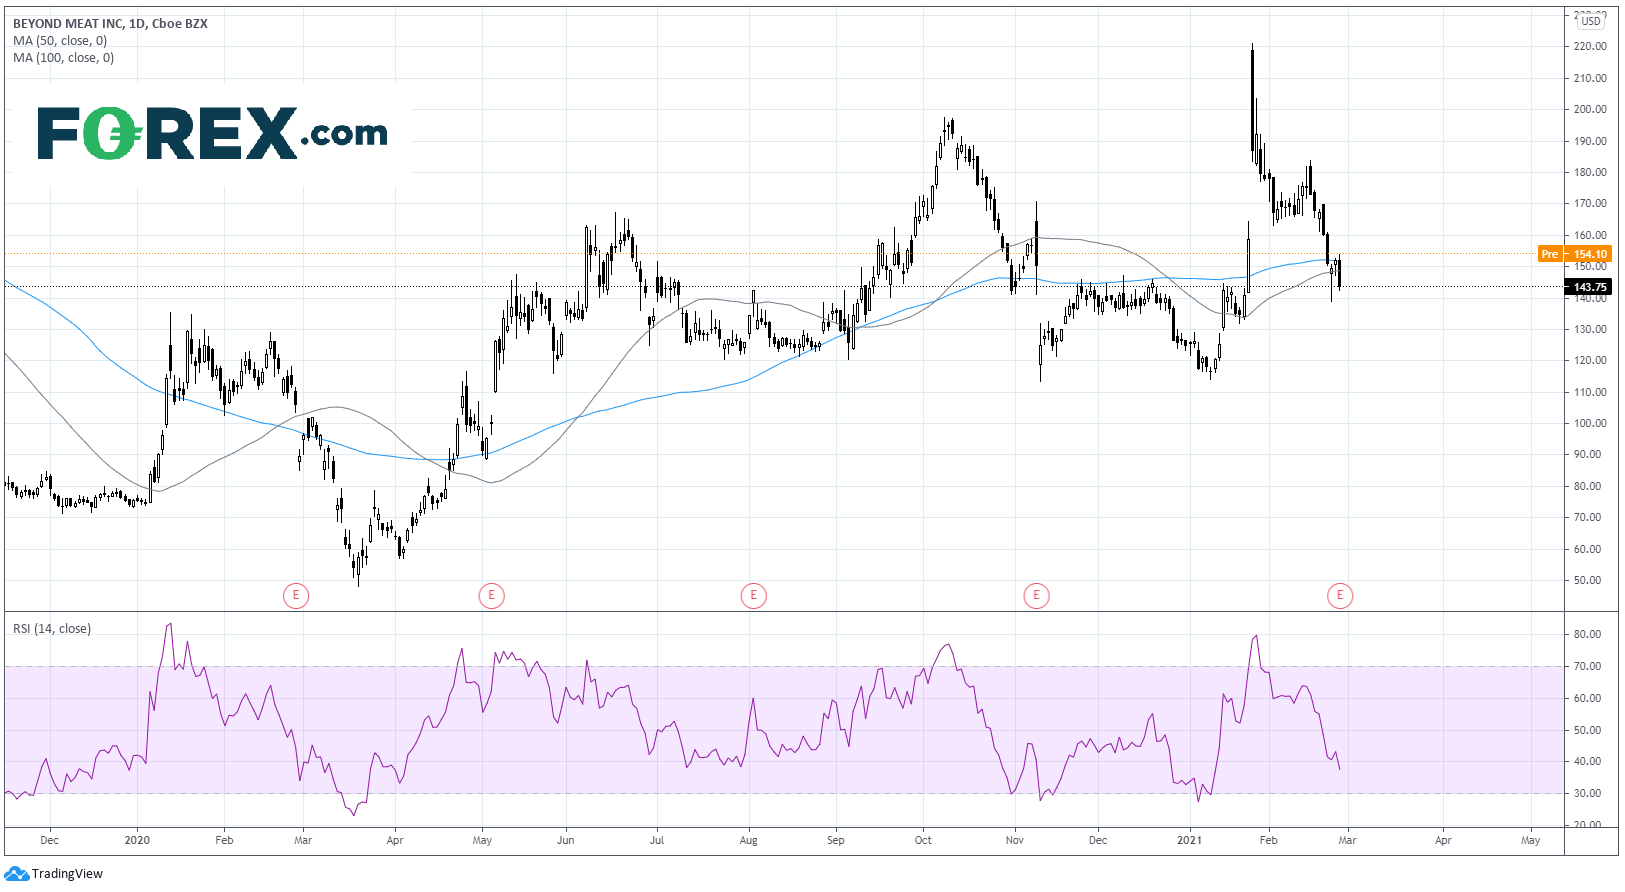
Beyond Meat trades +5.9% pre-market after announcing that it has signed an agreement with McDonalds and Yum! The owner of KFC, Pizza Hut and Taco Bell.
FX – US Dollar soars
The US Dollar rebounded off a 7 week low in the previous session and has continued rising as investors reprice the chances of a rate hike from the Fed. DXY looks towards 91.00
GBP/USD has fallen sharply from 1.4230 highs earlier in the week and heads towards $1.39 on US D strength and after BoE Governor Andrew Bailey warned that the UK economy is expected to contract in Q1.
Analyst Fiona Cincotta looks at GBP/USD price action and levels to watch.
GBP/USD trades -0.70% at 1.3914
EUR/USD trades -0.5% at 1.2115
Oil slides but set for 6% gains across the week
As with other commodities, crude oil trades over 1% lower on the back of US Dollar strength and as investors repositioned ahead of next week’s OPEC meeting. The meeting will see the output levels for April set. Speculation is growing that Russia will push for a rise in output levels.
Despite today’s selloff, WTI is still on track for 5% gains across the week.
Baker Hughes rig count data due later.
US crude trades +2% at $62.25
Brent trades +0.4% at $64.81
Learn more about trading oil here.
The complete guide to trading oil markets
US futures
Dow futures -0.01% at 31315
S&P futures +0.3% at 3840
Nasdaq futures +0.5% at 12915
In Europe
FTSE -1.6% at 6540
Dax -0.4% at 13815
Euro Stoxx -0.9% at 3650
Learn more about trading indices
Risk rally halts
Risk assets are broadly out of favour again today after a steep selloff in the previous session. Investors continue to price in a solid economic recovery, rising inflation and earlier intervention from the Fed despite soothing words of support from Fed Chair earlier in the week.
The yield on the 10-year treasury yield surged to 1.6% a pre-pandemic high overnight although has eased back to 1.5% today.
The strong greenback is hitting commodity prices across the board.
Stimulus vote
The House of Representatives will vote on President Biden’s relief package later in the session.
The Democrats plans to implement a national minimum wage of $15 as part of the $1.9 trillion stimulus proposal have been stopped in their tracks. A Senate official ruled that it can’t be passed under the Budget reconciliation provisions.
Stock to open mixed, after steep selloff
US stocks are pointing to a mixed start in cautious trading after sharp declines on Thursday as investors adjusted positions for rising inflation expectations.
The Dow Jones close -1.8% lower, the S&P 500 shed -2.5% and the Nasdaq slumped -3.5% in its biggest one-day selloff since October 28th.
This selloff marked a notable turnaround for stocks which have rallied hard across January and February.
However, with bond yields rising the markets are pricing in earlier intervention from the Fed. The potential of rising borrowing costs is taking the shine off stocks, particularly high growth stocks which have stretched valuations.
Airbnb
Airbnb dived over 9% in the previous session hit by the broad tech stock selloff. However, it trades +1.5% pre-market after forecasting a strong rebound in bookings this year.
Beyond Meat
Beyond Meat trades +5.9% pre-market after announcing that it has signed an agreement with McDonalds and Yum! The owner of KFC, Pizza Hut and Taco Bell.
FX – US Dollar soars
The US Dollar rebounded off a 7 week low in the previous session and has continued rising as investors reprice the chances of a rate hike from the Fed. DXY looks towards 91.00
GBP/USD has fallen sharply from 1.4230 highs earlier in the week and heads towards $1.39 on US D strength and after BoE Governor Andrew Bailey warned that the UK economy is expected to contract in Q1.
Analyst Fiona Cincotta looks at GBP/USD price action and levels to watch.
GBP/USD trades -0.70% at 1.3914
EUR/USD trades -0.5% at 1.2115
Oil slides but set for 5% gains across the week
As with other commodities, crude oil trades over 1% lower on the back of US Dollar strength and as investors repositioned ahead of next week’s OPEC meeting. The meeting will see the output levels for April set. Speculation is growing that Russia will push for a rise in output levels.
Despite today’s selloff, WTI is still on track for 5% gains across the week.
Baker Hughes rig count data due later.
US crude trades +2% at $62.25
Brent trades +0.4% at $64.81
Learn more about trading oil here.
The complete guide to trading oil markets
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
AUD/USD Analysis: What's Next for the Australian Dollar After the RBA Decision?
Recent trading sessions have reflected a more neutral tone around the Australian dollar. This can be seen in AUD/USD price action, which has posted moves of roughly 0.2% over the last two sessions without establishing a clear direction. Much of this lack of momentum is linked to expectations surrounding the next policy moves from both the Reserve Bank of Australia (RBA) and the Federal Reserve.

USD into a Massive Week as Yields Fly and Gold Breaks
It’s a huge week with PCE and NFP, but it’s what’s happening off of the calendar that demands attention with US yields flying to fresh multi-decade highs.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.