



USD/JPY Has Been a Big Mover on US CPI Data – Will Tomorrow Force a Repeat?
USD/JPY bulls are clawing back after the intervention-fueled sell-off but will tomorrow’s US CPI print compel another shock to the carry trade, or will strong inflation lead to more USD-strength and an eventual re-test of the 160.00 handle?
Share this:
USD, USD/JPY Talking Points:
- The long-term USD/JPY carry trade is still swinging USD trends across the FX market.
- At root of the USD/JPY trade are rate expectations and as high US CPI forced expectations higher over the past two months, USD/JPY bulls drove a rally that eventually brought out coordinated intervention.
- Over the past four years some of the largest moves in USD/JPY have been sparked by US CPI rather than interventions and that puts even more interest behind tomorrow’s release.
The Bank of Japan and the US Treasury Department took their swing at USD/JPY two weeks ago, but since then, bulls have been clawing back. This puts perhaps even more importance on tomorrow’s US CPI report as rates markets still widely-expect the US to lift rates later this year, with an approximate 80% probability priced-in for at least one 25 bp hike.
Even September is looking like a coin flip, and that’s largely owed to the spike in CPI seen earlier this summer on the back of the war in Iran. As oil prices rallied, inflation followed, and there’s been a growing chorus of Fed-speakers that sound as though they’re warming to the idea of tightening policy, looking to avoid a repeat of the disaster in 2021 that saw the FOMC dismiss inflation as ‘transitory’ until, eventually, they had no choice but to hike aggressively in 2022.
US CPI Prints Since Jan 2021
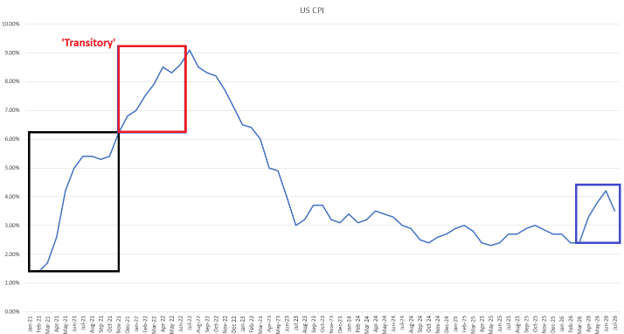
Chart prepared by James Stanley
Rates Markets
Right now rates markets are highly expecting a rate hike from the Fed later this year, which would fly in the face of President Trump’s strategy in which he wanted to install a Fed Chair that would cut rates. So far, Warsh has sounded more hawkish than dovish but as I shared after the last FOMC meeting, it seems as though he’s doing that to keep markets from just expecting that he’s going to cut rates whenever he can. If they did think that Warsh was a dove, that could give upward momentum to US Treasury Yields, such as we’ve seen, and that could complicate the picture for the US Treasury Department that has a considerable amount of debt coming due over the next four months and then more over the next year.
This is likely why he keeps saying that the market will adjust rates based on the preponderance of data rather than waiting for the Fed to do so. Nonetheless, that expectation still leans towards wide expectations for the Fed to hike, and this comes with numerous market responses such as a stronger USD, a stronger USD/JPY, etc. And if we do see those rate hike odds price out, then, reasonably, there could be a shift in price action for those markets, as well.
At this stage hike in September is a veritable coin flip.
CME Fedwatch Odds for September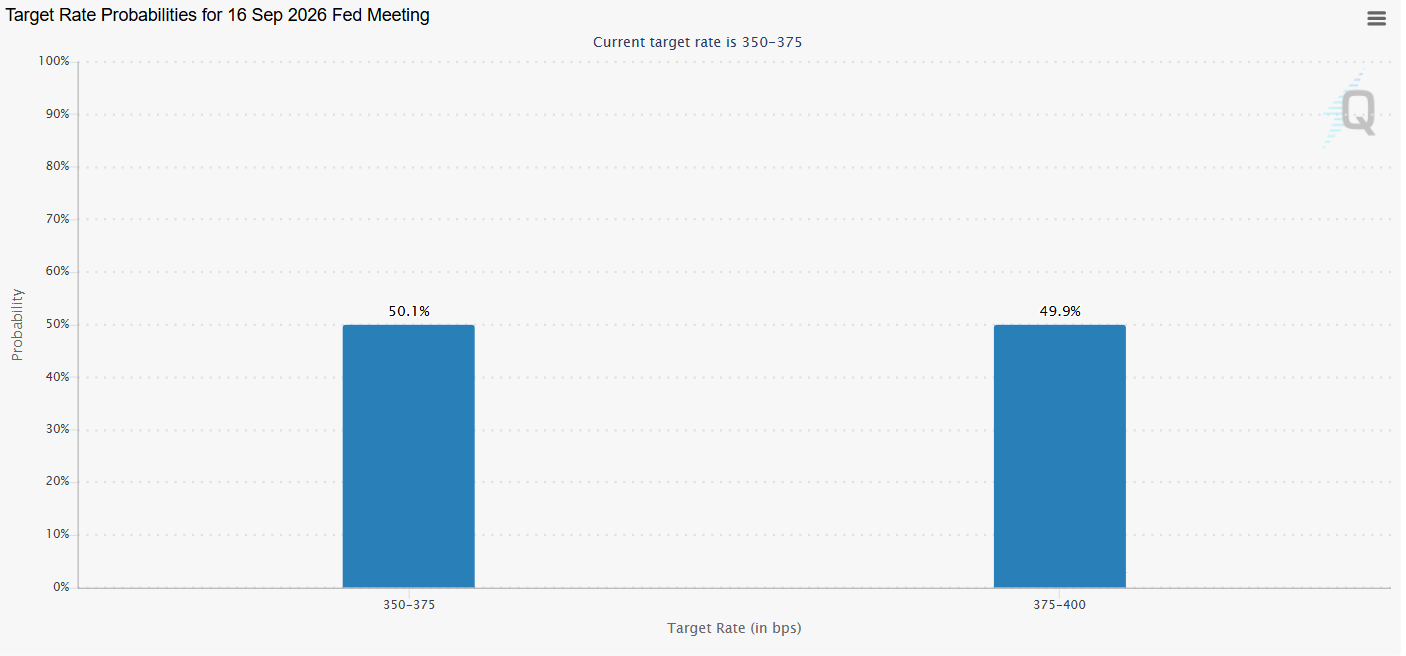
Chart prepared by James Stanley; data derived from CME Fedwatch
US CPI is Important for USD/JPY, Which is Important for the USD and FX Market
Some of the largest moves in USD/JPY over the past four years have been fueled by a US CPI release.

In October of 2022, when the Fed was hiking aggressively to tame the ‘transitory’ inflation that turned out to be not so transitory, USD/JPY was in a near-parabolic like state. To the point where Japanese officials were beginning to worry about the possibility of hyperinflation. So, they tried to step in at 145 and that largely failed, as the intervention merely prodded a pullback that USD/JPY bulls bid, eventually driving price up to 150.00.
At that point, the BoJ was forced to act, after a high of 151.95 traded. They intervened on a Friday ahead of the weekend and, again, price retreated to support before buyers piled back in.
But this time, as price re-approached that 150.00 handle that was previously defended, bulls began to back away. They still held and even bought at support, but as bounced showed up they came in with lower-highs.
What ultimately drove a reversal was the US CPI print on the morning of November 10th, 2022. That was when markets got warm to the idea that perhaps the Fed was getting a handle on inflation, and maybe they would soon be able to stop hiking and, perhaps even eventually cut rates. US CPI was 7.1% at the time and core was at 6.3% so this was still a distant prospect – but the possibility of change was enough to convince longs to bail on positions given that the theoretical cap on upside at the time, at 150.00 made chasing prices higher a less attractive setup.
That market reversed by about 2,000 pips over the course of around two months, with bulls ultimately getting back in the driver seat in January. They, again, drove right back to the same 151.95 level. And, again, it was a below-expected US CPI print in November that shook the branch of the carry trade. This time, it was a mere 23.6% retracement of that prior rally with bulls getting control in December and going right back up to the same 151.95 spot.
In April of 2024, hope was beginning to fade on rate cuts and on April 10th, the morning of a US CPI print, above expected data dashed rate cut hopes – and this time, USD/JPY broke out as the stops above 151.95 provided rocket fuel for longs, and the pair made a firm run up to the next big figure at 160.00.
The Bank of Japan, again, intervened, and that brought about a week of weakness to USD/JPY but that same 151.95 level provided a launch pad for bulls to get back in the driver seat, with price trickling back-above 160.00 shortly after.
The next intervention, in July of 2024, saw the BoJ take a different approach. This time, they waited until the morning of a US CPI print and the combination of the two forces, with inflation coming in below expectations and markets finally getting the confirmation they needed that the Fed could probably cut rates that year, sparked a dizzying reversal – and not just in USD/JPY, as the high-flying AI trade came under fire, as well.
USD/JPY Daily Chart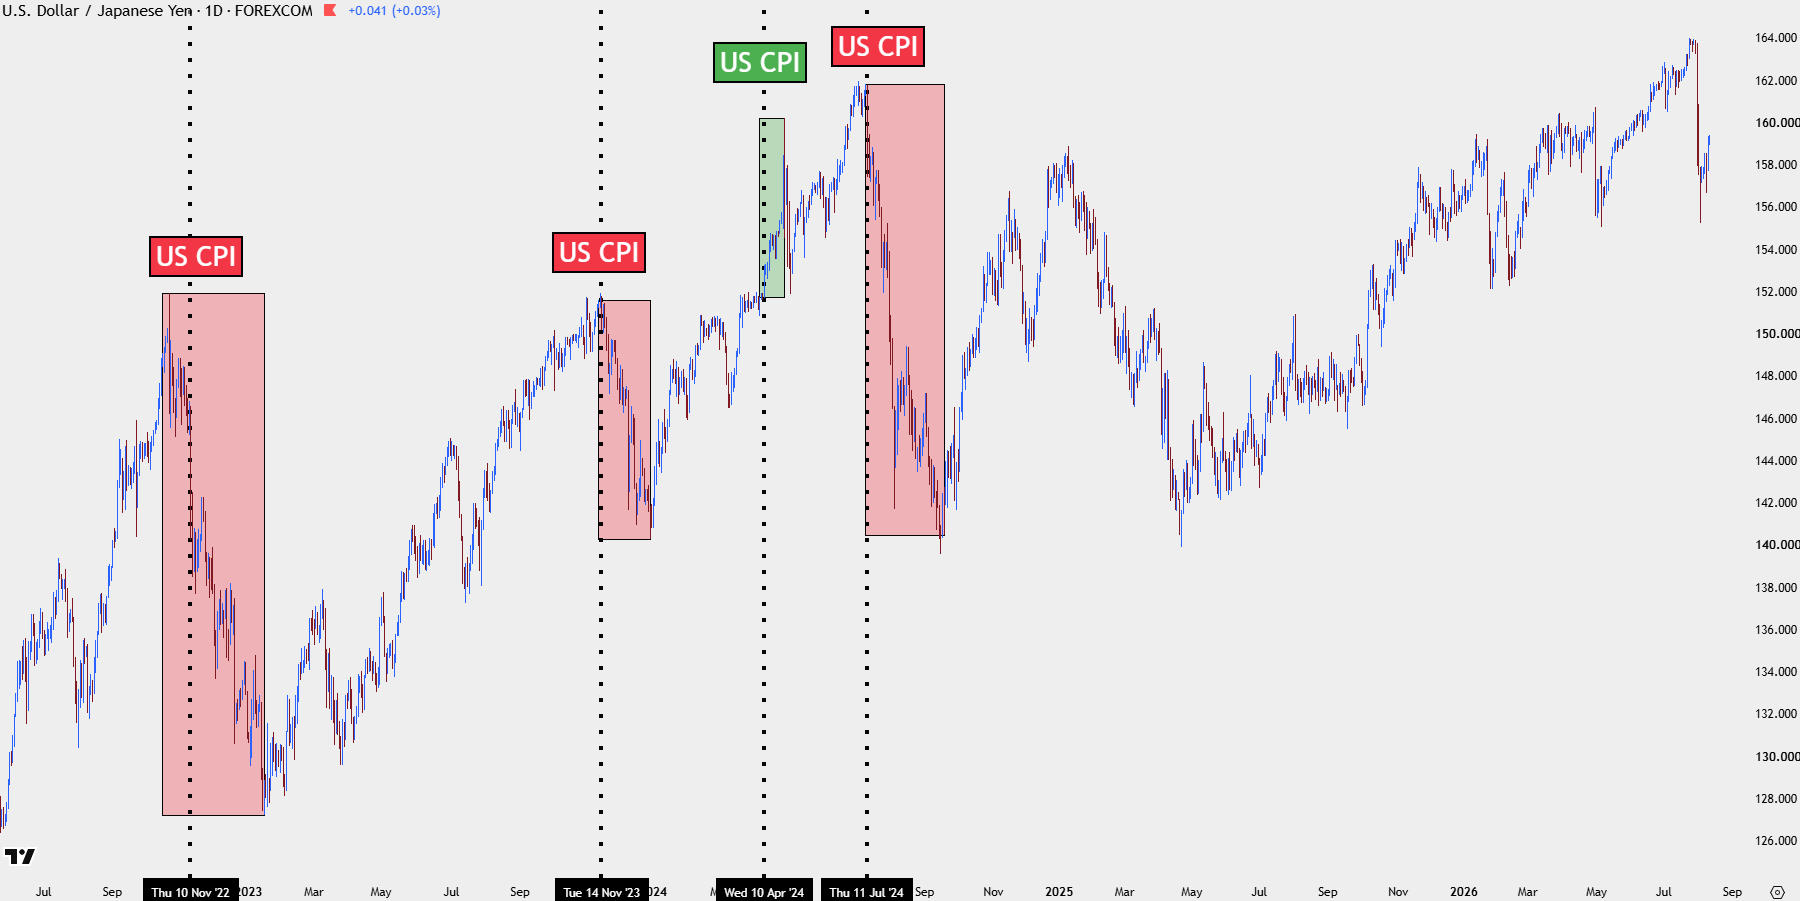
Chart prepared by James Stanley; data derived from Tradingview
Why USD/JPY is So Sensitive to US CPI
The carry trade is driven by rate differentials, and those are largely driven by inflation. With central banks tasked with monitoring inflation, drops that lead to lower rate expectations or even just fewer rate hikes could be enough to compel longs to close positions, such as we saw in November of 2022 or 2023, or again in July of 2024.
And because the USD/JPY trade is still up more than 50% from early 2021 levels, then logically there’s a large built-in position on the long side of the pair, which means selling in USD/JPY can lead to USD-weakness elsewhere, such as we saw with the EUR/USD rally in Q3 of 2024, or even the bullish move in EUR/USD two weeks ago.
--- written by James Stanley, Senior Market Analyst, Global Macro
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

USD/CAD Forecast: Canadian Dollar Gains Ground After U.S. Midterm Elections
The trading week continues to unfold and the recovery in the Canadian dollar has once again become a relevant theme in the short term. This can be clearly seen in the recent performance of USD/CAD, which is down nearly 0.4% during the session, reflecting a consistent recovery in the CAD against the U.S. dollar.
Euro Technical Outlook: EUR/USD Support Reversal Sets Up Breakout Test Ahead of NFP 11 4 2026
Euro bulls are attempting to build on the rebound from recent lows, but pivotal resistance still stands in the way of a larger EUR/USD recovery.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.