



USD/JPY Marches Higher as Markets Wake Up to Fed Risks
What will it take to stop the dollar? With payrolls surging, economic surprises piling up and the Fed's easing bias on life support, the answer may require far more than BOJ rate hikes or intervention threats.
Share this:
- USD/JPY trades above 160 once again
- Strong payrolls reinforce US growth momentum
- Multiple Fed hikes priced over the next year
- CPI, PPI and SpaceX IPO in focus next week
Above 160 and Still Climbing
The yen heads into the new week on the back foot, with USD/JPY trading north of 160 despite markets pricing almost two full Bank of Japan rate hikes by year-end. Add in the threat of intervention from Japanese authorities and it's fair to ask why the yen isn't performing better.
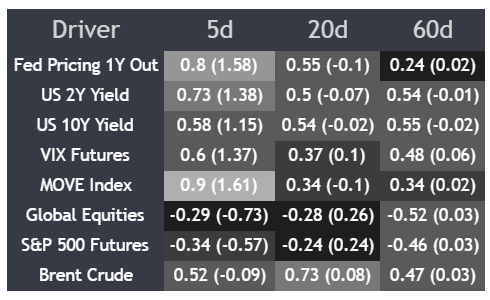
The correlation matrix below provides the answer.
Source: TradingView
Over the past week, USD/JPY has exhibited its strongest relationships with Fed pricing looking out one year (0.80), US two-year Treasury yields (0.73) and US 10-year Treasury yields (0.58), highlighting the influence of yield differentials, particularly at the front end of the curve. Equally telling, USD/JPY has maintained a positive correlation with both VIX futures and MOVE index, suggesting the yen's traditional role as a proxy for risk appetite remains largely redundant.
US Exceptionalism Lives On
While many have spent much of the past year waiting for signs of a meaningful slowdown in the US economy, the data is now increasingly pointing to the opposite direction. Citi's US Economic Surprise Index has climbed to its highest level in years, indicating economic releases are consistently outperforming expectations.

Source: LSEG
The latest nonfarm payrolls report only reinforced that message. The US economy added 172,000 jobs in May, more than double consensus forecasts, while revisions added a further 93,000 jobs to payroll growth reported in March and April. The unemployment rate held at 4.3%, leaving the three-month average payroll gain at 188,000. That's not evidence of an economy on the verge of capitulation.
Behind the Curve?
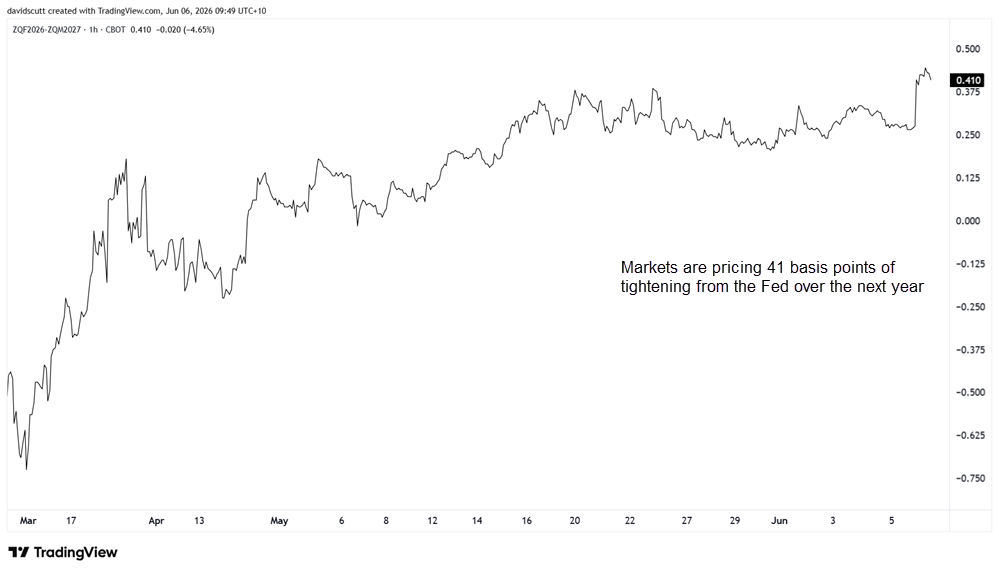
Markets are waking up to the possibility that the Fed is behind the curve in fighting inflation, with futures now pricing 41 basis points of tightening over the coming year.
Source: TradingView
At present, the Fed retains an easing bias, underpinned by the view that risks to its dual mandate are skewed towards the downside for full employment rather than upside risks for inflation. But with the labour market reaccelerating, the risks are now arguably skewed towards persistently high inflation. The idea that policymakers can simply look through this latest inflation pulse is getting flimsier by the day, risking a repeat of the policy error made coming out of the pandemic when officials were slow to respond to mounting price pressures.
What Stops the Dollar?
Given the macro backdrop, the prospects for sustained yen appreciation remain remote. As price action since the BOJ first intervened in late April demonstrates, that has been unable to offset the combination of a reaccelerating US economy and growing expectations that the Fed may need to tighten policy further.
The obvious question is what could change that.
The most obvious candidate would be a meaningful deterioration in the US economy. Given the relationship between USD/JPY and the front end of the US curve, sustained yen strength likely requires a material repricing lower in Treasury yields and Fed expectations. Right now, such an outcome looks extremely remote.
The other possibility is a disorderly unwind in riskier asset classes that pressures carry trades. But with yen borrowing costs remaining low and stable and the currency continuing to weaken, the pressure on leveraged positions is limited. It would likely take a mammoth decline in riskier asset classes to change that, putting added emphasis on price action on Monday following Friday's significant losses on Wall Street.
A Big Week for Inflation
Source: TradingView
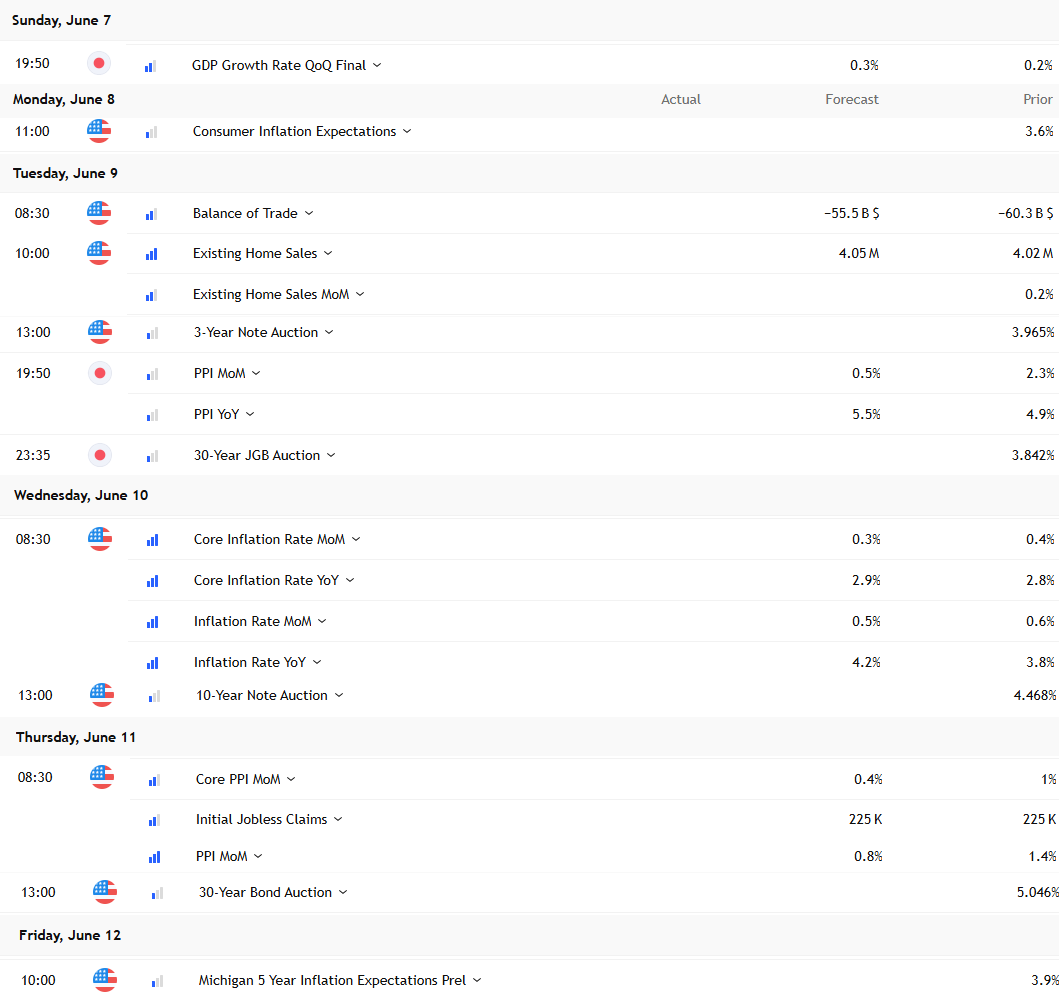
US inflation data looms as the key known risk event next week. Another significant upside surprise would only add to pressure on the Fed to acknowledge that risks to its mandate have shifted.
While CPI is usually the bigger market mover, upstream price pressures are now arguably more important when assessing the sustainability of the inflation surge, meaning PPI could prove the larger volatility event. Inflation expectations measures will add further colour either side of those releases.
In Japan, the May PPI report will also warrant attention following the huge upside surprise seen in April.
The other event that may influence sentiment is the likely SpaceX IPO. Given the scale of the offering, a strong debut would bolster risk appetite that has helped underpin carry trades and capital flows into higher-yielding assets.
160.73 in Sight
Source: TradingView
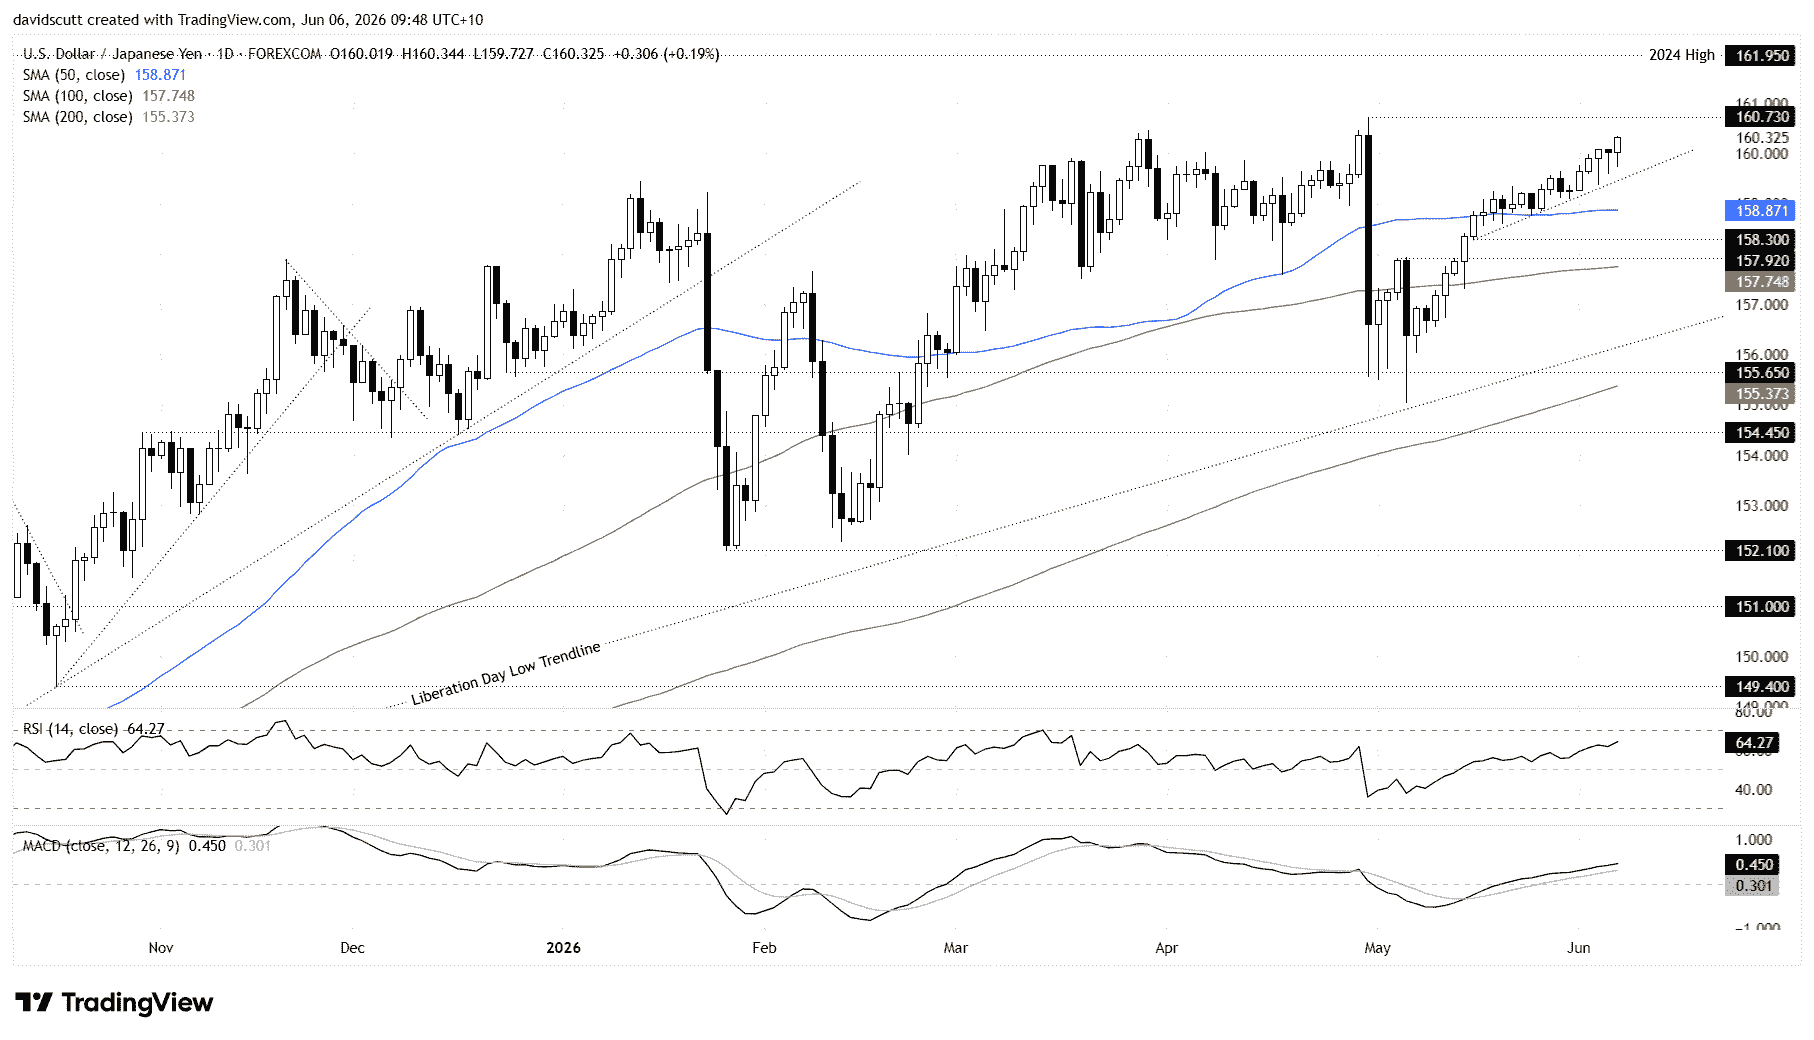
Fitting with the fundamental picture, technicals remain unambiguously bullish for USD/JPY. The pair finds itself grinding higher within a gradual uptrend, moving ever closer to testing the 2026 high of 160.73.
It remains the key level to watch immediately overhead, with a break likely to see bulls set sail for a run towards the multi-decade high of 161.95 set in 2024.
Beneath where the pair now trades, uptrend support is located around 159.50, with the 50-day moving average and former breakout level of 157.92 the next levels of note.
Momentum is also on the side of bulls, with RSI (14) trending higher without yet being overbought. MACD is confirming, pushing further into positive territory having crossed the signal line from below nearly a month ago.
The overall message favours long setups over shorts.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.