




Week Ahead Now that US China Trade Deal is Signed Whats Next
The markets next week are likely to focus once again on macro-economic data.
Share this:

Aside from the ceremonial signing of “Phase One” of the US-China Trade Deal, this past week was seemingly uneventful. The US Senate passed the United State- Mexico-Canada Agreement (USMCA) and it is currently waiting President Trump’s signature. Things between the US and Iran in the Middle East have calmed down, and stocks have continued their climb to all time highs on the back of better bank earnings.
The World Economic Forum’s annual meeting will be held next week in Davos, beginning on Wednesday. Many world leaders and large companies attend this event, including large oil companies, and it may be good for some potentially market moving soundbites.
With many of the political and geo-political events on the sidelines (for now), the markets next week are likely to begin focusing once again on central banks, macro-economic data and earnings.
There are three Central Bank meetings next week, which include the Bank of Japan, the Bank of Canada, and the European Central Bank.
Earnings season kicks into high gear next week, with such notables reporting as HAL, NFLX, TXN, JNJ, and AXP.
In addition, macro-economic data highlights for next week are as follows:
Monday
- Martin Luther King Jr. Day – US Markets closed
- ECB President Lagarde Speech
Tuesday
- BOJ Interest Rate Decision and Quarterly Outlook Report
- UK Employment data (DEC) Claimant Count expecting +26,000 vs +28,800 last
- German and EU ZEW Economic Sentiment Index (JAN). Expectations are for 15 and 6, respectively.
Wednesday
- Canada Inflation Rate (YoY) (DEC) Expectations are for 2.2% vs 2.2% last
- (MoM) expectation is for 0% vs -0.1% last
- BOC Interest Rate Decision and Monetary Policy Report
Thursday
- Australian Consumer Inflation Expectations (JAN) Expecting 3.7% vs 4% last
- Australian Employment Change (DEC) Expecting +16,000 vs +39,900 last
- ECB Interest Rate Decision, Press Conference, and Strategic Review
- Crude Oil Inventories
Friday
- BOJ Monetary Policy Meeting Minutes
- Worldwide Flash PMIs – In particular, for the US this will be the first piece of manufacturing data since the US-China trade deal was agreed. Markets participants will look closed to watch for an uptick in US PMIs.
- ECB President Lagarde Speech
- Canadian Retail Sales (MoM) (NOV) Expecting 0.4% vs -1.2% last
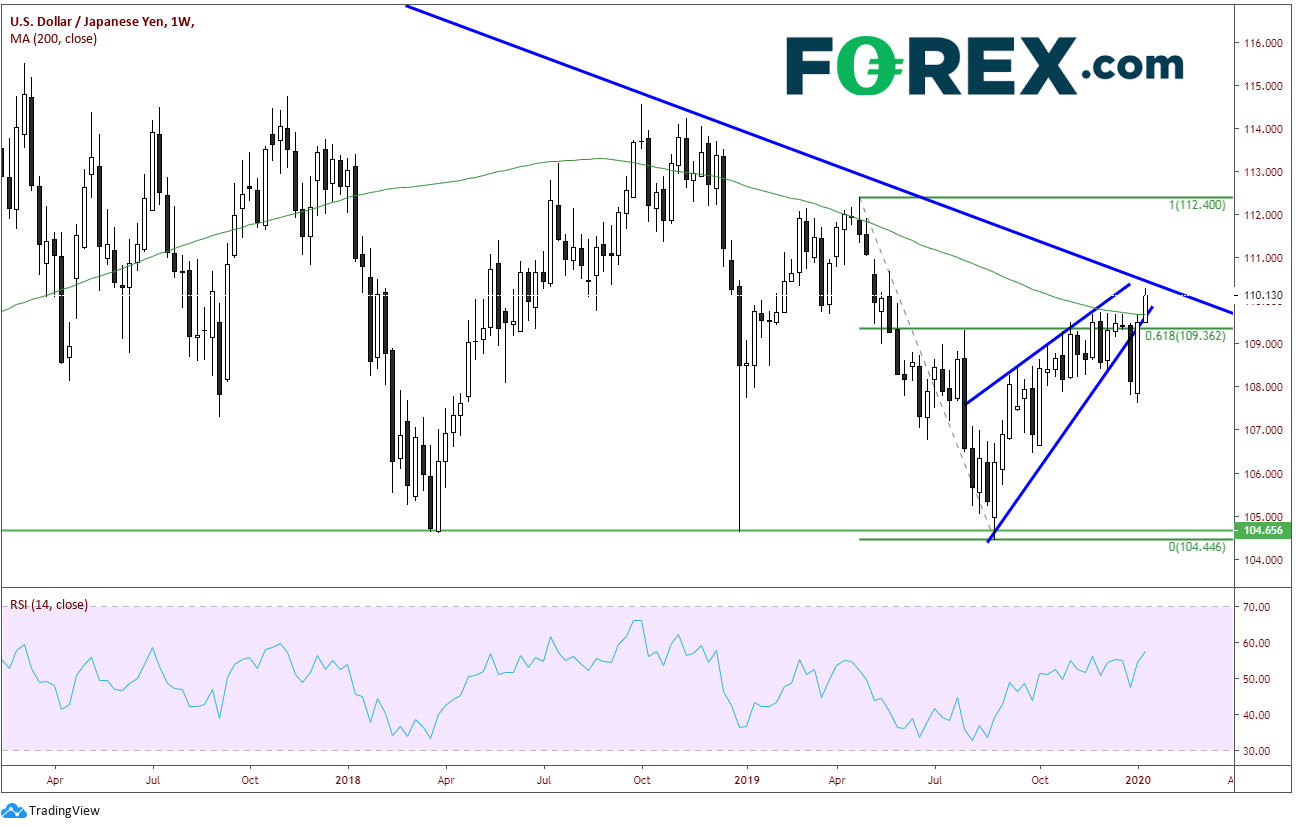
Chart to Watch: USD/JPY
Source: Tradingview, City Index
As stocks continue to put in new all-time highs, USD/JPY is moving right along with them. During the first week of the year, price put in a bullish engulfing candle after a false breakout out of the rising wedge. Last week, USD/JPY squeezed above strong horizontal resistance and the 200-week moving average near 109.70. The pair is currently approaching a long term downward sloping trending dating back to mid-2015. If price breaks above the trendline, it will look to fill the gap from the first week of May 2019 near 110.90/111.00.
Aside from the ceremonial signing of “Phase One” of the US-China Trade Deal, this past week was seemingly uneventful. The US Senate passed the United State- Mexico-Canada Agreement (USMCA) and it is currently waiting President Trump’s signature. Things between the US and Iran in the Middle East have calmed down, and stocks have continued their climb to all time highs on the back of better bank earnings.
The World Economic Forum’s annual meeting will be held next week in Davos, beginning on Wednesday. Many world leaders and large companies attend this event, including large oil companies, and it may be good for some potentially market moving soundbites.
With many of the political and geo-political events on the sidelines (for now), the markets next week are likely to begin focusing once again on central banks, macro-economic data and earnings.
There are three Central Bank meetings next week, which include the Bank of Japan, the Bank of Canada, and the European Central Bank.
Earnings season kicks into high gear next week, with such notables reporting as HAL, NFLX, TXN, JNJ, and AXP.
In addition, macro-economic data highlights for next week are as follows:
Monday
- Martin Luther King Jr. Day – US Markets closed
- ECB President Lagarde Speech
Tuesday
- BOJ Interest Rate Decision and Quarterly Outlook Report
- UK Employment data (DEC) Claimant Count expecting +26,000 vs +28,800 last
- German and EU ZEW Economic Sentiment Index (JAN). Expectations are for 15 and 6, respectively.
Wednesday
- Canada Inflation Rate (YoY) (DEC) Expectations are for 2.2% vs 2.2% last
- (MoM) expectation is for 0% vs -0.1% last
- BOC Interest Rate Decision and Monetary Policy Report
Thursday
- Australian Consumer Inflation Expectations (JAN) Expecting 3.7% vs 4% last
- Australian Employment Change (DEC) Expecting +16,000 vs +39,900 last
- ECB Interest Rate Decision, Press Conference, and Strategic Review
- Crude Oil Inventories
Friday
- BOJ Monetary Policy Meeting Minutes
- Worldwide Flash PMIs – In particular, for the US this will be the first piece of manufacturing data since the US-China trade deal was agreed. Markets participants will look closed to watch for an uptick in US PMIs.
- ECB President Lagarde Speech
- Canadian Retail Sales (MoM) (NOV) Expecting 0.4% vs -1.2% last
Chart to Watch: USD/JPY
Source: Tradingview, FOREX.COM
As stocks continue to put in new all-time highs, USD/JPY is moving right along with them. During the first week of the year, price put in a bullish engulfing candle after a false breakout out of the rising wedge. Last week, USD/JPY squeezed above strong horizontal resistance and the 200-week moving average near 109.70. The pair is currently approaching a long term downward sloping trending dating back to mid-2015. If price breaks above the trendline, it will look to fill the gap from the first week of May 2019 near 110.90/111.00.


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.

USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.


Canadian Dollar Analysis: USD/CAD Returns to July Highs Ahead of NFP
The Canadian dollar continues to face one of its most challenging environments in recent months when it comes to maintaining strength against the U.S. dollar. The weakness of the Canadian currency is clearly reflected in USD/CAD, which has now recorded nine consecutive bullish sessions and gained more than 1.7% during that period.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.