



Snap Q4 earnings preview: Where next for SNAP stock?
Snap was the canary in the coal mine for digital advertising stocks last earnings season.
Share this:

When will Snap release Q4 earnings?
Snap is scheduled to release fourth quarter and full year results for 2022 after US markets close on Tuesday January 31. A conference call will be held on the same day at 1430 PT (1730 ET).
The company will also be holding an investor day on Thursday February 16, when management will provide a presentation on the ‘latest news, company developments, and business highlights’.
Snap Q4 earnings consensus
Wall Street forecasts Snap will report a 0.5% year-on-year rise in revenue to $1.30 billion in the fourth quarter. Adjusted Ebitda is expected to decline 39% from last year to $200.4 million, while its net loss is expected to come in at $188.3 million and turn from a $22.6 million loss.
If Snap meets expectations in the final quarter, then it is on course to deliver a 12% rise in annual revenue in 2022 to $4.6 billion, a 46% drop in adjusted Ebitda to $332.2 million and a net loss more than twice the size of what we saw in 2021 at around $1.33 billion.
Snap Q4 earnings preview
Snap proved to be the canary in the coal mine for the digital advertising market last earnings season after sales growth stalled to single digits for the first time since it went public, which was followed by disappointing results from larger ad rivals like Meta and Alphabet – demonstrating that no company is immune to the slowdown.
However, social media stocks are having a tougher time and taking the brunt of the damage as they are grappling with a myriad of sector-specific headwinds. For example, platforms are still adapting to Apple’s privacy policy update back in 2021 that hurt their ability to target adverts at users, while competition is also intensifying from the likes of TikTok and other new entrants into the digital ad space.
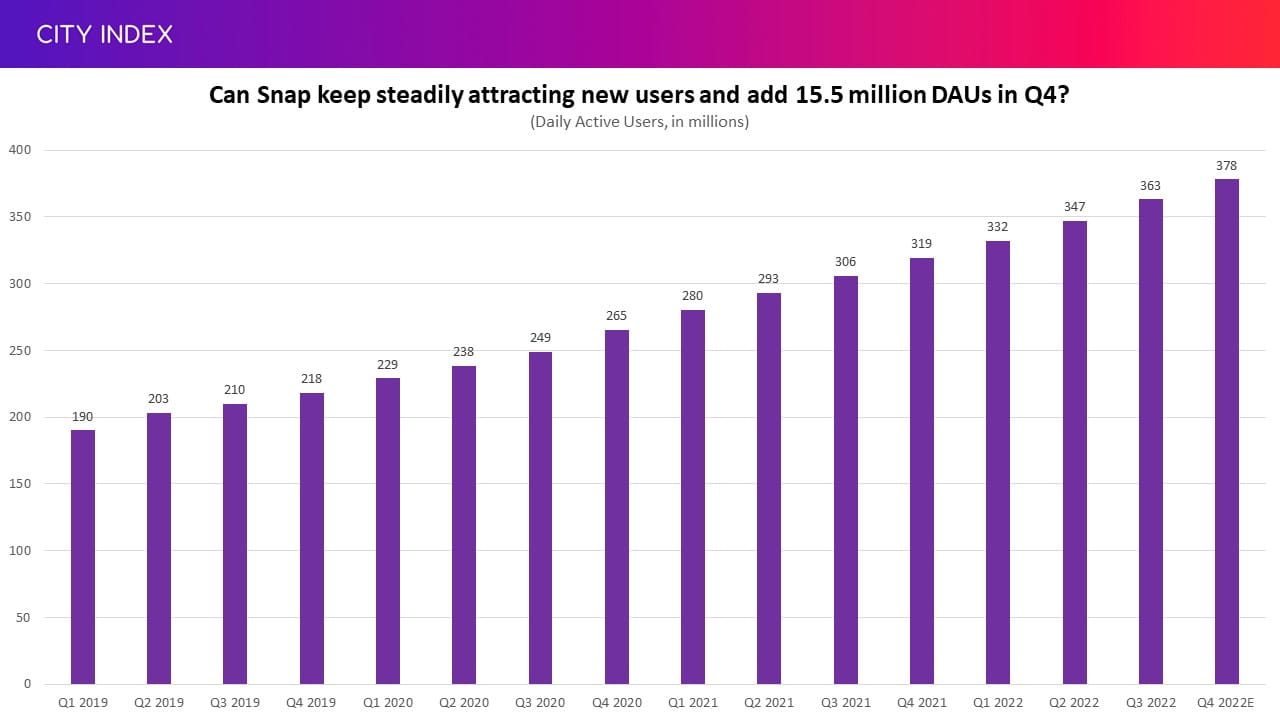
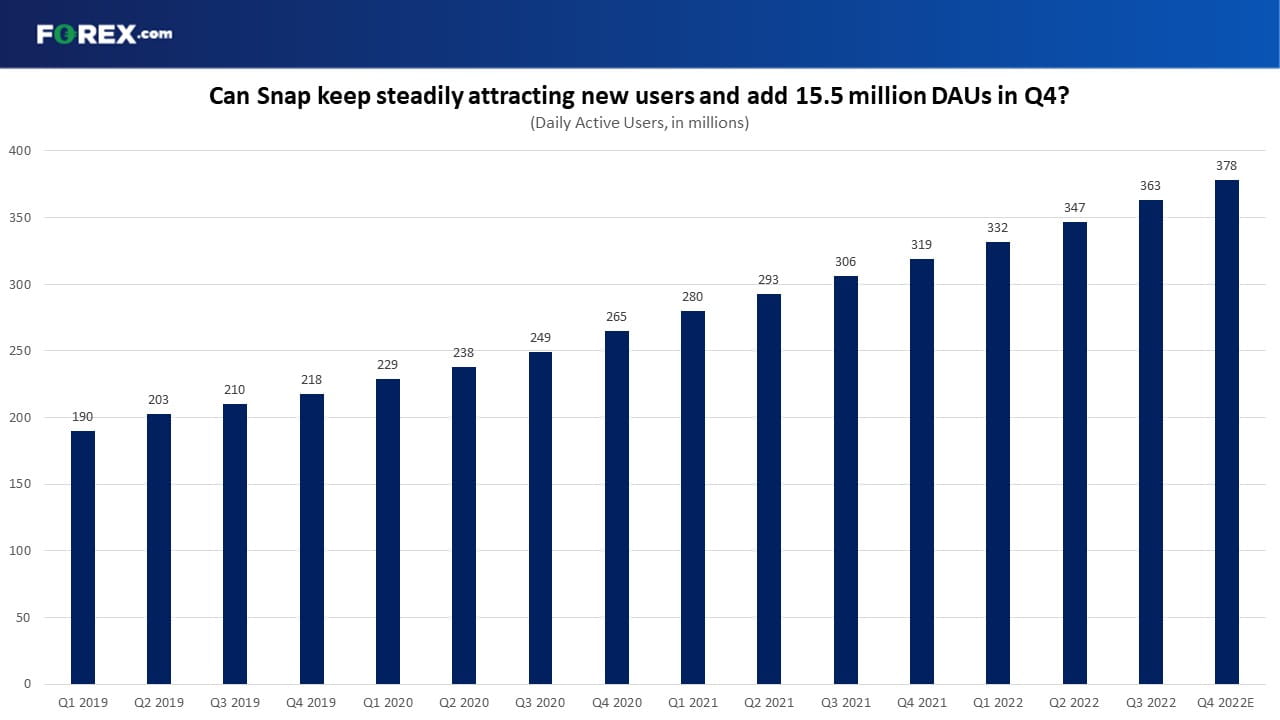
Snap has continued to shine in terms of user growth. Snap is expected to have grown daily active users (DAUs) by 15.5 million in the final three months of the year to end 2022 with 378.47 million of them on its platform.
(Source: Bloomberg)
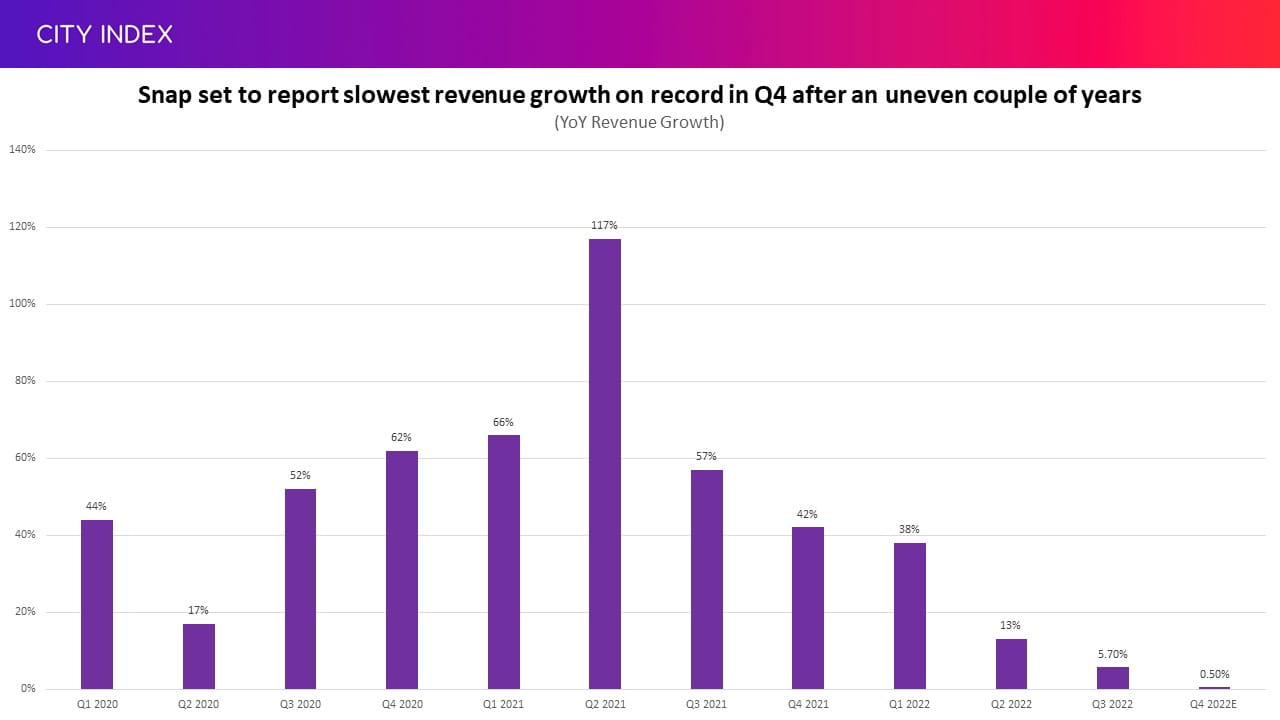
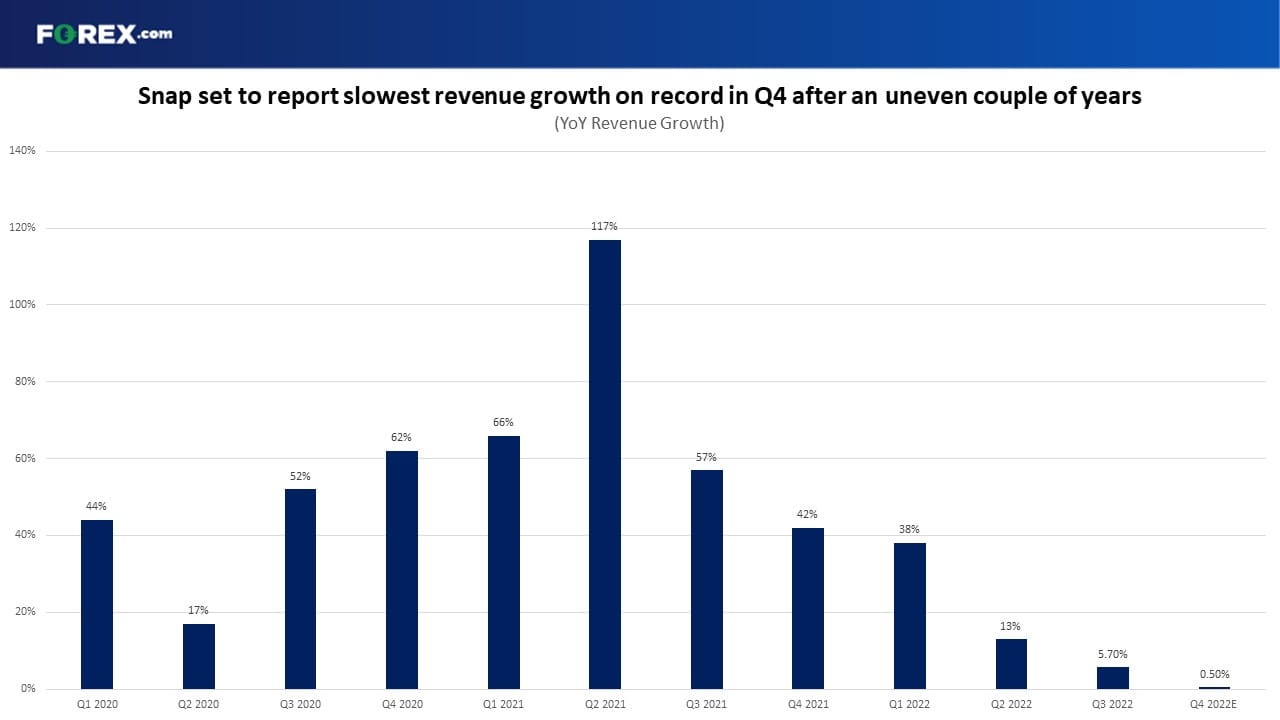
Attracting new users to the platform remains vital in the current environment considering this is the only thing that is growing revenue. The amount of money it earns from each user is under pressure as advertisers pull back on spending and Snap competes with more firms for marketing dollars. Average revenue per user (ARPU) is set to fall 14% from last year to $3.49 in the fourth quarter, and it is falling at a sharper pace where user growth is the strongest. The result will be a tepid 0.5% rise in revenue in the fourth quarter – the slowest pace on record since going public back in 2017.
(Source: Bloomberg)
User growth is also key to its ambition to diversify revenue, which is currently reliant on advertising. For example, its subscription service Snapchat+ that offers exclusive features and tools had 1.5 million subscribers at the end of the third quarter, which represents just a fraction of its total user base. Investors will be hoping this can gain momentum and show its subscription business has real prospects.
Snap will remain in the red once again this quarter, although it is set to report its smallest quarterly net loss of the year. Revenue growth has stalled at a time when costs are surging but Snap is trying to get a grip, having announced last August that it was laying off over 6,000 workers, representing one-fifth of its workforce. Everything from infrastructure costs and the amount it pays to its top content creators to R&D and marketing costs are continuing to rise, although at a slower pace than we saw earlier in 2022.
Although that could demonstrate that Snap is starting to get on top of expenses it is worth noting that Snap has only delivered one quarter of net profit since it has gone public, and Wall Street believes it will remain in the red at the bottom-line for years to come even if adjusted profits improve.
Cashflow is also under strain, but this should be temporary as its cost-cutting efforts start to make an impact. Snap is expected to burn through $6.9 million of cash in the fourth quarter. While that is mild, it will contribute to a cash burn of almost $32 million in 2022.
Snap’s liquidity remains strong considering it should deliver positive cashflow this year and has around $1.9 billion in cash, with a further $2.5 billion of short-term investments it could quickly turn into cash if it needed to. This is demonstrated by the fact it launched a $500 million share buyback in the third quarter, which should help support its valuation and provide some attraction to investors at a time when the share price is being tested by weak fundamentals.
Growth stocks are currently out of favour in the current environment as their prospects that underpin valuations have deteriorated, especially loss-making firms. With growth harder to come by, the best way for them to grab interest is by convincing investors they can cut costs and weather the storm so they can emerge stronger when market conditions bounce back.
What to expect from Snap in 2023
Snap investors hope that they can put 2022 firmly behind them after the fourth quarter results are released. It was the worst year on record for the stock, with the company seeing almost $60 billion wiped-off its valuation. With that in mind, management’s commentary on what to expect in 2023 will prove influential on how markets react.
Snap has refrained from providing formal guidance lately because of the uncertain outlook. Markets believe Snap’s user numbers will continue to grow at double-digit rates this year, revenue growth is forecast to begin accelerating again from the current quarter, adjusted Ebitda is also expected to improve this year, while analysts also anticipate it will generate record cash in 2023. Easier comparatives from the tough 2022 will be a big factor but it should get Snap back on a more even and steady road following the ups and downs seen in the last two to three years.
The uncertain outlook means these estimates are geared toward the downside, but that also provides an opportunity for Snap to perform even better should the soft-landing markets are hoping for plays out.
Where next for SNAP stock?
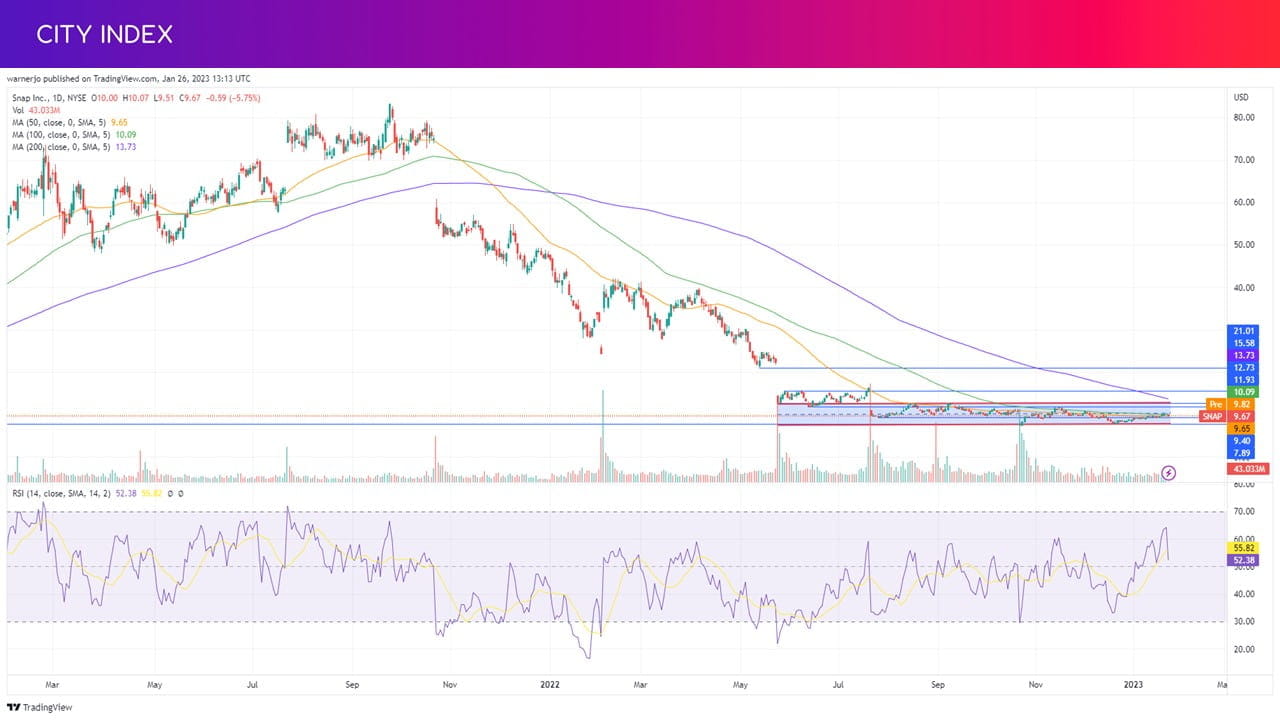
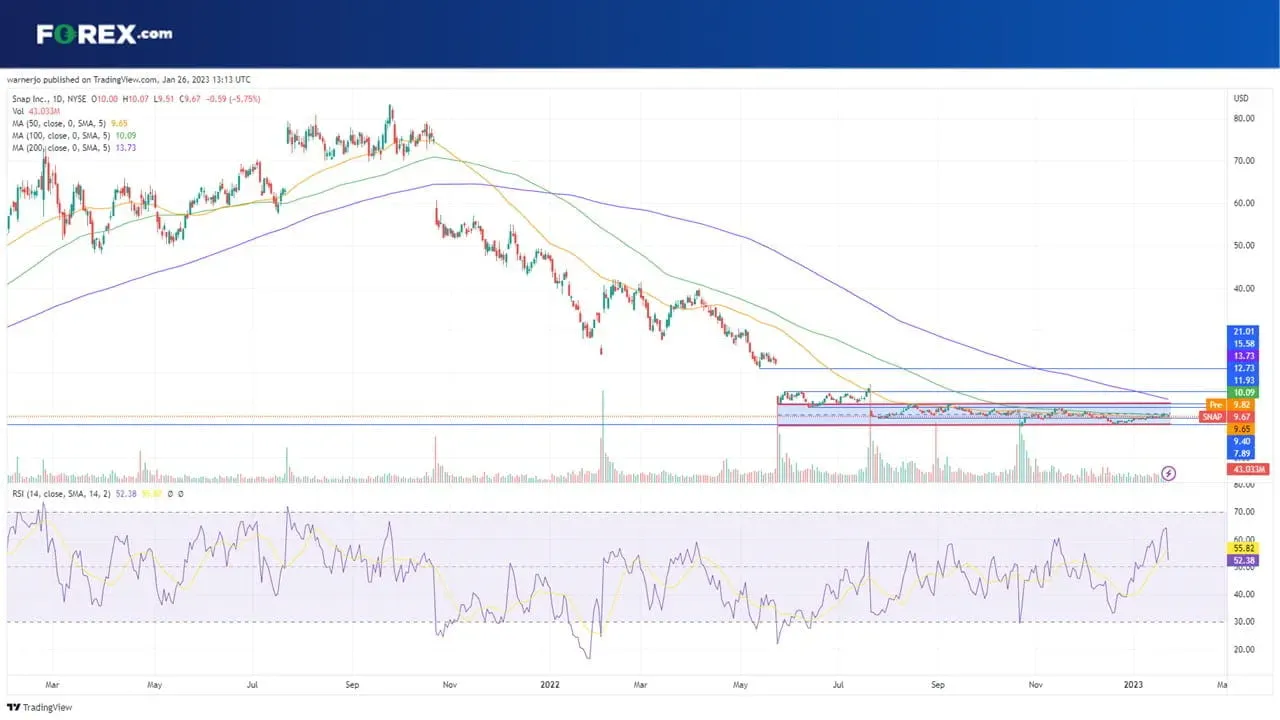
Snap shares have traded within a channel between $12.65 and $8.20 over the past six months, representing the targets needed to be breached to break out of it.
The stock is currently testing both the 50-day and 100-day moving averages. A move above $10 would allow these to be recaptured before it can look to move up to $12 and then eye the top of the channel. The 42 brokers that cover the stock have an average target price of $11.68.
We could see $9.40 provide some support if the stock comes under pressure and the floor of the channel should hold considering this is aligned with the low seen when the pandemic derailed financial markets back in March 2020.
Take advantage of extended hours trading
Snap will release earnings after US markets close and most traders must wait until they reopen the following day before being able to trade. But by then, the news has already been digested and the instant reaction in share price has happened in after-hours trading. To react immediately, traders should take their positions in pre-and post-market sessions.
With this in mind, you can take advantage of our service that allows you to trade Snap and other tech stocks using our extended hours offering.
While trading before and after hours creates opportunities for traders, it also creates risk, particularly due to the lower liquidity levels. Find out more about Extended Hours Trading.
Take advantage of extended hours trading
Snap will release earnings after US markets close and most traders must wait until they reopen the following day before being able to trade. But by then, the news has already been digested and the instant reaction in share price has happened in after-hours trading. To react immediately, traders should take their positions in pre-and post-market sessions.
With this in mind, you can take advantage of our service that allows you to trade Snap and other tech stocks using our extended hours offering.
While trading before and after hours creates opportunities for traders, it also creates risk, particularly due to the lower liquidity levels. Find out more about Extended Hours Trading.
How to trade Snap stock
You can trade Snap shares with City Index in just four easy steps:
- Open a City Index account, or log-in if you’re already a customer.
- Search for ‘Snap’ in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Or you can practice trading risk-free by signing up for our Demo Trading Account.
You can trade Snap shares with Forex.com in just four steps:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for ‘Snap’ in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Or you can practice trading risk-free by signing up for our Demo Account.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US dollar outlook: Nasdaq breakdown raises stakes for EUR/USD, USD/JPY
A potential Democratic sweep of Congress is adding to the AI trade's headaches, with Nasdaq 100 futures breaking below a major technical level. The implications for the dollar could be significant.
US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.

Nasdaq 100 forecast: Stocks rebound but AI concerns linger
The Nasdaq 100 was finding some support at 28,000 after recent sell-off amid concerns about the AI trade. Even with oscillators oversold, the risk to the near-term forecast is tilted to the downside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.