

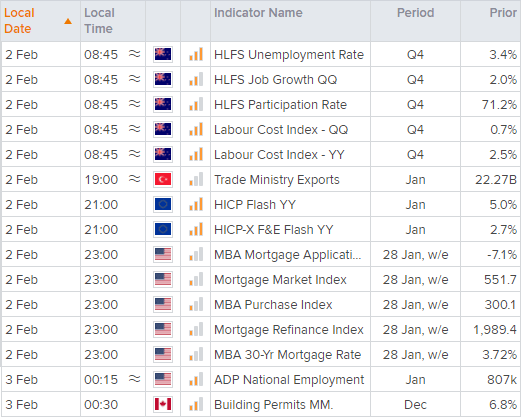


Asian Open: NZ unemployment falls to a new record low
New Zealand's jobs report saw unemployment fall for a fifth consecutive quarter to a fresh record low of 3.2%.
Share this:
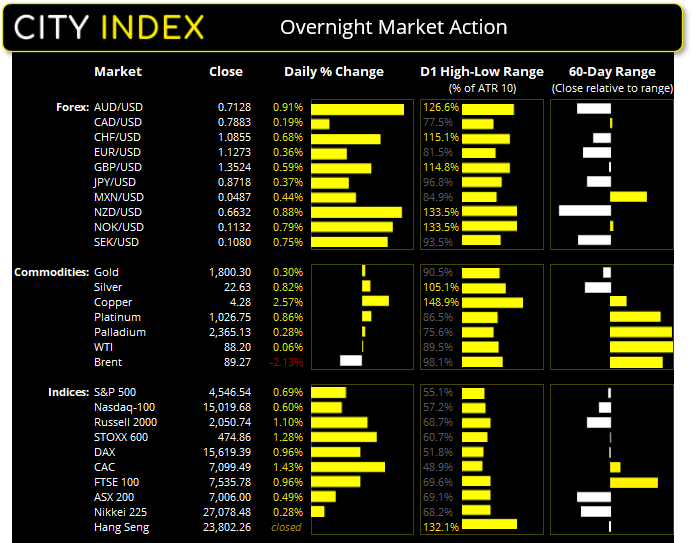
Tuesday US cash market close:
- The Dow Jones Industrial rose 273.38 points (0.78%) to close at 35,405.24
- The S&P 500 index rose 30.99 points (0.69%) to close at 4,546.54
- The Nasdaq 100 index rose 89.624 points (0.6%) to close at 15,019.68
Asian futures:
- Australia's ASX 200 futures are up 55 points (0.8%), the cash market is currently estimated to open at 7,061.00
- Japan's Nikkei 225 futures are up 130 points (0.48%), the cash market is currently estimated to open at 27,208.48
- Hong Kong's Hang Seng futures are down 0 points (0%), the cash market is currently estimated to open at 23,802.26
- China's A50 Index futures are up 3 points (0.02%), the cash market is currently estimated to open at 14,772.78
Wall Street extends it rally (on declining volumes…)
US indices rose for a third day although upside volatility was the lowest of the 3-days. Whilst it’s nice to see equities rise after a drubbing we also remain mindful of the fact they rise on lower volumes. The jury remains out as to whether this is the early stages of a bull rally or simply a bear0market bounce. The S&P 500 rose 0.7% to the Nasdaq’s 0.6%, and the Dow led the way with a 0.8% gain.
Antipodeans take advantage of a weak greenback
The New Zealand dollar retained its place at the top spot yesterday after another strong unemployment print, although the Kiwi and Aussie dollars were already strong due to a weaker dollar. Unemployment hit a new low of 3.2%, although employment change underwhelmed by only growing 0.1%, below 0.3% expected and the 2% prior. Labour costs also rose 0.7% q/q and 2.8% y/y. The Kiwi dollar has experienced its fair share of selling these past few weeks and it has allowed some breathing room to rebound from cycle lows against all majors except AUD.
The dollar continues to correct
US dollar index was lower for a third day with some Fed members helping to keep it under pressure. Bullard thinks the next job report “will not be good” whilst also stating that a 50 bps hike would help the Fed. Coming form a hawk, that should be taken note off if you’re hanging your hat on such a hike in March.
US manufacturing slows to a 14-month low
ISM manufacturing expanded at its slowest rate in 14-months, down to 57.6 from 57.9. Whilst it continues to signal that growth has topped it does remain above its long-term average of 53. New orders slipped to a 19-month low of 57.9 whilst prices paid (inflation component) rose to a 2-month high of 76.1, which remains relatively high to its long-term average of 60.
Gold toys with its 200-day eMA
Gold rose to a 3-day high of 1808, meaning it reached both of our near-term upside targets. Yet the 200-day and 50-day eMA’s continues to cap as resistance, and the market is on track for a bearish hammer on the daily chart. The four-hour chart shows the monthly pivot point and 38.2% Fibonacci retracement is also acting as resistance, whilst the market also trades in a tight bullish channel into resistance.
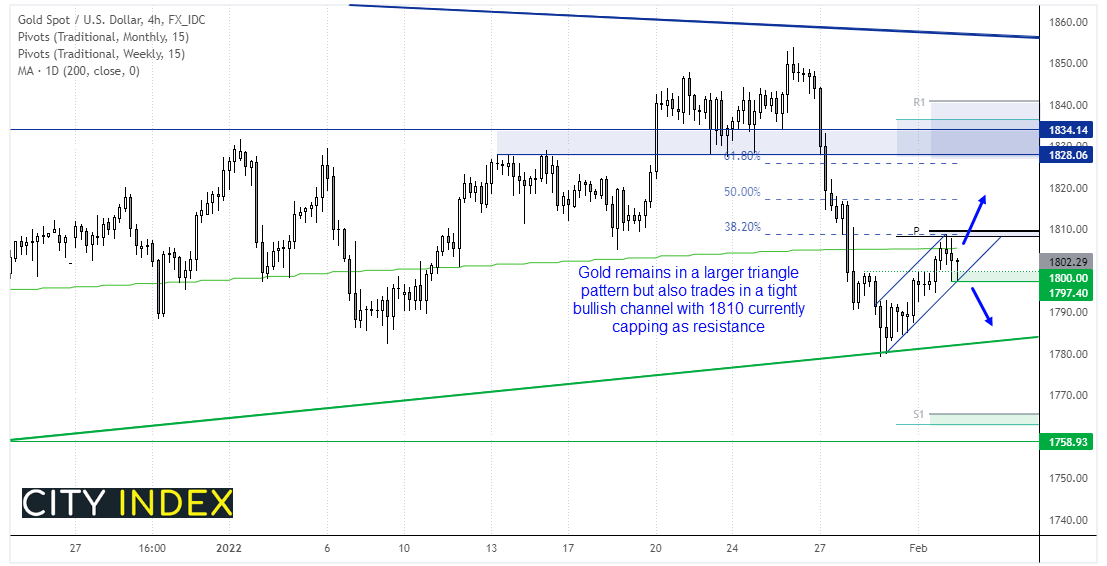

This leaves two potential outcomes; prices could hold the channel and break above 1810 to hint at trend continuation on the four-hour chart. Or bears return and break below 1797 out of the channel, which makes the 1797 - 1810 range of importance over the near-term. Given gold is only up against the US dollar (and lower against all other majors), and real yields rose overnight we’re leaning towards a downside break. But that is not reason to not be on guard for either scenario.
ASX 200 closed above 7,000 (just)
The ASX 200 managed to scrape a close above 7,000, yet the 7042.80 high capped as resistance which reaffirms the level’s importance. Whilst prices are rising it could simply be part of a dead-cat bounce whilst upside volatility remains underwhelming.
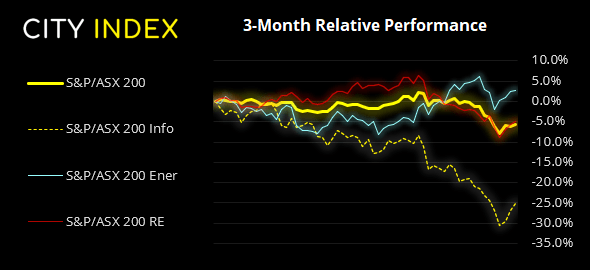
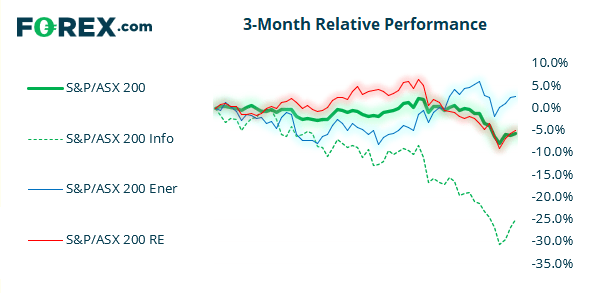
ASX 200: 7006 (0.49%), 1ST February 2022
- Utilities (2.57%) was the strongest sector and Materials (-1.21%) was the weakest
- 10 out of the 11 sectors closed higher
- 1 out of the 11 sectors closed lower
- 9 out of the 11 sectors outperformed the index
- 35 (17.50%) stocks advanced, 155 (77.50%) stocks declined
Outperformers:
- +7.28% - Pendal Group Ltd (PDL.AX)
- +6.56% - Judo Capital Holdings Ltd (JDO.AX)
- +6.45% - Imugene Ltd (IMU.AX)
Underperformers:
- ·-5.42% - Genesis Energy Ltd (GNE.AX)
- ·-3.06% - BHP Group Ltd (BHP.AX)
- ·-2.48% - Brambles Ltd (BXB.AX)
Up Next (Times in AEDT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.