





AUD/USD rises, EUR/USD, USD/CAD dip, US dollar selloff loses steam
The combination of tariff fatigue, extended moves and a refreshing set of softer CPI figures helped appetite for risk peel itself from the ropes it had been pinned to in recent weeks. And that helped AUD/USD rise for a second day and USD/CAD fall below resistance, while EUR/USD bulls paused for breath around a key high.
Share this:
View related analysis:
- Nasdaq 100 Forecast: Asset Managers Ramp Up Bearish Tech Bets
- EUR/USD forecast: Its pre-ECB surge did not come without a warning
- Bullish Bets on the Euro and Yen Continue to Rise: COT Report
- AUD/USD weekly outlook: 10 March 2025
View related analysis:
- Nasdaq 100 Forecast: Asset Managers Ramp Up Bearish Tech Bets
- EUR/USD forecast: Its pre-ECB surge did not come without a warning
- Bullish Bets on the Euro and Yen Continue to Rise: COT Report
- AUD/USD weekly outlook: 10 March 2025
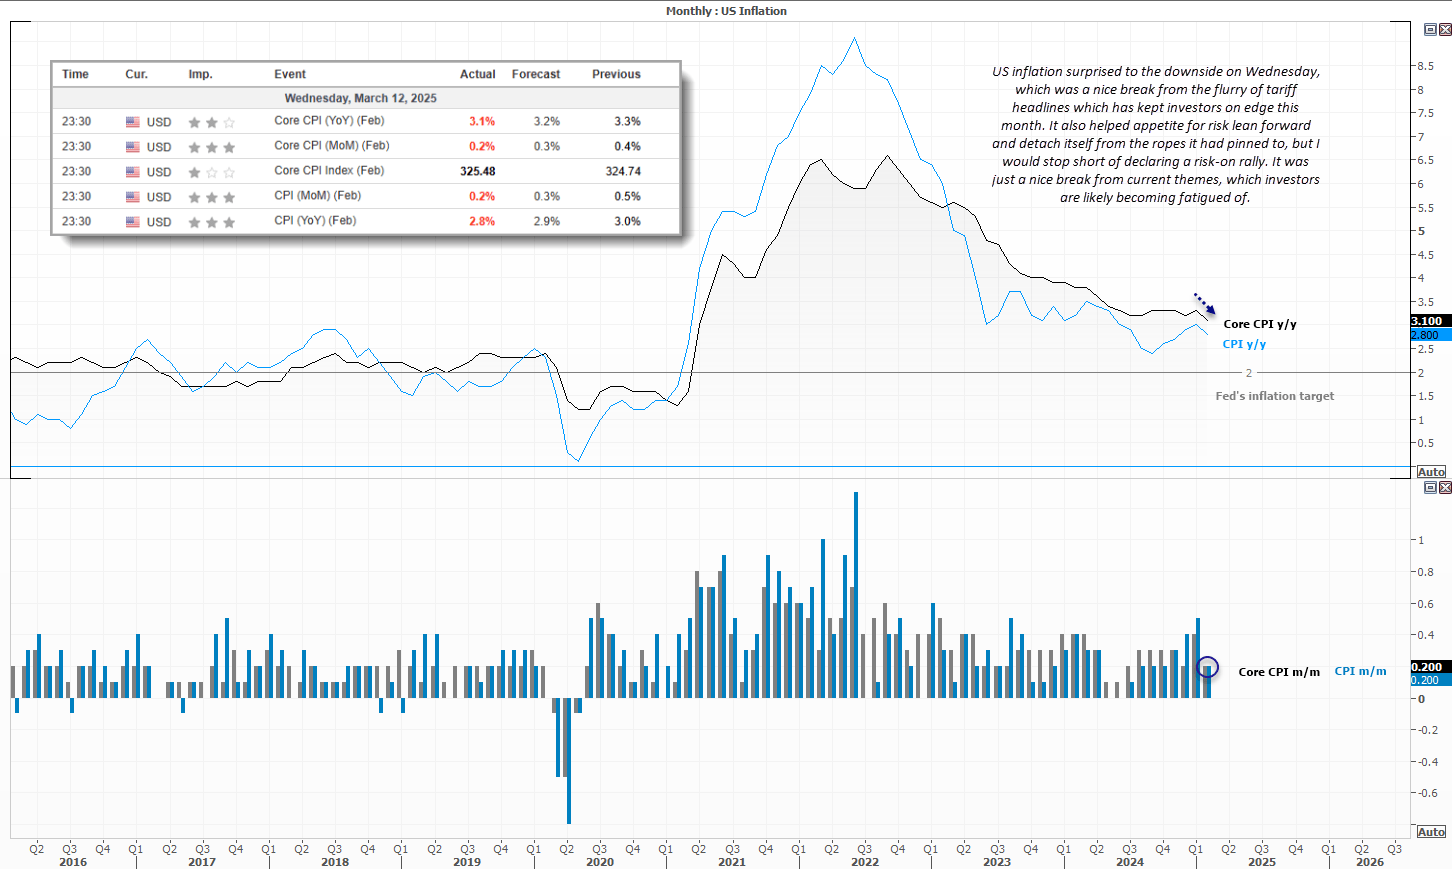
US inflation surprised to the downside on Wednesday, which was a nice break from the flurry of tariff headlines which has kept investors on edge this month. It also helped appetite for risk lean forward and detach itself from the ropes it had pinned to, but I would stop short of declaring a risk-on rally. It was just a nice break from current themes, which investors are likely becoming fatigued from.
Core CPI rose 0.2% m/m in February, below 0.3% expected and 0.4% prior. It also slowed to 3.1% y/y, below 3.2% expected and 3.1% prior. Still, this is a minor victory with tariffs being rolled out and weaker consumer sentiment and growth prospects for the US and global economy.
The Canadian dollar was the strongest FX major on Wednesday after the Bank of Canada (BOC) delivered a less-than-dovish 25bp cut, taking their cash rate to 2.75%. Noting that the economy will be subject to more uncertainty than usual, they will be carefully assessing the strength of upwards and downwards inflation and monitoring inflation expectations more closely. This is exactly in line with my own expectations in light of tariffs, which force central banks to take a more cautious approach to easing as they battle the contrasting themes of lower growth and rising inflation.
Economic events in focus (AEDT)
- 08:45 – New Zealand visitors and migrations
- 10:50 – Japanese foreign stock and bond purchases
- 11:00 – Australian inflation expectations (Melbourne Institute)
- 11:30 – Australian building approvals
- 13:00 – RBA Assistant Governor Jones speaks
- 18:30 – Swiss Producer Prices
- 20:50 – ECB’s de Guindos Speaks
- 21:00 – EU Industrial Production
- 23:30 – US Core Producer Prices
US 2-year, US dollar index, EUR/USD technical analysis
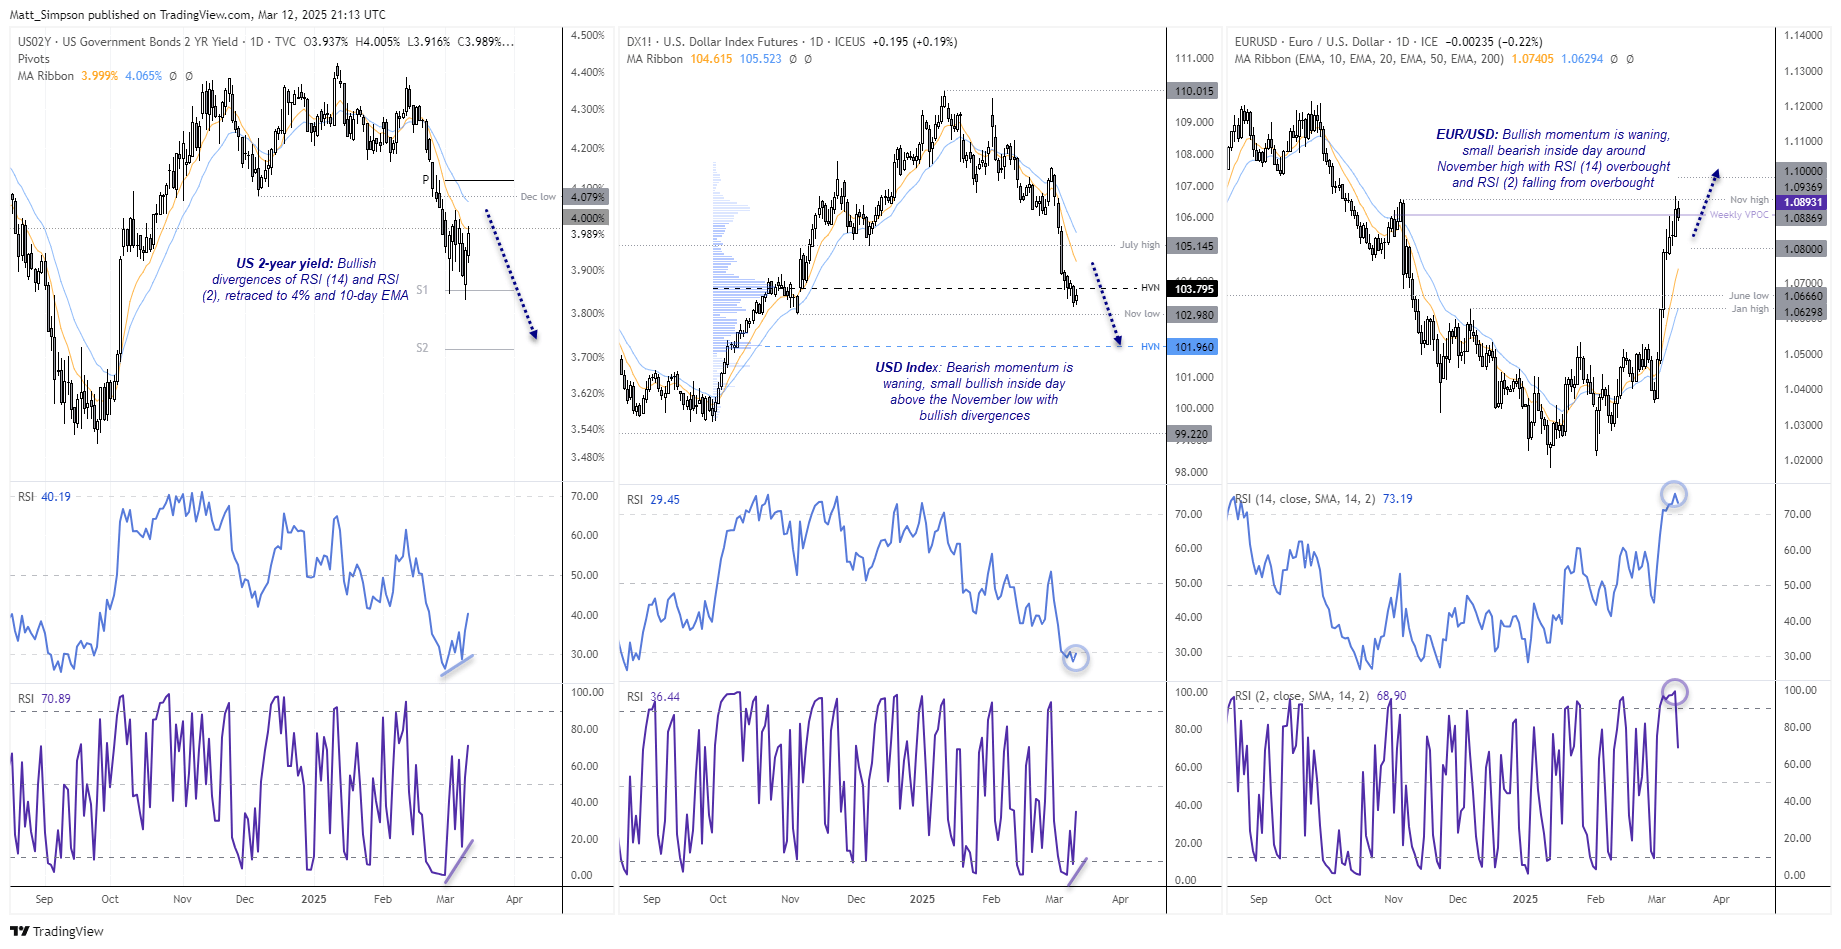
Tariffs have been the predominant driver for currency sentiment in recent weeks, over yield differentials. But with the US 2-year yield building a base and the likelihood of ‘tariff fatigue’ creeping in, perhaps they will begin to take some notice for a brief while. The US 2-year yield has formed a double bottom around its monthly S1 pivot and retraced back up to its 10-day EMA, with bullish divergences on the daily RSI (14) and RSI (2) forming on the daily chart in the oversold zone. If the US 2-year continues to retrace higher or consolidate, it bolsters the case for a pullback higher on the US dollar index and retracement lower on EUR/USD over the near term.
By Tuesday’s low, the US dollar index had fallen -6.2% from its January high which places it in a similar depth to the two prior pullbacks of the past two years. And yesterday’s small bullish inside day shows a slight hesitancy for it to test the November low. The RSI (14) is heavily oversold and a bullish divergence is forming on the daily RSI (2). While prices could still have a stab at the 103 handle, the oversold conditions of the US dollar alongside retracing yields to me suggests we could be approaching a small inflection point higher on the USD index
EUR/USD reached my 1.09 target on Tuesday and also briefly traded above the November high by a cats-whisker. Yet a small bearish inside day formed on Wednesday to show euro bulls pausing for breath before reconsidering their move to 1.10. This Is not really a cause for alarm to the bullish structure, but with prices pausing at such a key high then it is perfectly plausible to expect even a minor shakeout from current levels before the move resumes.
USD/CAD, AUD/USD technical analysis
Commodity FX took advantage of ongoing tariff discussions between the US and Canada, with CAD, AUD and NZD being the strongest majors on Wednesday. And we could find their strength continues should Canada walk away with more favourable terms than the 50% levy on steel and aluminium that Trump threatened them with.
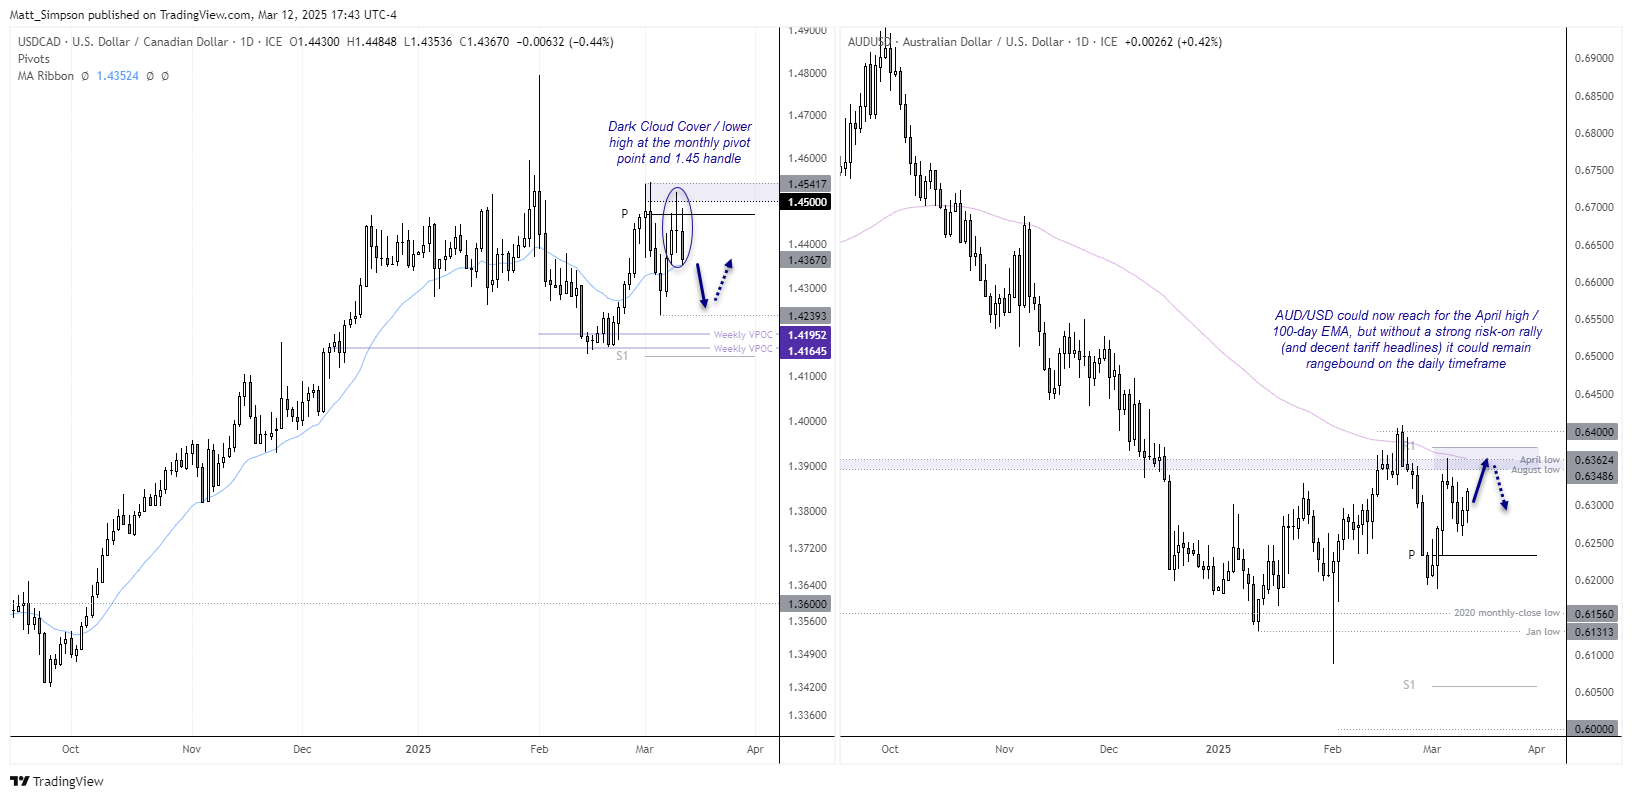
USD/CAD was lower in line with my bias after the BOC shed doubt over further cuts, although it has found support at the 20-day EMA. Still Tuesday’s doji is also a lower high, and yesterday’s bearish range expansion means a dark cloud cover pattern has now formed which will be confirmed with a break beneath yesterday’s low. Bears could target 1.43, break of which brings the 1.4239 low into focus.
AUD/USD rose for a second day and closed above 63c. If Wall Street and pick itself up further from its lows, AUD/USD could be headed for the April high and 100-day EMA around 0.6362. But we’d likely need a surprisingly good set of risk-on tariff headlines before we can expect a retest or break of 64c. And that could see AUD/USD remaining trapped in range for the foreseeable future.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.