



Dollar forecast: All eyes on bond markets
Ultimately, unless yields start to head lower, the pressure will likely remain on the US dollar, with currencies of countries with better fiscal discipline, like the Norwegian Krone and Swiss franc, likely to remain supported. This makes the USD/NOK our favourite currency to take advantage of the slump in the dollar.
Share this:
The US dollar has bounced back a tiny bit following last week’s sharp decline when currencies of countries with better fiscal discipline outperformed the greenback. The so-called 'debasement' trade will be put to test this week with fresh policy updates from the US government. Markets will be eyeing some sort of fiscal consolidation plan following last week’s stress in the Treasury market. Kevin Warsh's speech on Friday could also prove decisive for the dollar forecast. Ultimately, unless yields start to head lower, the pressure will likely remain on the US dollar, with currencies of countries with better fiscal discipline, like the Norwegian Krone and Swiss franc, likely to remain supported. This makes the USD/NOK our favourite currency to take advantage of the slump in the dollar.
Watch bond markets
The big story last week was the unexpected announcement of the bond buyback of at least $4 billion per operation. But that announcement only caused a temporary drop in yields. The US 10-year and 30-year yields quickly rebounded from their initial decline. In response, Treasury Secretary Scott Bessent said there is a 'bigger toolkit' in an attempt to calm nerves.
The dollar remains largely out of favour despite a small bounce back at the start of this week, in what still is a pro-risk, soft-dollar environment. But the potential is there for a sharper sell-off in the dollar as the so-called ‘debasement’ trade returns.
That view could be put to the test this week with the prospect of fiscal consolidation flagged by Bessent last week. Few expect meaningful spending cuts or tax increases, give the Trump administration’s pro-growth policies.
Ultimately, a more structural solution — particularly fiscal consolidation — would be needed to deliver a sustainable improvement in the bond market. But the message that the Treasury is prepared to be more active in managing conditions at the long end has nevertheless been welcomed by investors.
Still, if oil continues higher, this will surely be bad news for bonds as the inflation worries remain front and centre. That, in turn, could see the dollar remaining under pressure against currencies where fiscal discipline is taken more seriously. The likes of the Swiss franc, Norwegian krone, and several commodity dollars. Against the Japanese yen, though, the dollar may well hold its own relatively well.
Treasury to announce new sanctions on Iran
The US Treasury Secretary is due to hold a press conference about new US sanctions and economic measures against Iran. If the measures appear to be quite severe, this will likely see Tehran retaliate and potentially strike US bases in the Middle East, prolonging the conflict and causing further disruptions to energy supplies.
The key question is whether the new Iran measures once again threaten US trade relations with China, which remains the largest buyer of Iranian energy exports. Any significant re-escalation of the tariff war would probably be negative for the dollar.
Core PCE among key data highlights this week
The core PCE price index is due on Wednesday, August 26. If recent CPI and PPI inflation data is anything to go by, Core PCE inflation should also be weaker than expected. But this is the Fed’s favourite inflation measure, and any surprises could have important implications for monetary policy.
Warch speaks at Jackson Hole on Friday
At the Jackson Hole summit Kevin Warsh's first major speech as Fed Chair will be watched closely. While he is unlikely to say much as his aversion to forward guidance is well known, he could still alleviate pressure from rising bond yields by acknowledging recent weakness in US data.
But Warsh will be under pressure to reinforce the Fed’s inflation-fighting credentials. Unless Warsh manages to reverse the course in bond yields, the dollar could remain under pressure.
Dollar index key levels to watch
Having bounced off the 98.55/60 area of support, the dollar index faces key resistance starting around 99.16 level, to around 99.50 region. Prior lows and the 200-day average all meet there.
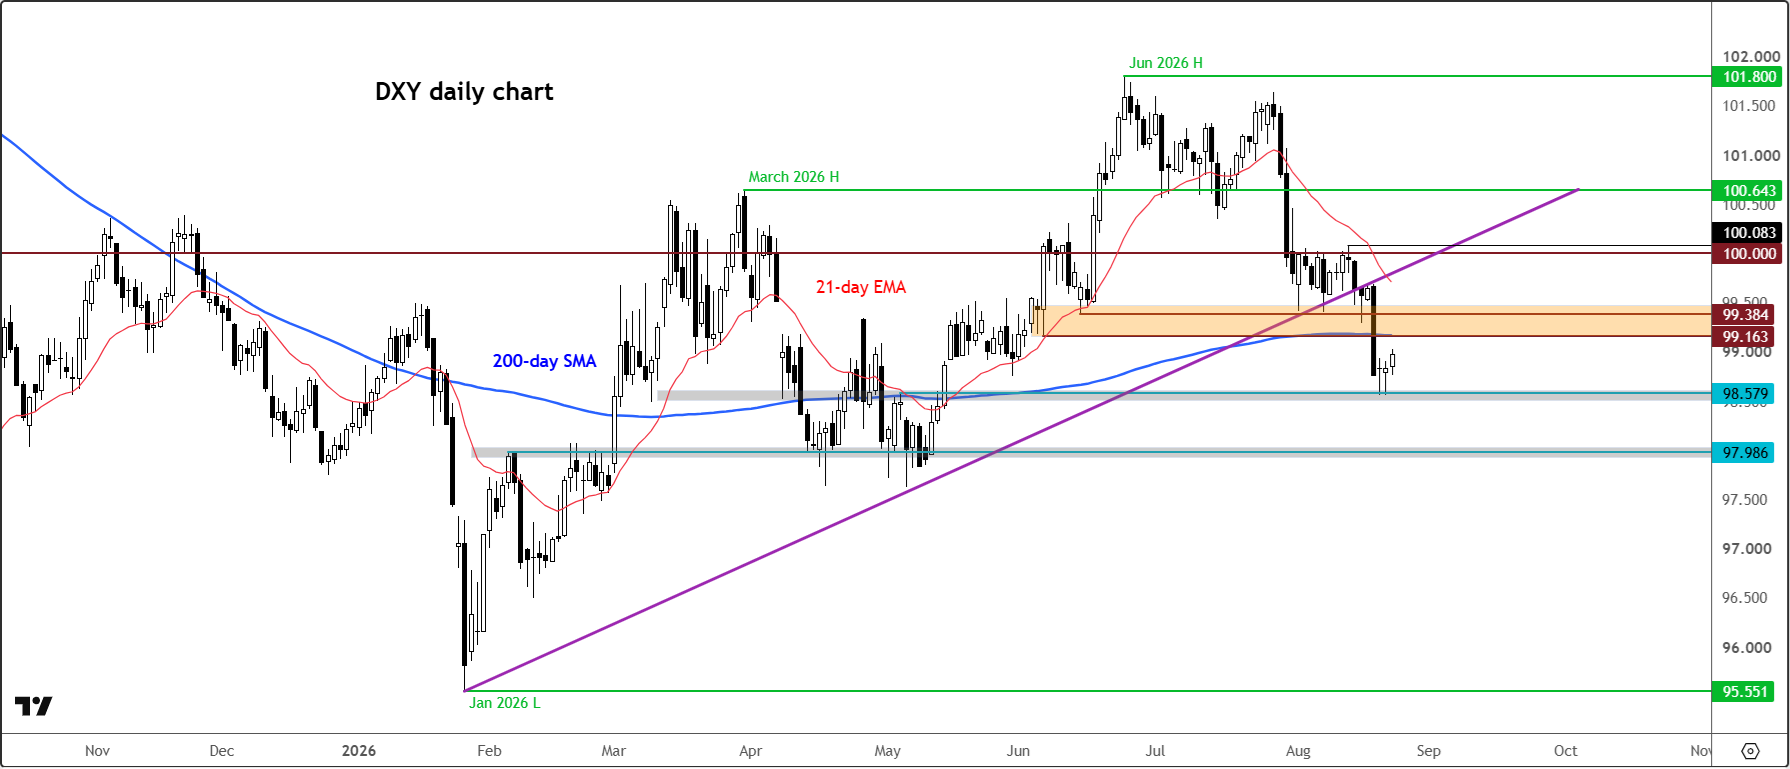
For the dollar forecast to turn positive, the DXY will need to reclaim its broken trend line now and climb back above the 100.00 level. Should the selling continue, the next potential support below the recent lows come in around 97.95-98.00 area. Then, round handles will be in focus next like 97.00, 96.00 etc.
USD/NOK is the currency pair of the week
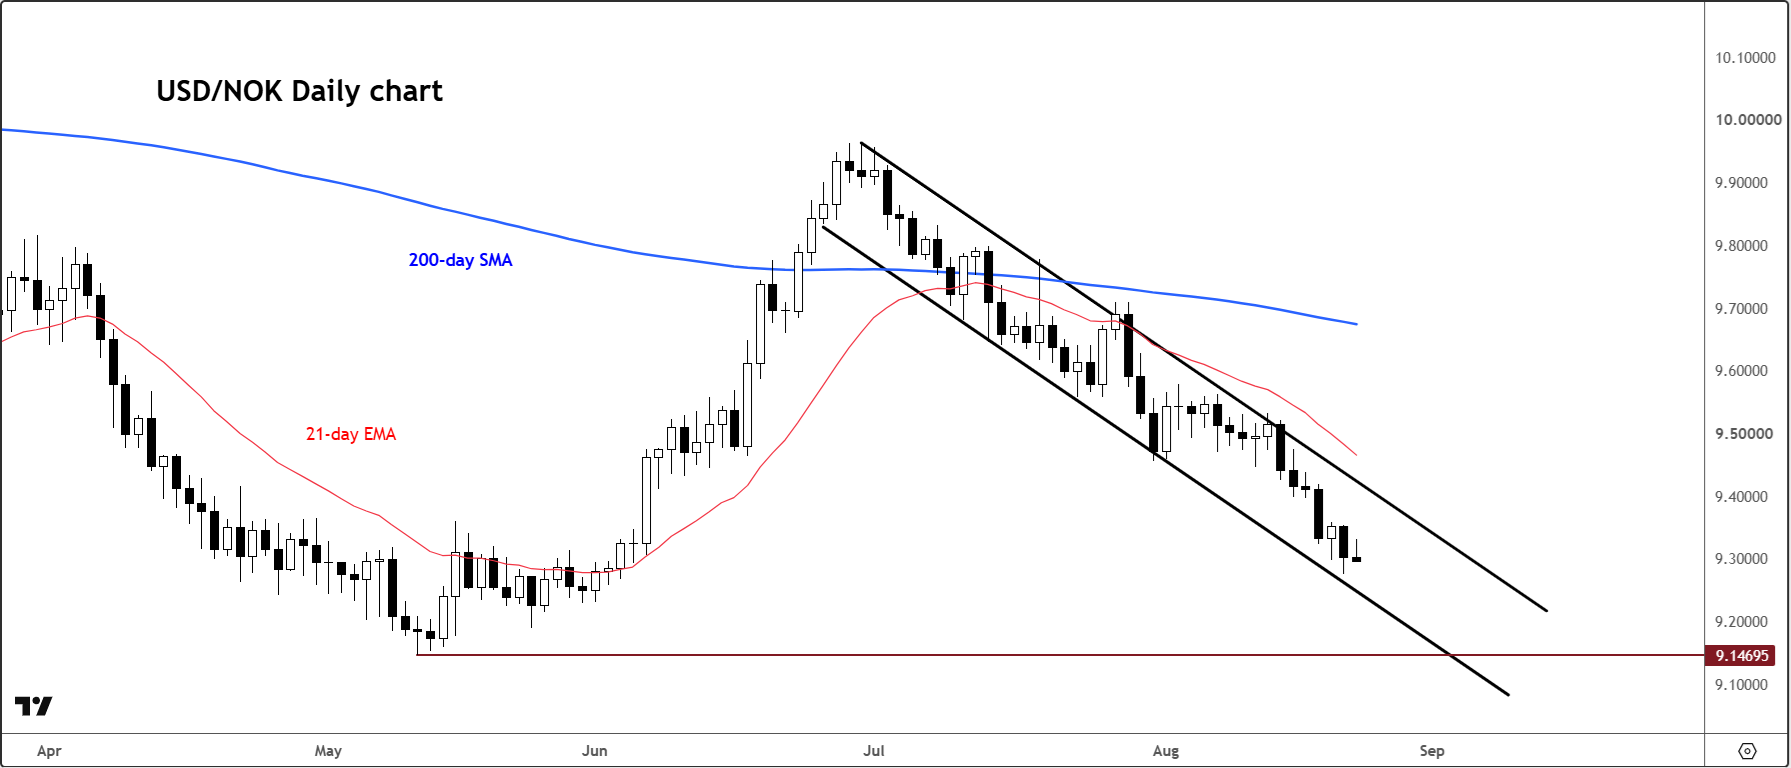
Not necessary because of any data but about what I mentioned above, namely fiscal discipline. The bearish trend on the USD/NOK is certainly growing, so watch out below!

Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.