



RBA Hikes, Signals More to Come as Inflation Stays Sticky
The RBA is back hiking, lifting rates to 3.85% as expected. With inflation forecasts refusing to cooperate, markets are now bracing for more tightening as Governor Bullock prepares to face the media.
Share this:
- RBA Cash rate lifted 25bp to 3.85%, first hike since Nov 2023
- Inflation forecasts signal price pressures remain sticky
- Markets now price further hikes this year
- AUD jumps back above 0.7000
- Bullock presser at 3.30pm the next key risk even
The RBA is back hiking. A 25bp move lifts the cash rate to 3.85% for the first time since November 2023, as expected, but the real signal sits in the forecasts. With inflation projected to stay sticky, the door is open to multiple hikes this cycle, putting extra focus on Governor Michele Bullock’s 3.30pm press conference.
RBA Hawks Circle
On inflation, the RBA’s language clearly hardened relative to December. Then, the Board stressed uncertainty, saying inflation had “picked up more recently,” with only “some signs” of a broader lift and an emphasis on monitoring persistence. In February, that conditional framing is gone. Inflation is now described as having “picked up materially in the second half of 2025,” with the increase tied directly to “greater capacity pressures” and an explicit judgement that inflation is “likely to remain above target for some time.”
The labour market story has also shifted. December acknowledged conditions were “a little tight” but leaned on easing dynamics, pointing to rising unemployment, slower employment growth and “further modest easing” ahead. February removes that bias. Labour market conditions are deemed still “a little tight,” but are now said to have “stabilised,” with unemployment “a little lower than expected.” References to easing or slowing momentum were dropped.
On productivity, December relied on indirect signals, but February was more direct. While productivity is still not mentioned explicitly, the Board now says growth in the economy’s “supply capacity remains limited,” and that capacity pressures are “greater than previously assessed,” shifting constraints from a risk to a reality.
Finally, its language on economic growth strengthened noticeably. December framed activity as a recovery, with private demand having “strengthened” and momentum better than expected. February sharpens this materially, saying private demand has strengthened “substantially more than expected” and is “growing more quickly than expected,” explicitly linking stronger growth to rising capacity pressures.
Inflation Sticky, Higher for Longer
That firmer assessment is reflected clearly in the updated forecasts, which quietly point to a more extended tightening phase than the February hike alone would suggest.
Source: RBA
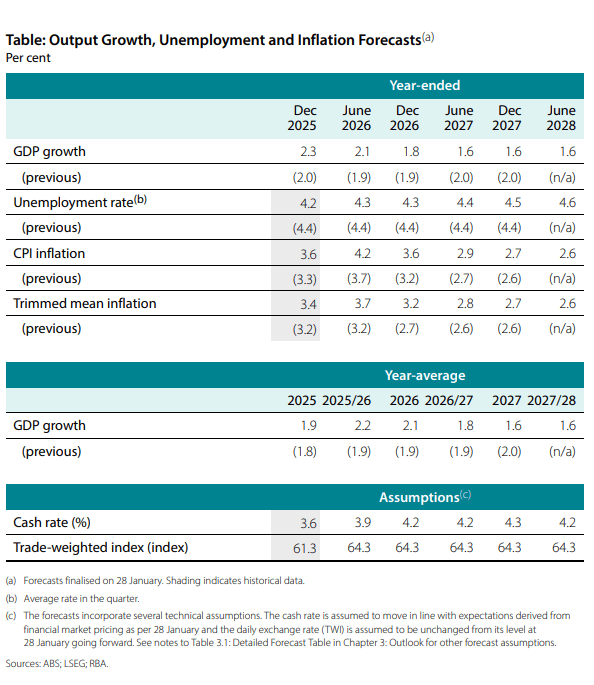
The big takeaway is that February looks unlikely to be a one-and-done. The RBA’s updated trimmed mean inflation forecasts do not show inflation returning to the 2.5% midpoint of its 2–3% target range by mid-2028, even after factoring in a stronger Australian dollar, lower crude oil prices and an assumption that the cash rate peaks at 4.3% in the final quarter of 2027.
Notably, the profile implies trimmed mean inflation running at 0.9% in each of the next two quarters, underlining the Bank’s concern that disinflation remains slow.
With the cash rate at 3.85%, that forecast path implies the Bank may ultimately unwind all three rate reductions delivered in 2024.
Consistent with policy remaining restrictive for longer, the RBA has revised down its GDP forecasts, with growth expected to slow to 1.6% from the middle of next year, down from 2% previously. The unemployment rate is forecast to drift higher over the projection period, reaching 4.6% by mid-2028, although the outlook for this year was trimmed slightly to 4.3%.
While the Bank is using market pricing to generate these forecasts, the detail sends a clear implicit signal: returning inflation to target under current conditions is likely to require more than a single rate hike.
Markets Price Multiple Rate Hikes
Source: Bloomberg
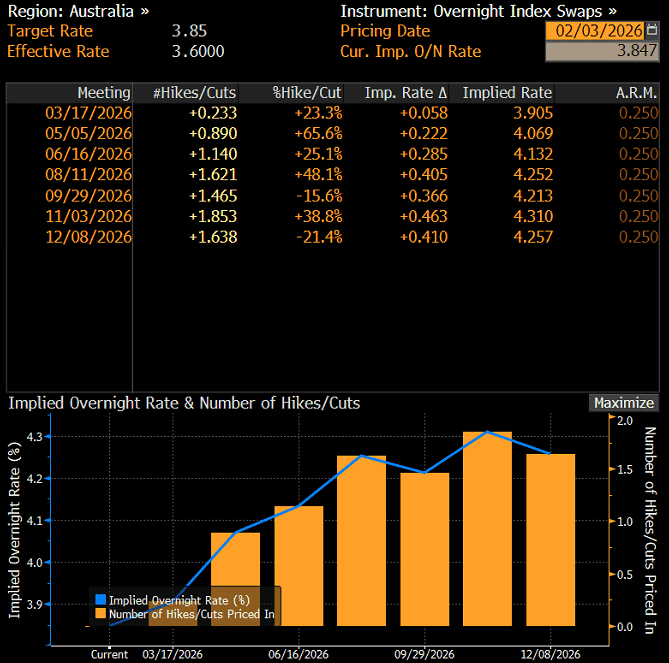
Markets have moved quickly to price a longer tightening cycle. By the RBA’s May meeting, when the Q1 inflation data is available, a follow-up 25bp hike is bordering on a lock at 89%, according to swaps markets. That’s not unusual given the RBA has often delivered multiple moves early in a cycle following quarterly inflation reports.
By August, when the Q2 data is available, an additional hike to 4.35% is seen as a roughly two-in-three chance. That looks about right given the run of data recently, which has come in on the firm side of expectations more often than not for key indicators.
The risk around whether we see fewer or more hikes this cycle appears premised on fiscal policy decisions in the federal budget, labour market trends and developments offshore.
Neutral policy settings, where inflation and unemployment are stable, arguably sit above the current cash rate. That raises the risk the RBA may need to deliver more hikes than are currently priced to re-establish equilibrium in the economy.
AUD/USD Surges, Reclaiming .7000

Source: TradingView
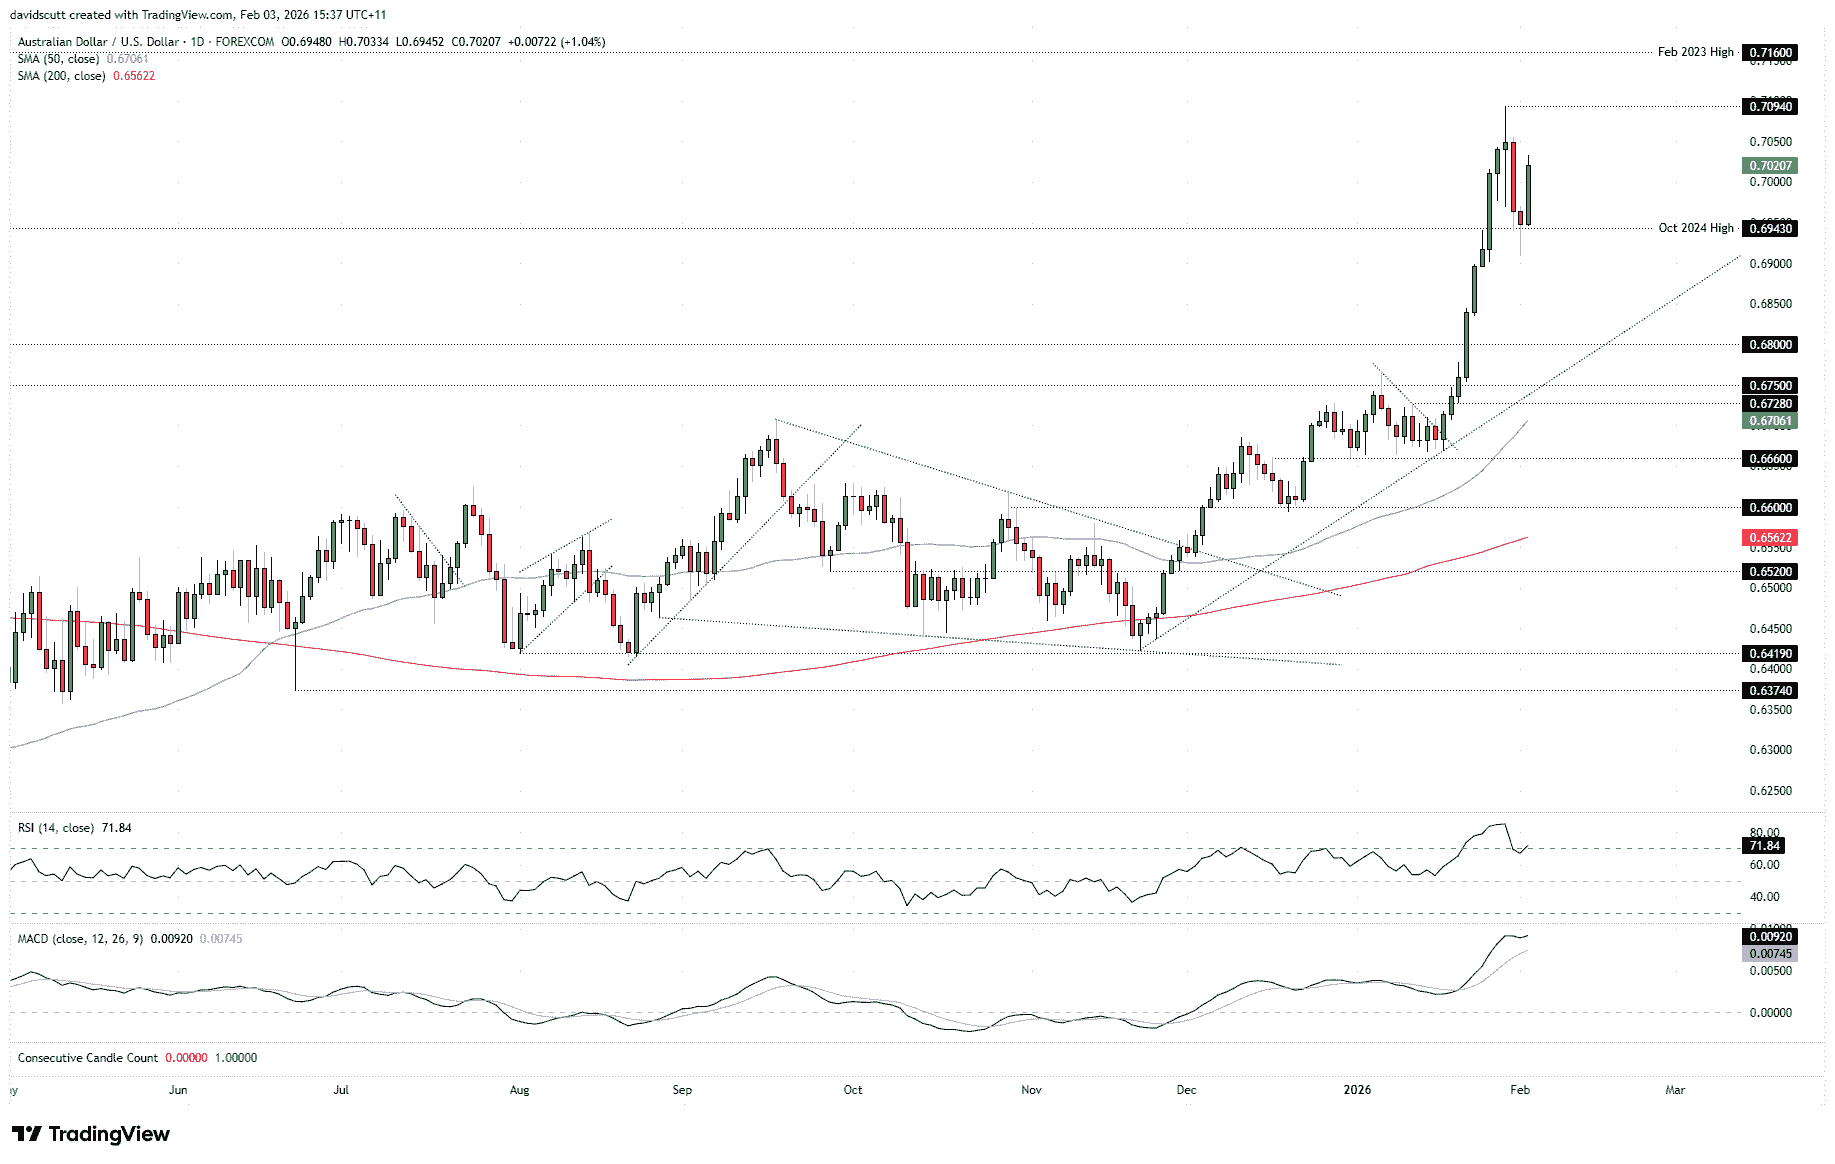
Naturally, the RBA’s hawkish hike delivered a sharp upside response in AUD/USD, pushing the pair back above the psychologically important 0.7000 level. Momentum indicators are confirming the move, with both RSI (14) and MACD showing upside strength accelerating. From here, bulls will be eyeing a retest of the January 29 high at 0.7094, particularly after the failed bearish break below the October 2024 high earlier this week, which produced a clear hammer candle on the daily chart.
While there is little to dislike about the Aussie from a domestic perspective, broader risk appetite remains fragile, which may limit how far the rally can extend in the near term, especially with the pair already looking somewhat stretched. That said, a sustained break above 0.7094 would put a retest of the February 2023 high back into play, with the 0.7250–0.7280 zone another key area to watch after marking multiple failed bullish breakout attempts in prior years.
On the downside, initial support sits at 0.6943, with 0.6900 and 0.6800 next on the radar should we see a deeper pullback. For now, the technical picture continues to favour buying dips rather than chasing strength.
Latest market news

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Price Short-term Outlook: XAU/USD Bears Face Critical Test at Yearly Lows 11 17 2026
Gold's decline is showing signs of exhaustion at major support, with a pivotal range break in focus ahead of the FOMC minutes.

British Pound Technical Outlook: GBP/USD Tests Pivotal Support—Breakdown Risk Rises 11 17 2026
Sterling bears are pressing critical support near the yearly lows, with the next reaction likely to determine whether the broader trading range survives.
US Dollar, Gold, Silver Outlook: 2026 Extremes and Key Levels to Watch
US Dollar, Gold, Silver Outlook: Major currency pairs and precious metals are testing 2026 extremes as markets price in a 25-basis-point Fed rate hike in December. However, stretched momentum indicators are bringing near-term reversal risks into focus.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.