



UK inflation surprise not a game changer
The UK inflation figures were stronger than anticipated, with headline CPI rising at a 0.6% rate rather than 0.5% that had been widely expected. The impact of Brexit was very clear as a significantly weaker pound caused the price of goods and raw materials purchased by manufacturers to soar.
Share this:

The UK inflation figures were stronger than anticipated, with headline CPI rising at a 0.6% rate rather than 0.5% that had been widely expected. The impact of Brexit was very clear as a significantly weaker pound caused the price of goods and raw materials purchased by manufacturers to soar. The 3.3% month-over-month jump in PPI input was much stronger than 0.6% expected, but it looks like most of the costs were absorbed by manufacturers as factory gate prices only rose 0.3% on the month. Still, the weakness of the pound has been sustained since the Brexit vote in June because of the Bank of England’s corresponding stimulus measures. So in the coming months, we could see further signs of rising inflation. But the potential weakness in economic growth, as a result of Brexit, would likely be disinflationary, which would offset some of the impact of a weaker currency on prices. Thus, today’s inflation data is unlikely to be a gamer changer as far as the Bank of England’s monetary policy is concerned.
Market reaction
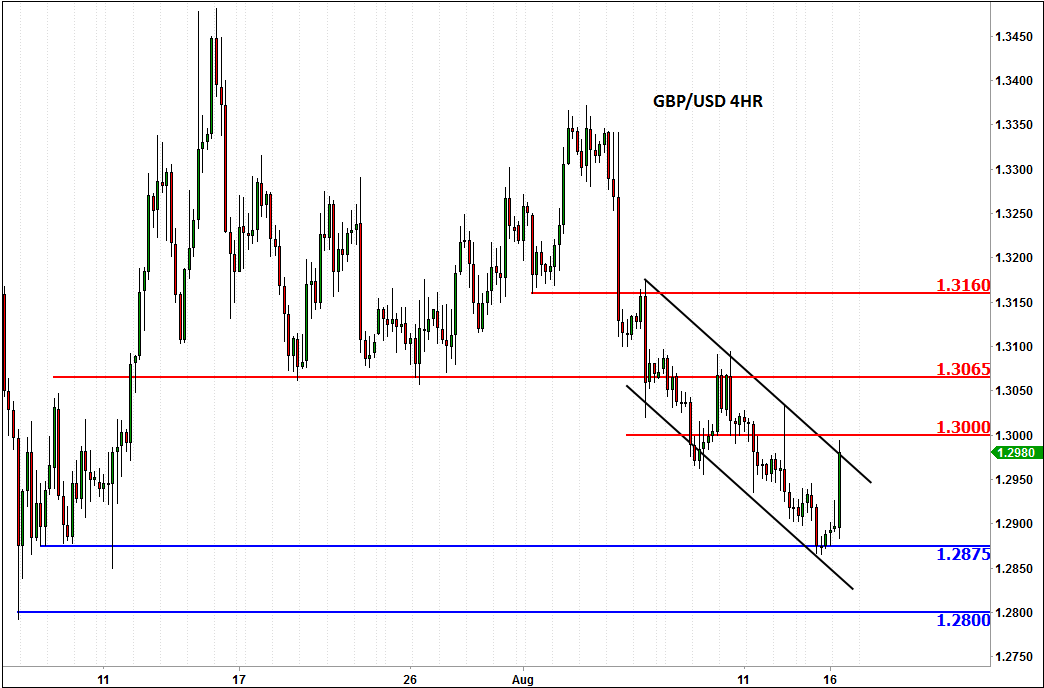
Indeed, the FTSE was able to bounce nicely off its earlier lows, although the pound held on to its earlier gains, to trade at just shy of 1.3 against the US dollar. In the afternoon, the GBP/USD could turn volatile again in reaction to the US data dump, which also includes CPI among other things. The cable is holding within its established short-term bearish channel below 1.30 at the time of this writing, although should it manage to break above this psychological barrier later then we could see price squeeze towards the next potential resistance at 1.3065. Ultimately however, the path of least resistance remains to the downside, despite today’s rally.
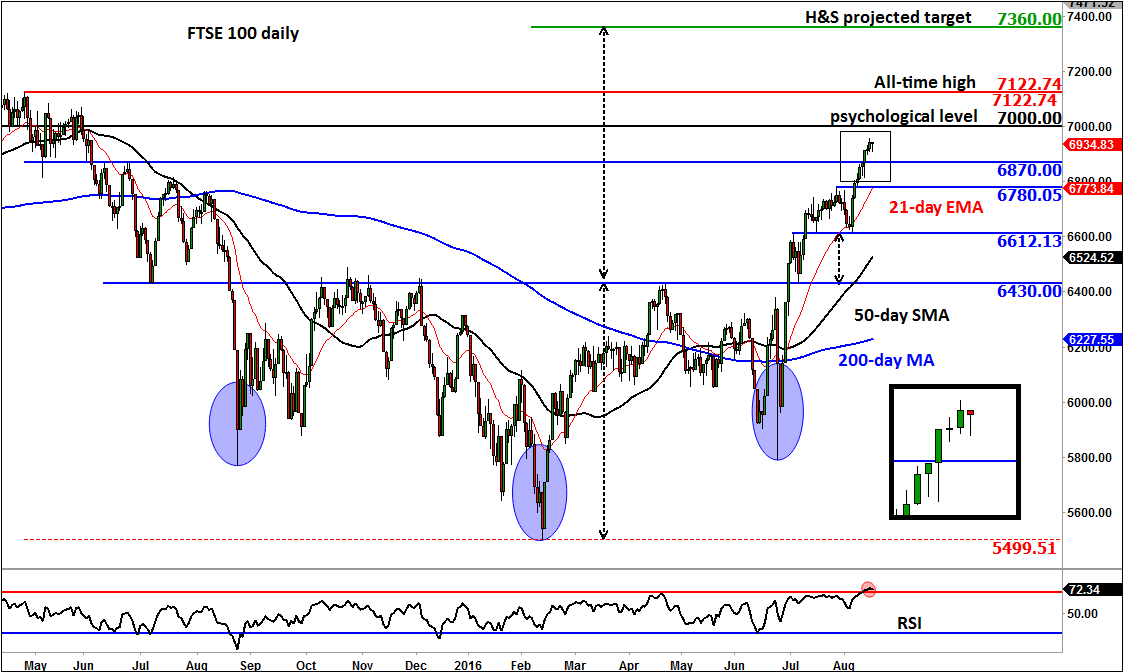
Meanwhile the domestic focus will turn to UK jobs and wages data on Wednesday. The FTSE, already among the top performing stock indices out there due to the Bank of England’s re-introduction of QE, could benefit further from potential weakness in UK data tomorrow as this would encourage the BoE to remain uber-dovish for longer. Indeed, the UK benchmark stock index has been virtually on a tear since the initial wobble post the Brexit vote. It is now not too far off the psychological level of 7000 or its prior record high of 7122 achieved in April 2015. But potentially rally could go far beyond those levels, with the projected target of the recent inverse head and shoulders pattern being at 7360 and the 127.2% Fibonacci extension of the move down from the prior record high residing at 7565. These are among our short-to-medium term bullish targets.
But the rally is beginning to look a bit stretched although a pause here, if seen, may not necessarily be a bad thing. The RSI has moved above the “overbought” threshold of 70, although it is yet to reach the extreme levels of 80 and beyond. Even if we do get a pullback, there are so many short-term support levels that could help to limit the downside, including the recently broken resistance levels such as 6870, 6780 and 6615. The long-term key support is the neckline of the inverse head and shoulders pattern at 6430. It might be a while until some of these levels are revisited again, as we believe a bullish breakout to new all-time highs is a more likely outcome than a sharp sell-off, even at these elevated levels.
Figure 1:
Source: eSignal and FOREX.com
Figure 2:
Source: eSignal and FOREX.com. Please note, this product is not available to US clients
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.