



US dollar index remains heavily pressured on tepid inflation White House changes
Two primary developments on Tuesday led to a sharp fall for the already-struggling US dollar.
Share this:

Two primary developments on Tuesday led to a sharp fall for the already-struggling US dollar. First, the highly anticipated Consumer Price Index inflation data for February was released, and it helped corroborate last week’s weaker-than-expected wage growth figures. Though the CPI was precisely in-line with consensus expectations – February headline CPI at +0.2% after January’s higher-than-expected +0.5%, and February core CPI also at +0.2% after January’s higher-than-expected +0.3% – the lower inflation readings relative to the previous month decreased expectations that the Federal Reserve will need to raise interest rates faster than anticipated. While this relatively tepid inflation data initially boosted equity markets, the dollar was pressured by the prospect of potentially diminished urgency for higher interest rates. The Fed meets next week and is widely expected to raise interest rates then by 25 basis points, but the outlook for interest rates further into 2018 and beyond will be the main focus for markets.
Shortly after the CPI release on Tuesday, an announcement that US Secretary of State Rex Tillerson has been dismissed and will be replaced by current CIA Director Mike Pompeo pressured the US dollar even further. Aside from all the investor uncertainty that continues to be generated almost daily due to incessant market-moving surprises from the White House, this dollar pressure was exacerbated by the implications of President Trump’s replacement of Tillerson with Pompeo. The outgoing Secretary of State Tillerson has been seen as a moderating voice for US foreign policy that helped to serve as somewhat of a counterpoint to Trump’s impulsive and often abrasive attitude towards other countries. Pompeo, on the other hand, is well-known for his views that mirror Trump’s hardline stance on international political issues, including the Iran nuclear deal and North Korean regime change, and is seen as having a similar anti-globalist perspective. Much of the risk of this hardline stance for the US dollar lies in the high likelihood that the top US diplomat will be yet another staunch supporter of Trump’s protectionist trade policies.
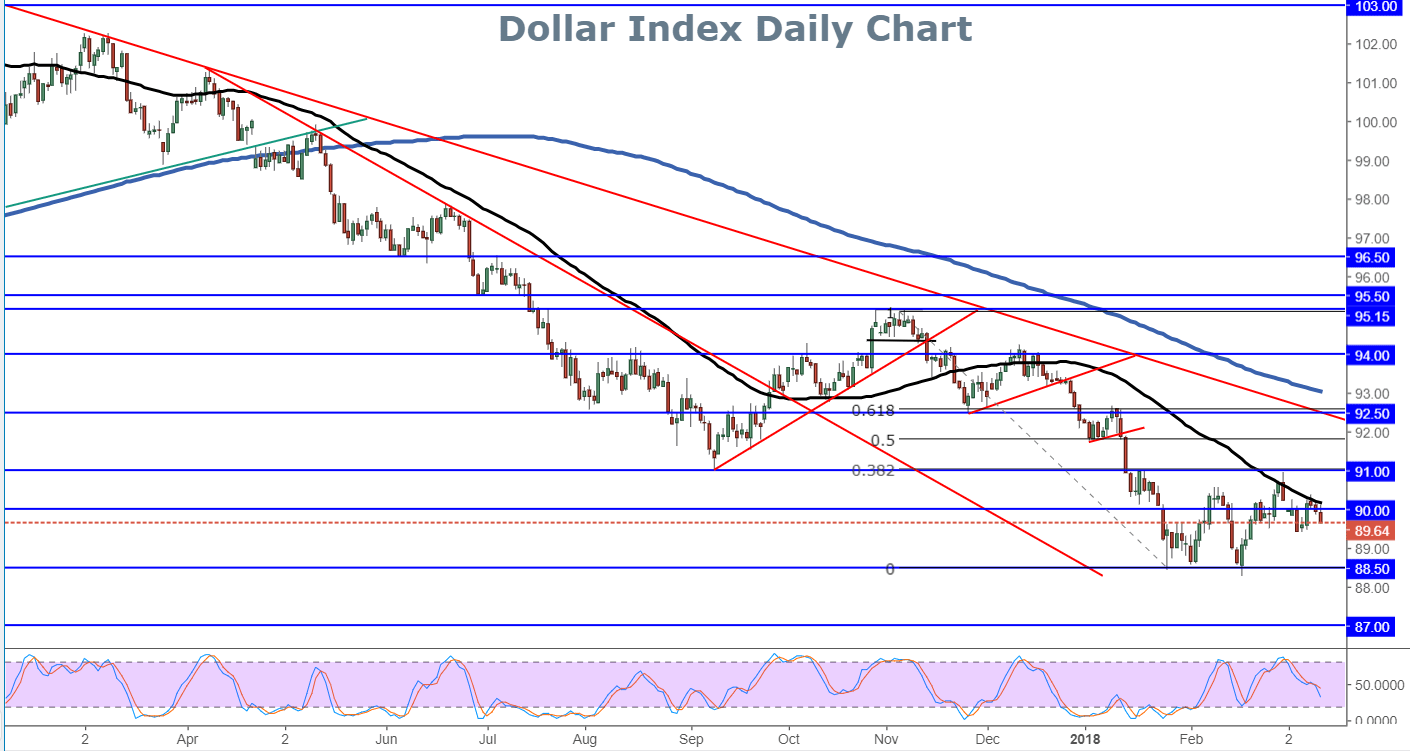
Though the US dollar index pared some of its initial losses later in the day on Tuesday, pressure on the dollar remained heavy. The index is not too far off from its mid-February multi-year low of 88.25, and is currently following a continuing downtrend outlined by its descending 50-day moving average. Both long-term and short-term trends continue to point to the downside for the weak dollar. Wednesday features more US inflation data in the form of the Producer Price Index. With any further signs of soft inflation and/or threats to global trade stability, the dollar index is potentially poised to fall once again towards its key 88.50 support area.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.