



US open: Stocks fall on Powell's comments GDP up next
After strong gains in the previous session, stocks are falling in the continued fallout from the Fed rate decision. US GDP data is due next.
Share this:

U
S futures
Dow futures +0.50% at 31910
S&P futures +0.93% at 3916
Nasdaq futures +1.5% at 12269
In Europe
FTSE -0.21% at 7360
Dax +0.01% at 13190
Euro Stoxx +0.12% at 3610
Meta disappoints, Apple Amazon to report after the close
US stocks are set to lower as investors continue to digest the latest Federal Reserve interest rate decision and look ahead to the US GDP data.
Yesterday the Fed hiked rates by 75 basis points, which was expected. However, Jerome Powell declined to provide guidance on the size of the next rate hike, given the amount of uncertainty in the economic outlook.
The Fed funds priced in a more dovish outlook following the press conference, with the market expecting a 50 basis point hike in September rather than 75 bps.
There is still plenty of economic data to get through between now and then, with two jobs reports and two inflation reports. So a lot could happen.
Attention now turns to the US GDP reading, which is expected to show that the US economy rebounded in Q2 by 0.4% annually after falling -1.6% in Q1. Two-quarters of contraction would mean that the US economy is already in contraction.
In corporate news:
Meta is falling lower after missing both revenue and earnings forecasts. This marked the first year-on-year revenue decline for the social media company. Meta reported EPS of $2.46 against forecasts of $2.54 on revenue of $28.8 billion on revenue of $28.9 billion.
Apple and Amazon are set to report after the close.
Where next for the S&P500?
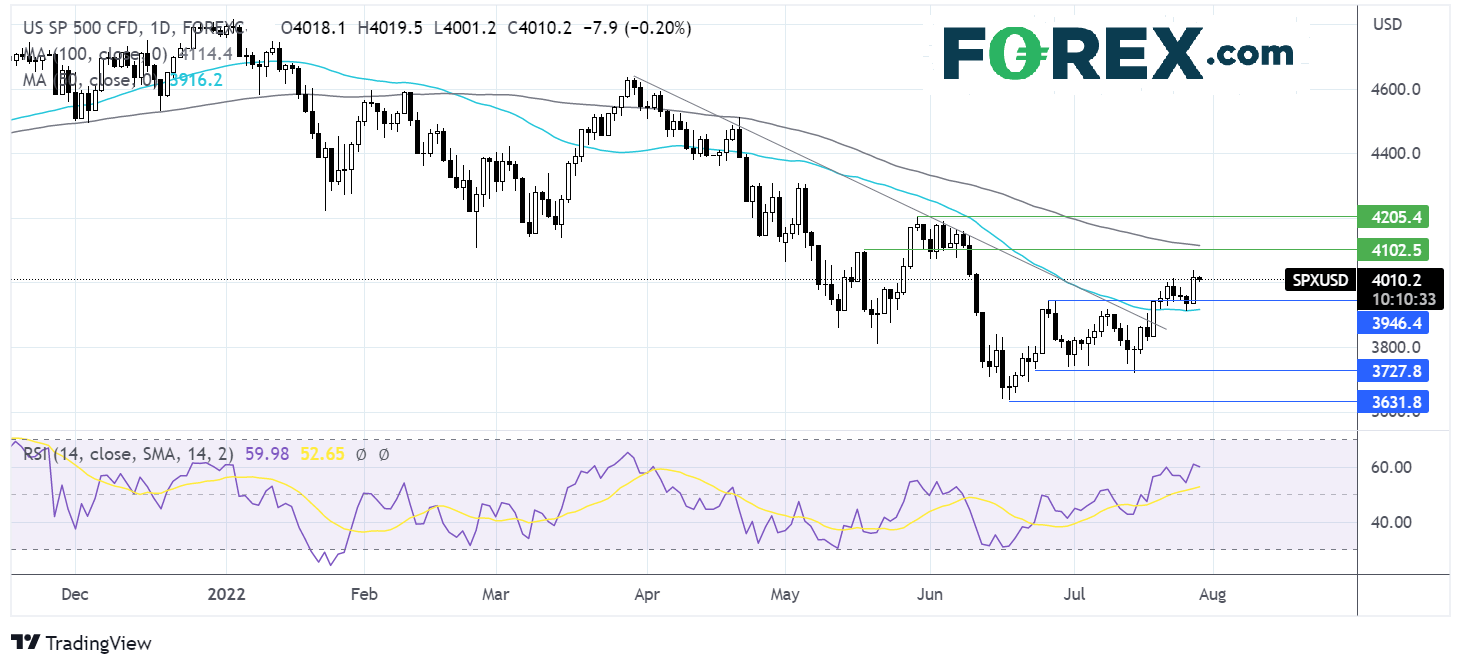
The S&P500 extended its rebound from the 2022 low of 3636. The index has risen above its 50 sma, which, combined with the bullish RSI, suggests that more upside could be on the cards. Buyers will need to rise over 4040, yesterday’s high, in order to look towards 4100 round number and expose the 100 sma at 4120. On the flip side, support can be seen at 3940, the June 27 high, and at 3910 the 50 sma, a break below here could open the door to 3735, the July low.
FX markets – USD rises, EUR falls
The initial selloff in the USD following the Fed rate decision has stalled, and the USD is rebounding higher.
EURUSD is falling after dismal eurozone consumer confidence, which tumbled by more than expected in July to -27, down from -23.8. The fall in sentiment comes as recession fears rise and amid growing concerns over the energy picture. Attention now turns to German inflation data, which is expected to ease slightly to 8.1% YoY in July, down from 8.2%.
GBP/USD is falling amid rising concerns over the health of the UK economy. The latest survey from RICS showed that the commercial real estate sector is entering or may already be in a downturn. No high-impacting UK data is due to be released, so attention turns to the BoE meeting next week.
GBP/USD -0.2% at 1.21230
EUR/USD -0.43% at 1.0150
Oil rises after inventories drop.
Oil prices are rising, extending gains from the previous session, boosting hopes of a less aggressive Federal Reserve and falling inventories.
Recession fears eased after the market interpreted the tone of the Fed at the latest Federal Reserve meeting as being slightly more dovish.
Oil prices had fallen in recent weeks on bets that aggressive Fed tightening would tip the economy into recession, hurting the demand outlook. With aggressive Fed bets being reined in the demand outlook has improved.
Separately stockpile data showed that inventories fell by 4.5 million barrels last week, more than the 1 million barrels forecast.
WTI crude trades +1.7% at $98.48
Brent trades +1.86% at $103.64
Looking ahead
13:00 German inflation
13:30 USD GDP
13:30 US initial jobless claims
US futures
Dow futures +0.50% at 31910
S&P futures +0.93% at 3916
Nasdaq futures +1.5% at 12269
In Europe
FTSE -0.21% at 7360
Dax +0.01% at 13190
Euro Stoxx +0.12% at 3610
Learn more about trading indices
Meta disappoints, Apple Amazon to report after the close
US stocks are set to lower as investors continue to digest the latest Federal Reserve interest rate decision and look ahead to the US GDP data.
Yesterday the Fed hiked rates by 75 basis points, which was expected. However, Jerome Powell declined to provide guidance on the size of the next rate hike, given the amount of uncertainty in the economic outlook.
The Fed funds priced in a more dovish outlook following the press conference, with the market expecting a 50 basis point hike in September rather than 75 bps.
There is still plenty of economic data to get through between now and then, with two jobs reports and two inflation reports. So a lot could happen.
Attention now turns to the US GDP reading, which is expected to show that the US economy rebounded in Q2 by 0.4% annually after falling -1.6% in Q1. Two-quarters of contraction would mean that the US economy is already in contraction.
In corporate news:
Meta is falling lower after missing both revenue and earnings forecasts. This marked the first year-on-year revenue decline for the social media company. Meta reported EPS of $2.46 against forecasts of $2.54 on revenue of $28.8 billion on revenue of $28.9 billion.
Apple and Amazon are set to report after the close.
Where next for the S&P500?
The S&P500 extended its rebound from the 2022 low of 3636. The index has risen above its 50 sma, which, combined with the bullish RSI, suggests that more upside could be on the cards. Buyers will need to rise over 4040, yesterday’s high, in order to look towards 4100 round number and expose the 100 sma at 4120. On the flip side, support can be seen at 3940, the June 27 high, and at 3910 the 50 sma, a break below here could open the door to 3735, the July low.

FX markets – USD rises, EUR falls
The initial selloff in the USD following the Fed rate decision has stalled, and the USD is rebounding higher.
EURUSD is falling after dismal eurozone consumer confidence, which tumbled by more than expected in July to -27, down from -23.8. The fall in sentiment comes as recession fears rise and amid growing concerns over the energy picture. Attention now turns to German inflation data, which is expected to ease slightly to 8.1% YoY in July, down from 8.2%.
GBP/USD is falling amid rising concerns over the health of the UK economy. The latest survey from RICS showed that the commercial real estate sector is entering or may already be in a downturn. No high-impacting UK data is due to be released, so attention turns to the BoE meeting next week.
GBP/USD -0.2% at 1.21230
EUR/USD -0.43% at 1.0150
Oil rises after inventories drop.
Oil prices are rising, extending gains from the previous session, boosting hopes of a less aggressive Federal Reserve and falling inventories.
Recession fears eased after the market interpreted the tone of the Fed at the latest Federal Reserve meeting as being slightly more dovish.
Oil prices had fallen in recent weeks on bets that aggressive Fed tightening would tip the economy into recession, hurting the demand outlook. With aggressive Fed bets being reined in the demand outlook has improved.
Separately stockpile data showed that inventories fell by 4.5 million barrels last week, more than the 1 million barrels forecast.
WTI crude trades +1.7% at $98.48
Brent trades +1.86% at $103.64
Learn more about trading oil here.
Looking ahead
13:00 German inflation
13:30 USD GDP
13:30 US initial jobless claims
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.

Nikkei swings harder than Nasdaq as AI fears deepen
Nikkei 225 volatility is running well ahead of Nasdaq 100, with the index construction and Japan's heavy exposure to AI manufacturing potentially explaining the difference.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.