- RBA’s Deputy Governor Guy Debelle says floor for rates here likely around 0% - 0.5%, adding they hope they won’t have to go as low as some countries (ie negative).
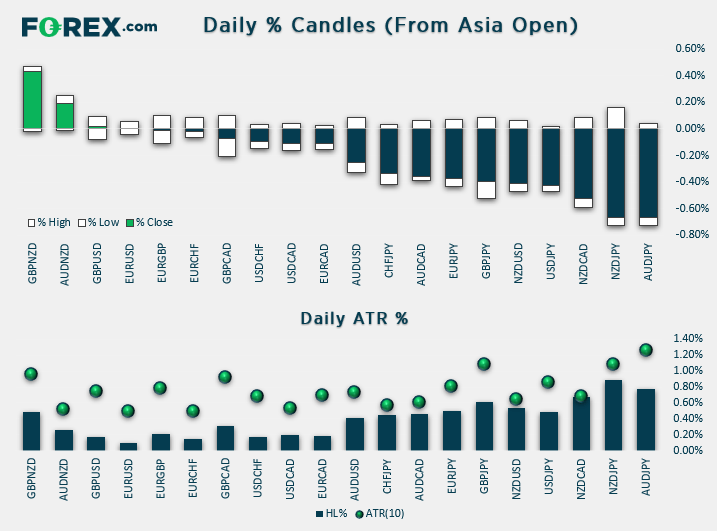
- JPY and CAD are the strongest majors, NZD and AUD are the weakest. The baulk of today’s volatility has been seen on yen pairs, with USD/JY, GBP/JPY, NZD/JPY and AUD/JPY exceeding their typical daily ranges. AUD/JPY is the largest mover, having shed nearly -0.6% at the session low.
- Japan’s Finance Minister, Taro Aso said he’s closely watching FX moves “with a sense of urgency” following the yen recent spike.
- The CNY fix was set to a fresh 11.5 year low, yet not as weak as expected. USD/CNY not trades at 7.16 and USD/CNH at 7.17.
- Philippines central bank keep the global race to the bottom alive and well, saying another 25bps cut will come by the year end.

- Asian stock markets have recouped yesterday’s losses after U.S. President Trump’s “smoothing de-escalation” comments towards China regarding the on-going trade tension. Trump said at the press conference after the G7 summit that a trade deal was around the corner after positive gestures by Beijing.
- However, it not a broad-based stellar recovery seen in Asian stocks as at today’s Asian mid-session, the Hong Kong’s Hang Seng Index and Singapore’s STI are almost unchanged. Concerns over the on-going domestic protests in Hong Kong have continued to dent sentiment despite a better than expected China’s industrial profits; it rose 2.6% y/y in Jul from a contraction of -3.1% y/y in Jun.
- Apple supplier, AAC Tech (Hang Seng component stock) has continued to underperform after it announced a weak H1 earnings result yesterday, ACC Tech has shed – 2.15% today.
- Over at Singapore’s STI, market breadth for the component stocks is lacklustre where 14 are showing gains; 14 losses and 4 at the unchanged mark. The biggest drag is Yangzijiang Shipping, down by -5.45% over uncertainty on the state of its Executive Chairman and major shareholder, Ren Yuanlin that was reported on leave since 14 Aug to assist the Chinese authorities in a confidential investigation.
- S&P 500 E-min futures is almost unchanged in today’s Asian session where it printed a current intraday high of 2886 versus a closing level of 2878 seen in the cash S&P 500 yesterday.
Up Next:
- German GDP is the final read, so tends not to deviate too much from its prior read. Although leading indicators such as German IFO business sentiment strongly point towards a recession. So a minor downgrade here could mean more than usual.
- From the US, the Richmond Manufacturing Index is of interest after it fell off a cliff last month. At -12, it as its weakest print since 2013 and, with an expectation for to ‘only’ contract at -, still leaves potential for disappointment later today if this hefty gap is not filled.
- Whilst business sentiment remains in the doldrums, consumer sentiment is soaring again and just a few points away from its post-GFC high. The argument is that consumer’s are usually the last reads to show distress I the underlying economy, so signs of weakness here could be taken as confirmation by some that the expansion is nearing an end but, for now, consumer sentiment appears quite resilient.