US futures
Dow futures 0.48%, S&P futures 0.66% & Nasdaq futures 0.83%
In Europe
FTSE 0.06% & DAX 0.01%
- Stocks rise after CPI data support Fed rate cut expectations
- CPI rose 3% YoY vs 3.1% forecast, core CPI fell to 3%
- Earnings remain supportive & big names cut jobs
- Oil rises 8% this week
Stocks rally as CPI data support Fed rate cut expectations
U.S. stocks are rising after U.S. inflation came in weaker than expected, keeping the Federal Reserve on track to cut rates.
US CPI rose 3% year on year, up from 2.9% in August, but below the 3.1% that economists forecast. Meanwhile, core inflation was cooler than expected at 3% down from 3.1% previously.
Following the CPI report, the market continues to expect the Federal Reserve to cut interest rates by 25 basis points at next week's meeting, and a December rate cut also remains likely, with the current data drought giving the Fed little reason to deviate from the path set out in the dot plot.
We know the Federal Reserve is more concerned about the health of the US jobs market than inflation right now. While government data is lacking, announcements from the likes of GM and Target highlight the Fed’s concerns.
Inflation aside, the market mood was also buoyed by news that President Trump will meet with Chinese President Xi Jinping next week during his trip through Asia. The leaders of the world's two largest economies will get together on October 30th, marking the first face-to-face meeting since the G20 summit in Osaka in 2019. The market is optimistic that the two leaders could agree to extend the trade truce.
Corporate news
Intel, the chipmaker, is surging over 7% premarket after reporting better-than-expected revenue as demand for its core X86 processors for PCs recovered.
Ford is trading over 4% higher pre-market after Q3 earnings beat expectations. The automobile maker posted EPS of $0.45, ahead of the $0.36 forecast, and revenue of $47.19 billion, well ahead of the $43.08 billion forecast.
Alphabet is trading over 1% higher after AI company Anthropic and Google officially announced their cloud partnership, a deal worth billions of dollars that gives Anthropic access to 1 million of Google's custom-designed Tensor processing units.
Target is rising after the company announced it will slash 1800 corporate jobs, around 8% of its corporate workforce. This marks the first round of major layoffs in a decade.
Nasdaq 100 forecast – technical analysis.
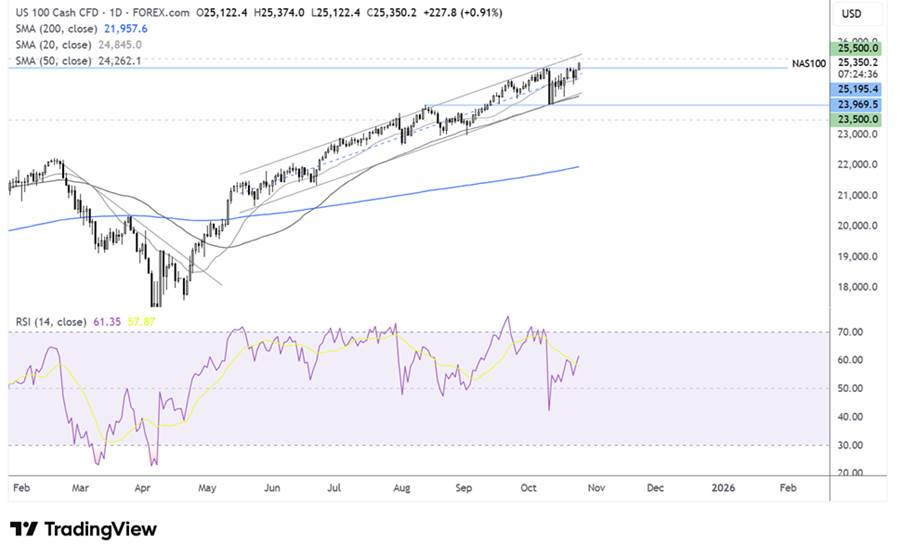
The Nadaq trades in a rising channel reaching a fresh record high of 25,300. Buyers will look to extend the bullish run towards 25,500 and 26,000. Support is seen at 25,200 and 24,850, the 20 SMA, which has guided the price higher. Below here, attention turns to 23,980. A break below here creates a lower low.
FX markets – USD falls, GBP/USD rises
The U.S. dollar is falling after weaker-than-expected US CPI data, which keeps the Federal Reserve on track to cut rates next week and potentially again in December.
EUR/USD is rising, boosted by USD weakness and stronger-than-forecast PMIs. The data showed that eurozone business activity growth accelerated to 52.2 in October from 51.2 in September, reaching a 17-month high.
The GBP/USD is rising amid a weaker USD, following UK retail sales unexpectedly rising 0.5% MoM in September, marking the fourth straight monthly increase. The data, combined with stronger-than-forecast PMIs, suggests the economy saw a boost ahead of next month's Budget.
Oil rises 8% this week.
Oil prices are rising for a fifth straight session, putting oil on track to book gains of 8% across the week, after three weeks of losses. This is the strongest weekly gain since early June.
Oil prices have steadied after yesterday’s surge, but have held onto the gains after the US imposed sanctions on two of Russia’s major oil producers, raising supply concerns. Rosneft and Lukoil, the two Russian companies sanctioned together, account for around 5% of global output.
Refiners in India, the largest buyers of Russian seaborne oil, are set to sharply cut crude imports, which increases demand for oil elsewhere.