The S&P 500 was up nearly 1% at a new all-time high today, even as European markets traded mixed, and oil held around $100 per barrel. Outside of the US, global market sentiment remained somewhat cagey. So, yet again, Wall Street was continuing to outperform European equities as investors weigh easing oil prices against lingering geopolitical risks in the Middle East, while another round of strong US technology earnings has helped support the case for higher US equity markets. The mood in Europe, however, has remained more restrained.
Oil prices were bouncing off earlier lows, but remained down quite sharply on the week after Trump insisted the ceasefire between the US and Iran was still holding despite exchange of strikes. Hopes of renewed indirect talks between the two sides have helped calm some immediate supply concerns, with markets increasingly pricing in a scenario where shipping through the Strait of Hormuz resumes normally.
Still, the situation remains fragile. Iran is reportedly seeking the removal of the naval blockade before formal talks can resume, while reports also suggest parts of the proposed US peace framework have already been rejected. So, although oil has weakened sharply in recent sessions, the downside may remain limited unless there is meaningful diplomatic progress. And that could put a ceiling on risk assets.
Until now, though, investors have effectively been pricing in a relatively favourable outcome, leaving little room for disappointment if negotiations stall or tensions flare up once again.
US Jobs beats ahead of US CPI
The latest US labour market data also added to the constructive tone. The US economy added 115,000 jobs in April, comfortably beating expectations for a 62,000 increase. Although hiring slowed from March’s revised 185,000 reading, the report still helped ease fears of a more abrupt economic slowdown.
At the same time, revisions to previous months painted a slightly softer picture overall, with February payrolls revised down to a decline of 156,000. Combined revisions for February and March left employment levels 16,000 lower than previously reported.
Attention will now turn towards US CPI data due on Tuesday, May 12. Inflation has accelerated to 3.3% year-on-year from 2.4% previously, and markets will be watching closely for signs that higher energy costs are beginning to feed more broadly into price pressures.
Any upside surprise in the inflation data could inject some mild volatility back into markets, particularly after the recent risk-on move across equities, metals and currencies. The US dollar has already softened somewhat ahead of the release, while the euro and commodity-linked currencies have found support.
Overall, market sentiment remains surprisingly resilient given the geopolitical backdrop. Wall Street, in particular, appears increasingly willing to look beyond the recent oil volatility, although European investors remain noticeably more cautious.
Technical S&P 500 forecast: Key levels to watch
The latest rally to new highs has yet again violated the bearish signal we got from Thursday’s small red candle. But if the low of Thursday’s range is now reclaimed by the bears, then this should inject some volatility back into the markets as this will show the latest push to new highs was running on empty. In that case, a decent pullback should be the result. Among the levels to watch on the downside 7,200 is the initial target below the 7,315/7,300 support. As before, the broken 7,000 level is the most important support to watch on any sizeable retracements.
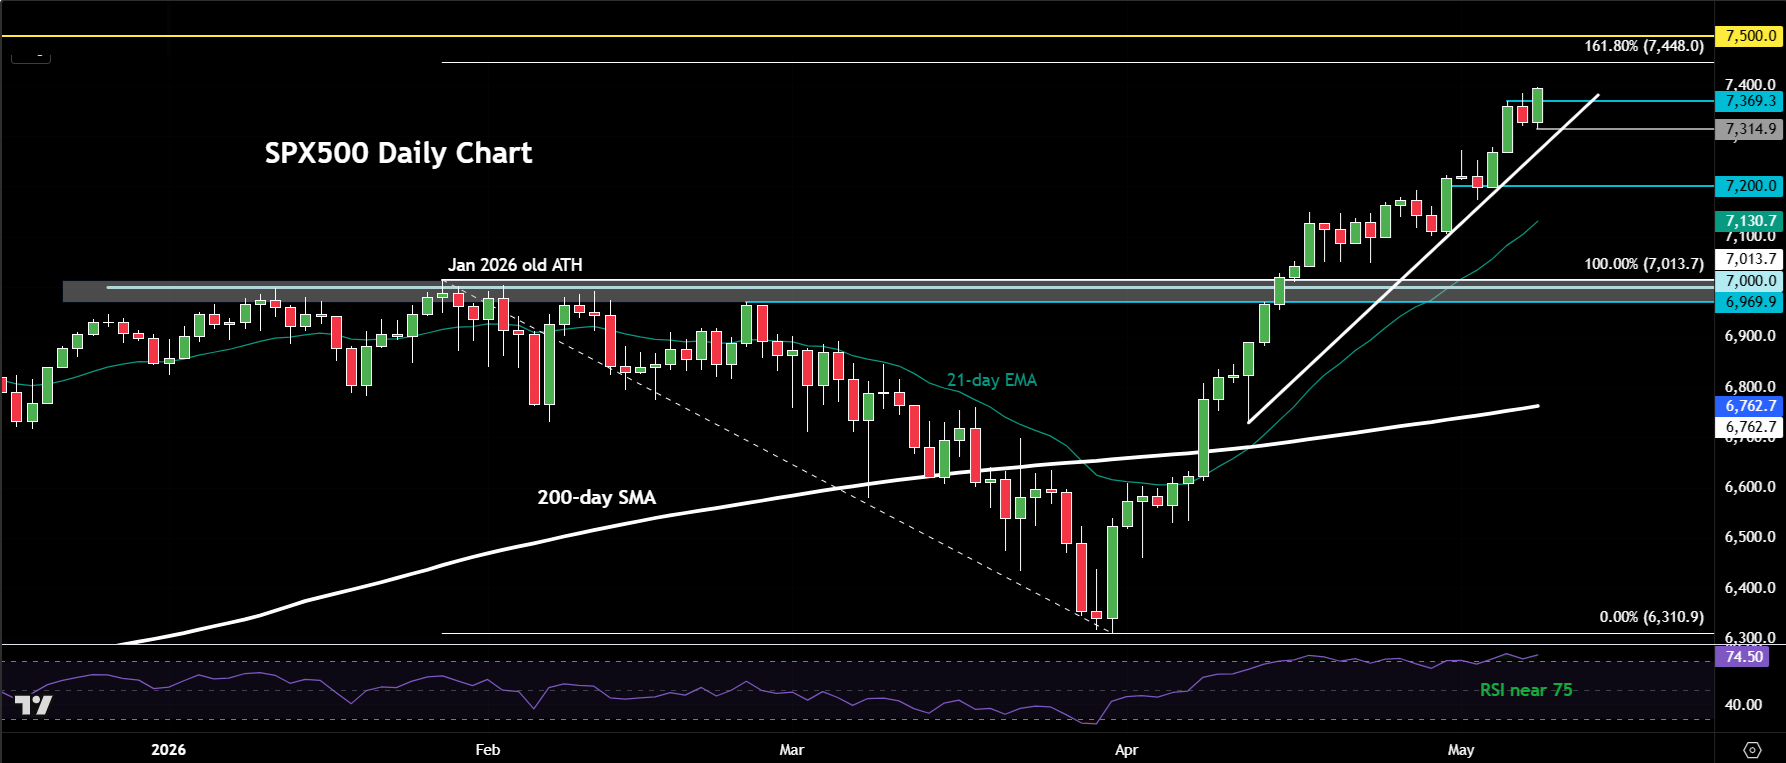
On the upside, there are no prior reference points so watch your round handles and Fibonacci extension levels where we could see some profit-taking. Until there is a clear bearish reversal, the S&P 500 forecast remains positive even though the RSI is now at overbought levels near 75.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R